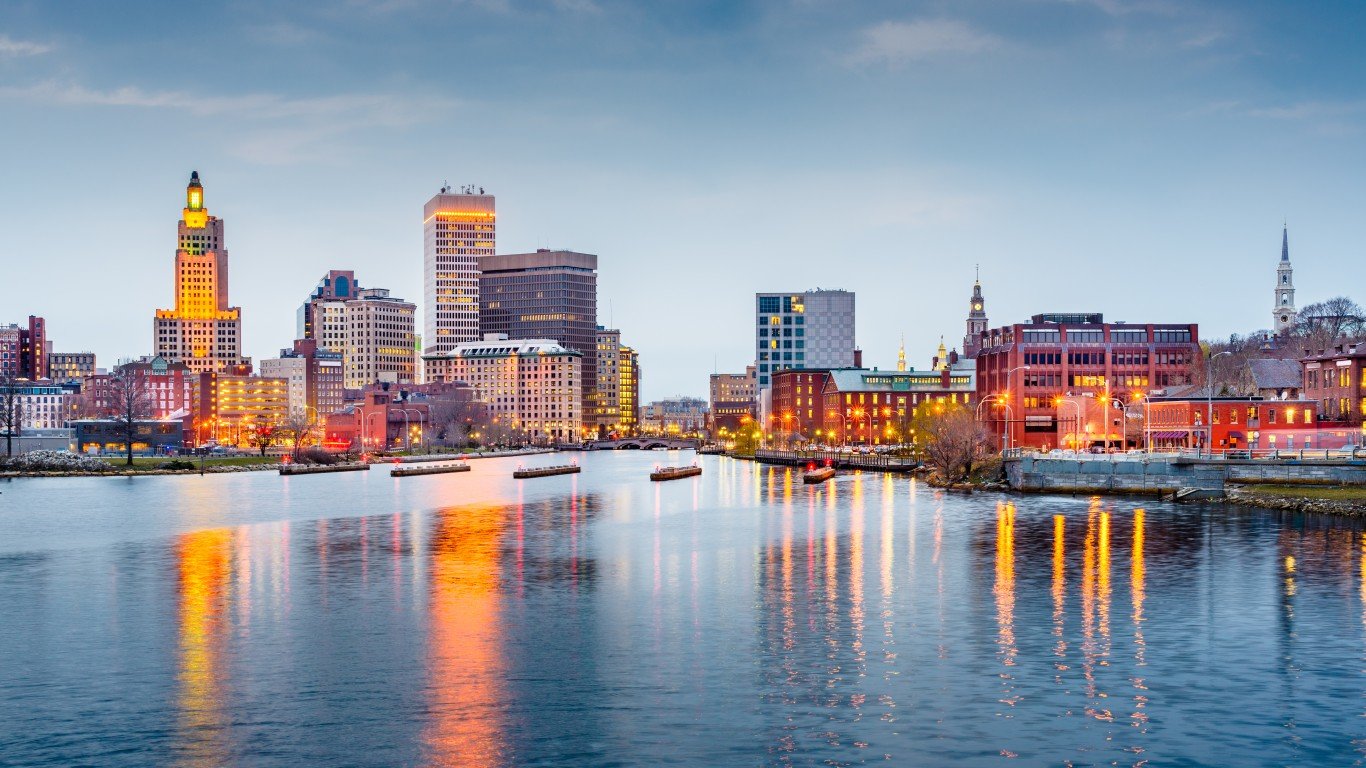
Retiring at 65 with a $900,000 nest egg sounds like a comfortable milestone, but in Providence, Rhode Island, the math is tighter than many might expect.
A married couple can make this dream a reality, but only if they enter the city with a paid-off home and a disciplined approach to their monthly spending.
The core of this financial puzzle lies in the cost of living. While Rhode Island is not the most expensive state in the Northeast—the Bureau of Economic Analysis (BEA) regional price index places the state at 102.28, notably lower than Massachusetts at 105.757—the local real estate market has been unforgiving.
With the median sale price in Providence hovering around $565,000, anyone looking to buy a home upon arrival would immediately deplete the majority of their savings, leaving them with an unsustainable withdrawal rate. The math only balances if the couple arrives with a house already owned outright, allowing that $900,000 to remain invested and productive.
The Monthly Cost of Living in Providence
Managing a household in Providence requires accounting for both the expected and the overlooked. A monthly budget for a retired couple in the city is estimated at approximately $5,807. This figure covers the essentials, from a $900 grocery bill to a $470 reserve fund specifically for home maintenance—a necessity in a city where many properties are older and require frequent repairs to roofs, boilers, and windows.
Property taxes represent a major variable in this equation. Based on Providence County’s median effective rate of 1.50%, the budget allocates $706 per month for taxes, though this can swing wildly depending on the town; a move to Cumberland might drop that burden to 1.20%, while settling in Foster could push it up to 2.08%.
Beyond taxes, the budget accounts for the reality of New England winters, estimating $225 a month for heating oil based on the consumption of an older home.
| Expense Category | Monthly Cost |
|---|---|
| Groceries | $900 |
| Property Tax | $706 |
| Medigap and Part D | $600 |
| Home Maintenance | $470 |
| Car/Transportation | $700 |
| Other Living Expenses | various minor costs |
Bridging the Two-Year Tax Gap
A critical, often-missed hurdle for retirees is the state’s tax treatment of income. Rhode Island offers exemptions on Social Security and pension income, but these perks are tied to the federal “full retirement age,” which is 67 for those born in 1960 or later.
A couple retiring at 65 will not qualify for these breaks for two years, meaning their Social Security benefits and IRA withdrawals remain fully taxable at state rates, which start at 3.75% for income up to $82,050.

To manage this, the most effective strategy involves delaying Social Security until 67. By living solely off the investment portfolio for those first two years, a couple can avoid the state tax trap while simultaneously securing higher lifetime benefits. This requires holding two years of living expenses in highly liquid, safe assets like CDs or a Treasury ladder—a move that sacrifices immediate cash flow for long-term tax efficiency.
The benefits of the city, however, remain a draw for many. Providence offers access to major teaching hospitals, the intellectual and cultural hubs of Brown University and the Rhode Island School of Design, and high-speed rail links to Boston and New York.
For those who can clear the financial hurdles of housing and the two-year tax gap, the city provides a distinct lifestyle that balances urban amenities with the character of Narragansett Bay.
Ultimately, the viability of this retirement plan rests entirely on the housing decision. If the couple must purchase a home in Providence, the remaining savings would yield only about $1,117 a month at a 4% withdrawal rate, falling short of the required $5,807 budget by roughly $1,335 a month.
The plan only clears the finish line if the house is a “sunk cost” from previous equity, leaving the $900,000 to serve as the primary engine for daily life.

Micron and Sandisk Stocks Trade at Discounts Through 2030
Memory chip manufacturers Sandisk and Micron Technology have staged a massive rally in 2026, yet market skepticism regarding...

UNC Defeats Wyoming 76-63 as Sayon Keita Records Six Blocks
First-year center Sayon Keita recorded six blocks and eight rebounds on Tuesday night to help the North Carolina...
9 Vatican Theologians Unanimously Affirm Priest’s Cause for Sainthood
Nine Vatican theologians voted unanimously to advance the canonization cause of Servant of God Father Joseph Walijewski, a...

Charleston Michelle Pauley-Lamaster Faces 32 Fraud Charges
Travel fraud allegations landed a West Virginia business owner in jail on 32 separate counts following an investigation...