
The AI infrastructure trade is hitting a wall, and CoreWeave is sitting at the epicenter of a widening credit crisis.
The market’s skepticism is no longer just about valuation; it is about the fundamental ability of capital-intensive neoclouds to bridge the gap between massive infrastructure spending and actual cash flow.
The Bottom Line:
- CoreWeave’s credit default swaps have surged 50% in the past month, trading above 1,240 basis points as lenders price in heightened default risk.
- Yields on CoreWeave bonds maturing in 2031 have spiked above 16%, as capital markets restrict access to cheap growth financing.
- Despite $5 billion in 2025 revenue, the company remains unprofitable, carrying $35 billion in total debt against $5.5 billion in cash as of the end of June.
The Alpha Metric of Distress
The most critical indicator of the current rot in the neocloud sector is the 1,240 basis point spread on CoreWeave’s five-year credit default swaps. This figure is the market’s way of saying that the cost of insuring against a CoreWeave default has become prohibitive.
When these spreads widen this aggressively, it reflects a total loss of confidence among institutional creditors who previously viewed AI-linked debt as a sure bet. According to the company’s latest earnings statement, the firm is already servicing significant debt at double-digit interest rates, including a 15% rate on a facility maturing in March 2028.
This is the “doom cycle” described by Paul Meeks, head of technology research at Freedom Capital Markets. When creditors fear for the repayment of existing debt, they tighten lending standards, forcing the company to borrow at even more exorbitant rates to fund its ongoing data center buildouts. It is a classic liquidity trap where the cost of capital outpaces the speed of infrastructure deployment.
Voters Reject Data Center Measures Amid AI Market Volatility
The volatility in the neocloud sector is not confined to the trading floors of the Nasdaq. For the everyday American, this market correction represents a cooling of the AI gold rush that has dominated headlines for two years.
Voters across the country are increasingly pushing back against the physical reality of these systems, with data center measures rejected in all but one of the 41 related measures on ballots across the country last week. This political resistance, combined with the tightening of credit, suggests that the “infinite growth” narrative for AI infrastructure is being replaced by a focus on fiscal discipline and local regulatory pushback.

“Capital markets have become more selective in the last few weeks, and the questions have undoubtedly moved from how big the contract is to whether it can be delivered, financed, and run at a profit,” said Daniel Roberts, co-CEO of IREN, during his company’s recent earnings call.
If these companies cannot secure the capital necessary to maintain their aggressive buildout schedules, the impact will ripple through the broader tech ecosystem. Major chipmakers like Nvidia, Advanced Micro Devices and Micron are already feeling the pressure, as their own revenue growth is tethered to the ability of neoclouds to keep spending. When the credit cycle turns, the hardware suppliers are often the first to see their order books shrink.
The Financing Gap
CoreWeave CEO Mike Intrator has attempted to reassure the market, noting in a recent memo that the company’s backlog remains secure. However, investors are looking past the contracts to the balance sheet. With $35 billion in debt, the company faces a massive financing gap.
Morningstar analyst Luke Yang notes that equity raises are currently off the table due to the depressed stock prices across the sector, leaving the company heavily reliant on debt markets that have become increasingly hostile.
The contrast between the bullish revenue projections of $42 billion by 2028 and the current reality of 16% bond yields is stark. Until these companies can demonstrate a clear path to profitability—moving away from the “growth at any cost” model—the credit markets will likely remain in a state of high alert.
As the sector prepares for upcoming earnings reports, the focus will remain squarely on cash burn and the sustainability of debt service, rather than the scale of new AI systems deployed.
Disclaimer: The information provided in this article is for educational and market analysis purposes only and does not constitute financial, investment, or legal advice. Always consult with a certified financial professional before making investment decisions.

Slippery Rock Men’s Basketball Opens 2026-27 Season Against Lincoln University
The Slippery Rock University men’s basketball team opens its 2026-27 season against Lincoln University on Monday at 6...
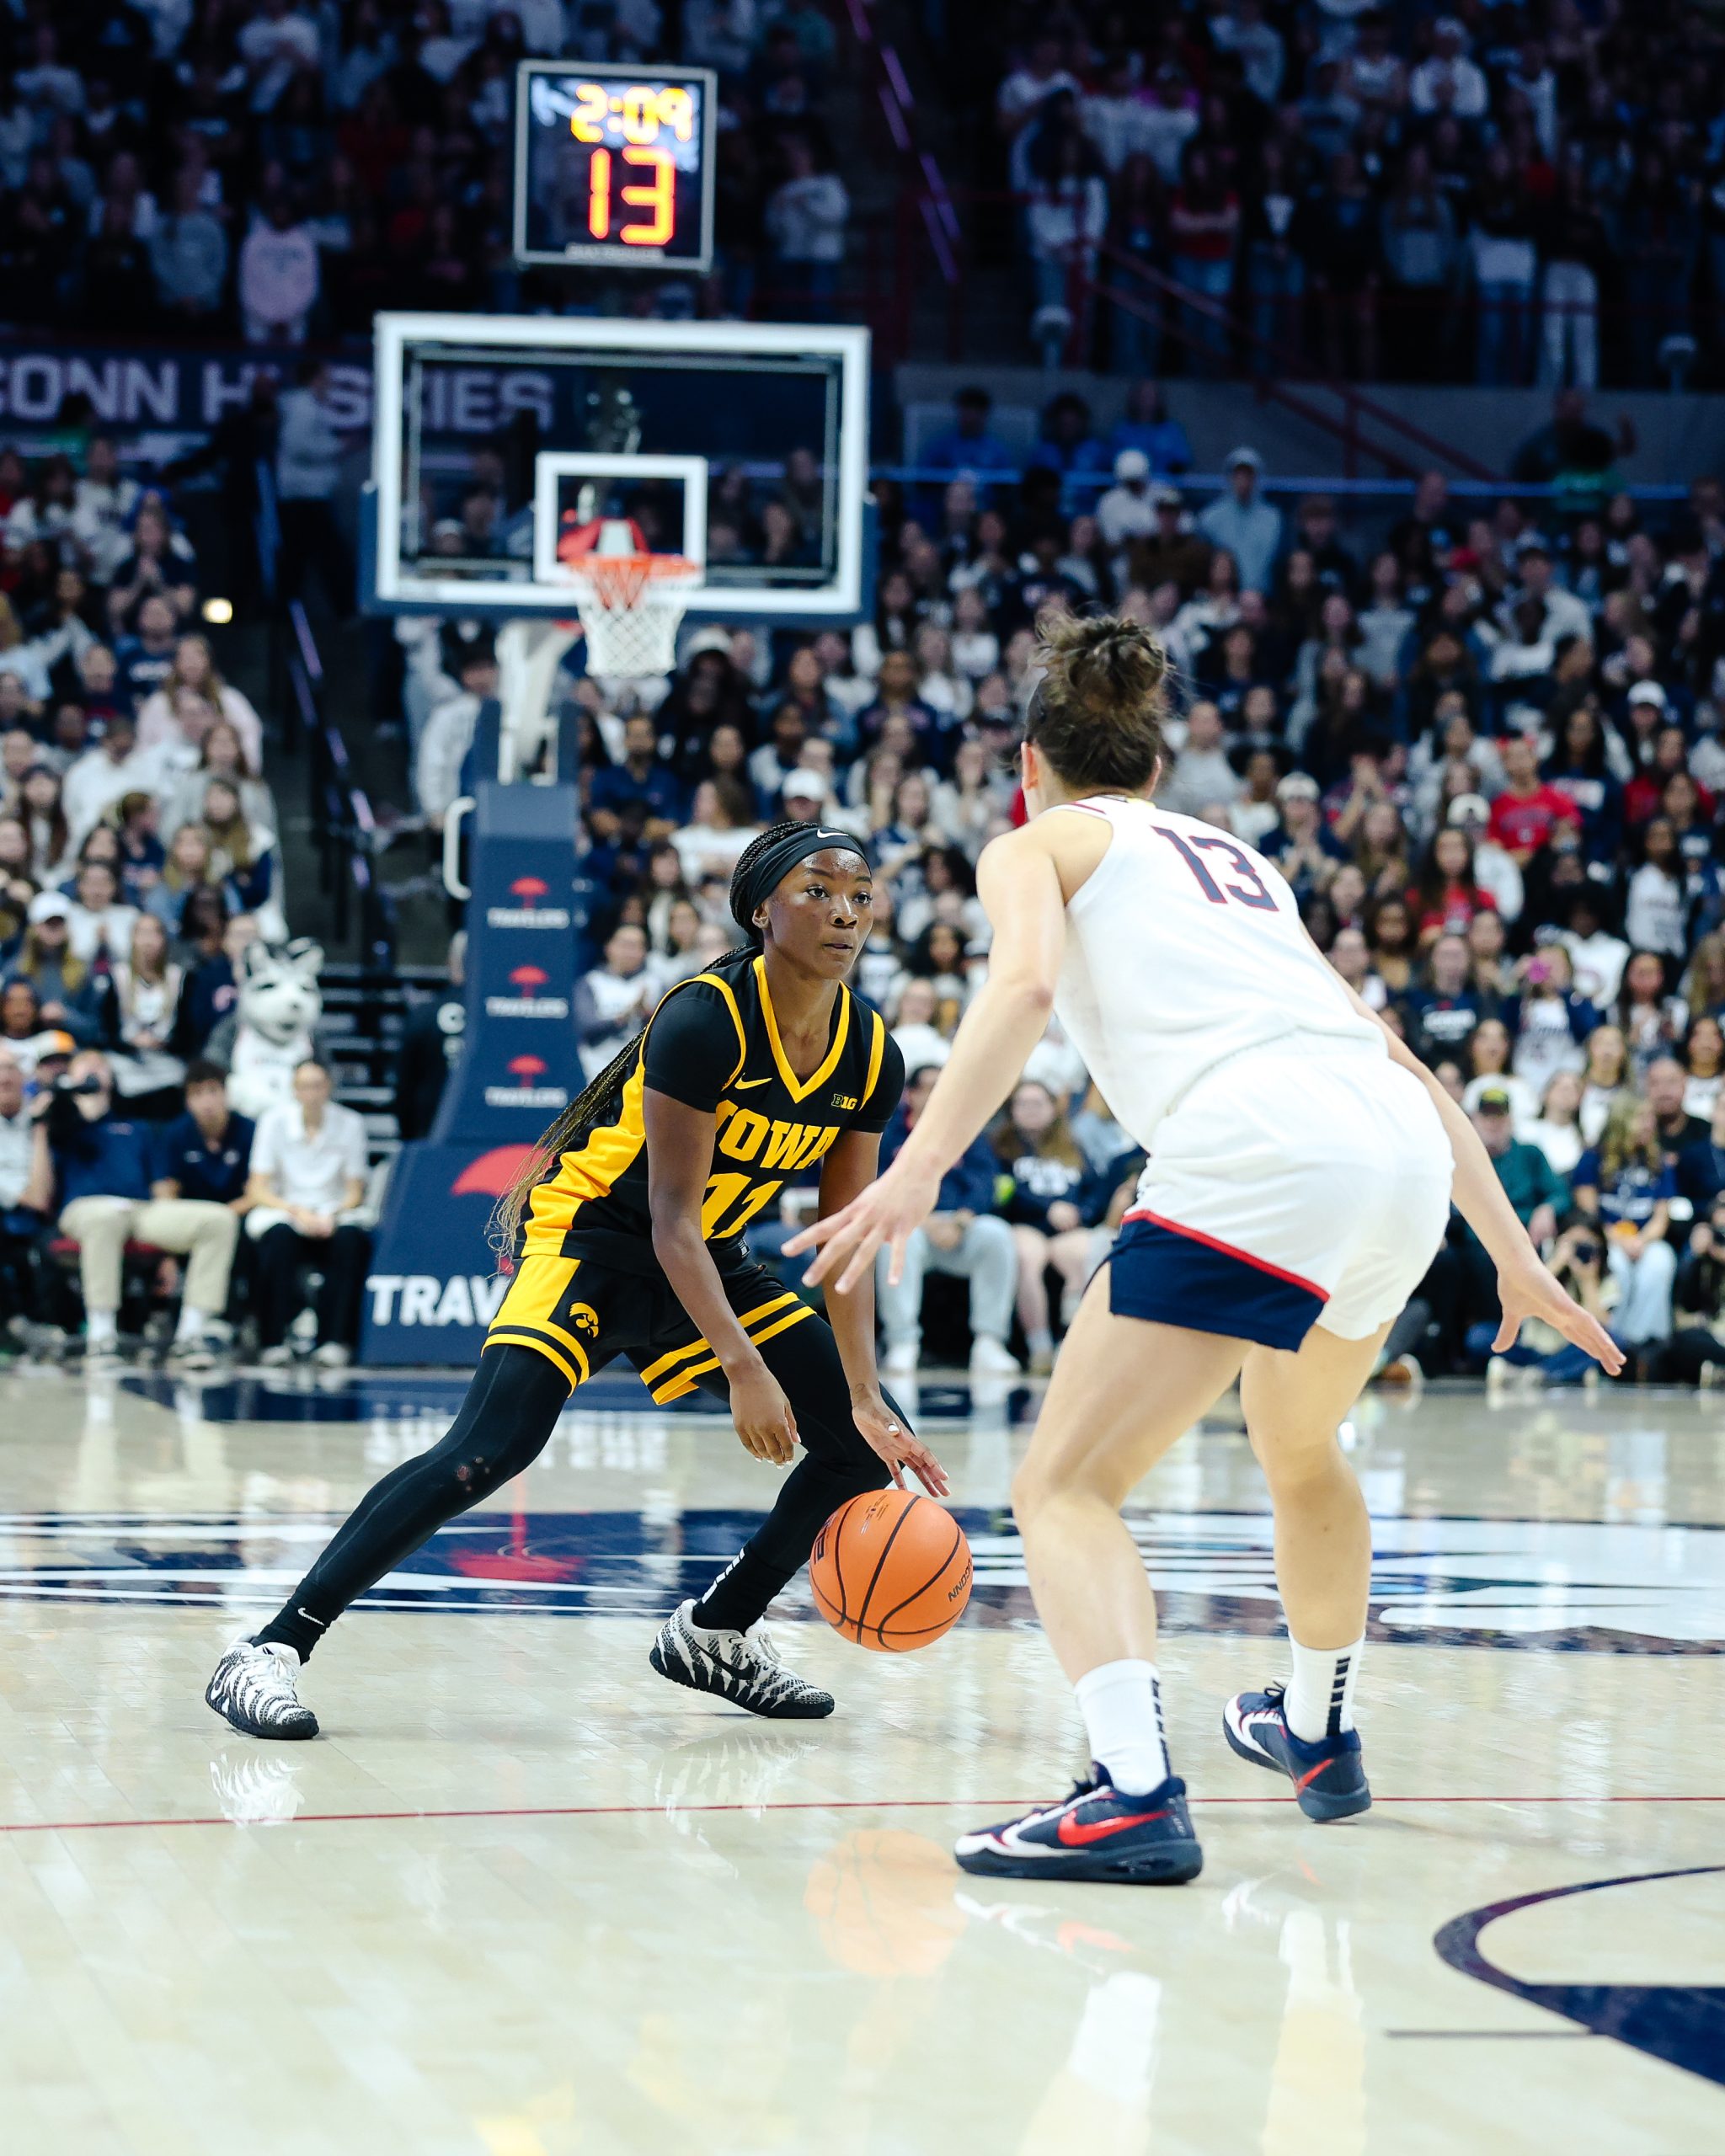
Sarah Strong Scores Career-High 39 to Lead UConn Over Iowa
Iowa Falls 91-79 at Connecticut Connecticut forward Sarah Strong scored a career-high 39 points and grabbed 10 rebounds...
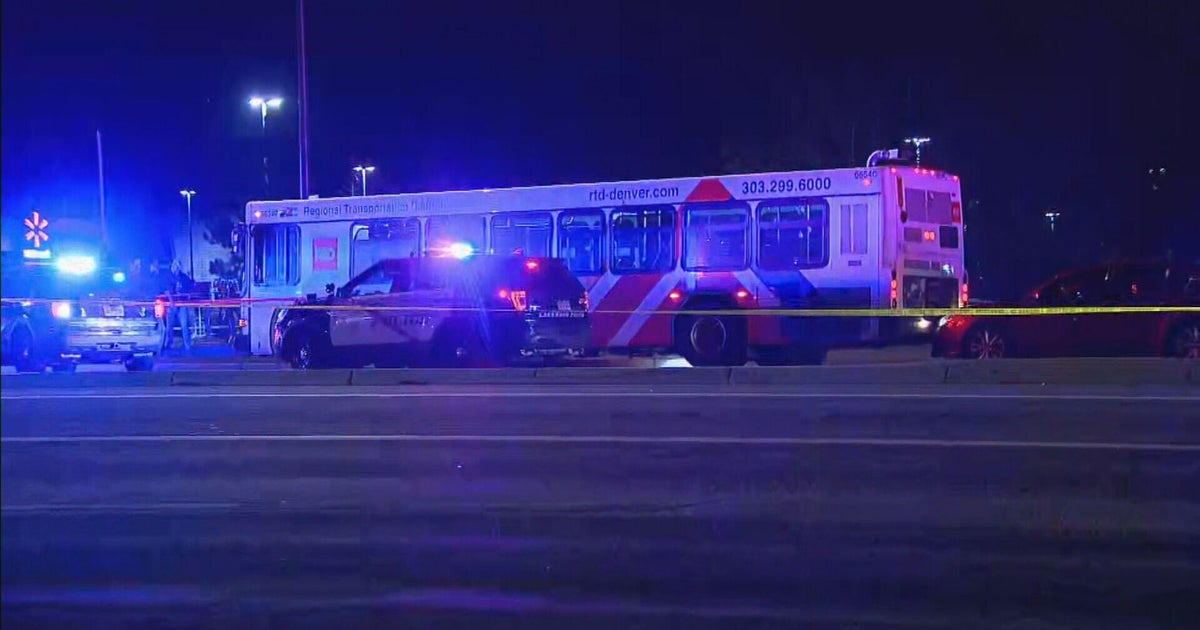
Agents, Civilian Released From Hospital Following Fatal Shooting on Denver Metro Area Bus
All three Lakewood Police agents who sustained injuries during the incident have been officially discharged from the hospital....

Arkansas Democrats Break GOP Supermajority to Gain Budget Leverage
Arkansas Democrats did not claim any statewide or federal victories in the midterm elections, but they carved out...