Big-box retailers in Michigan are challenging their property tax assessments by using the sale prices of vacant or former big-box properties to value their operational stores.
This practice, commonly known as the “dark store” issue, has created a fiscal concern for municipalities across the state, according to the Michigan Municipal League.
When retailers argue that an operational store should be valued by using sales of vacant or former big-box properties as comparables, the resulting assessment drops can be large. The Michigan Municipal League points out that the consequences of a significant decline in a major commercial property’s assessed value extend well beyond the borders of a single municipality.
Large assessment reductions can require taxing jurisdictions to refund taxes collected in previous years following a successful appeal, and the method can shift an unfair share of the property tax burden to homeowners and other taxpayers, who support essential public services, including police and fire protection, roads, libraries, and schools.
The core of the dispute lies in the use of “comparables” during tax appeals. Retailers contend that the market value of their active retail locations should be calculated by referencing the sale prices of shuttered or former big-box buildings.
However, these vacant properties are frequently sold subject to deed restrictions that limit future use or prohibit competing retailers from occupying the property. These restrictions can reduce the property’s marketability and sale price.
The Michigan Municipal League advocates for a property tax system that is fair, transparent, and consistent, ensuring it reflects the genuine cash value of commercial real estate. They are pushing for legislative measures that would enable local governments, in specific scenarios, to factor in the potential elimination of deed restrictions or other encumbrances that might artificially deflate the sale price of a comparable property.
The League emphasizes that properties used as comparables in an assessment or appeal should be genuinely comparable to the property being valued, including consideration of occupancy, condition, use, and market circumstances.
While the cost, sales-comparison, and income approaches to valuation are recognized as accepted methodologies, the application of these methods in the Michigan Tax Tribunal remains a subject of dispute. Local governments must devote many resources to defending assessments before the Michigan Tax Tribunal. The financial stakes are compounded by the prospect that large assessment reductions can require taxing jurisdictions to refund taxes collected in previous years following a successful appeal.
The Michigan Legislature has considered several proposals in past sessions intended to provide greater statutory clarity, but a comprehensive solution remains elusive. A four-bill package introduced during the 2023–24 legislative session did not become law. Michigan courts have partially addressed aspects of the issue, but disputes over the valuation methodology, depreciation, obsolescence, and appropriate comparable sales continue.
For those looking to understand the issue, the documentary BOXED IN: A Documentary about the Dark Store issue in Michigan, produced by Northern Michigan University, is available on YouTube.
The Michigan Municipal League maintains that they are not advocating assessing commercial properties above their market value. Instead, they are pushing for a system where Michigan ensures that valuations accurately reflect the property. Until the state provides clear and consistent standards for the Michigan Tax Tribunal, communities will continue to face the ongoing costs of litigation.
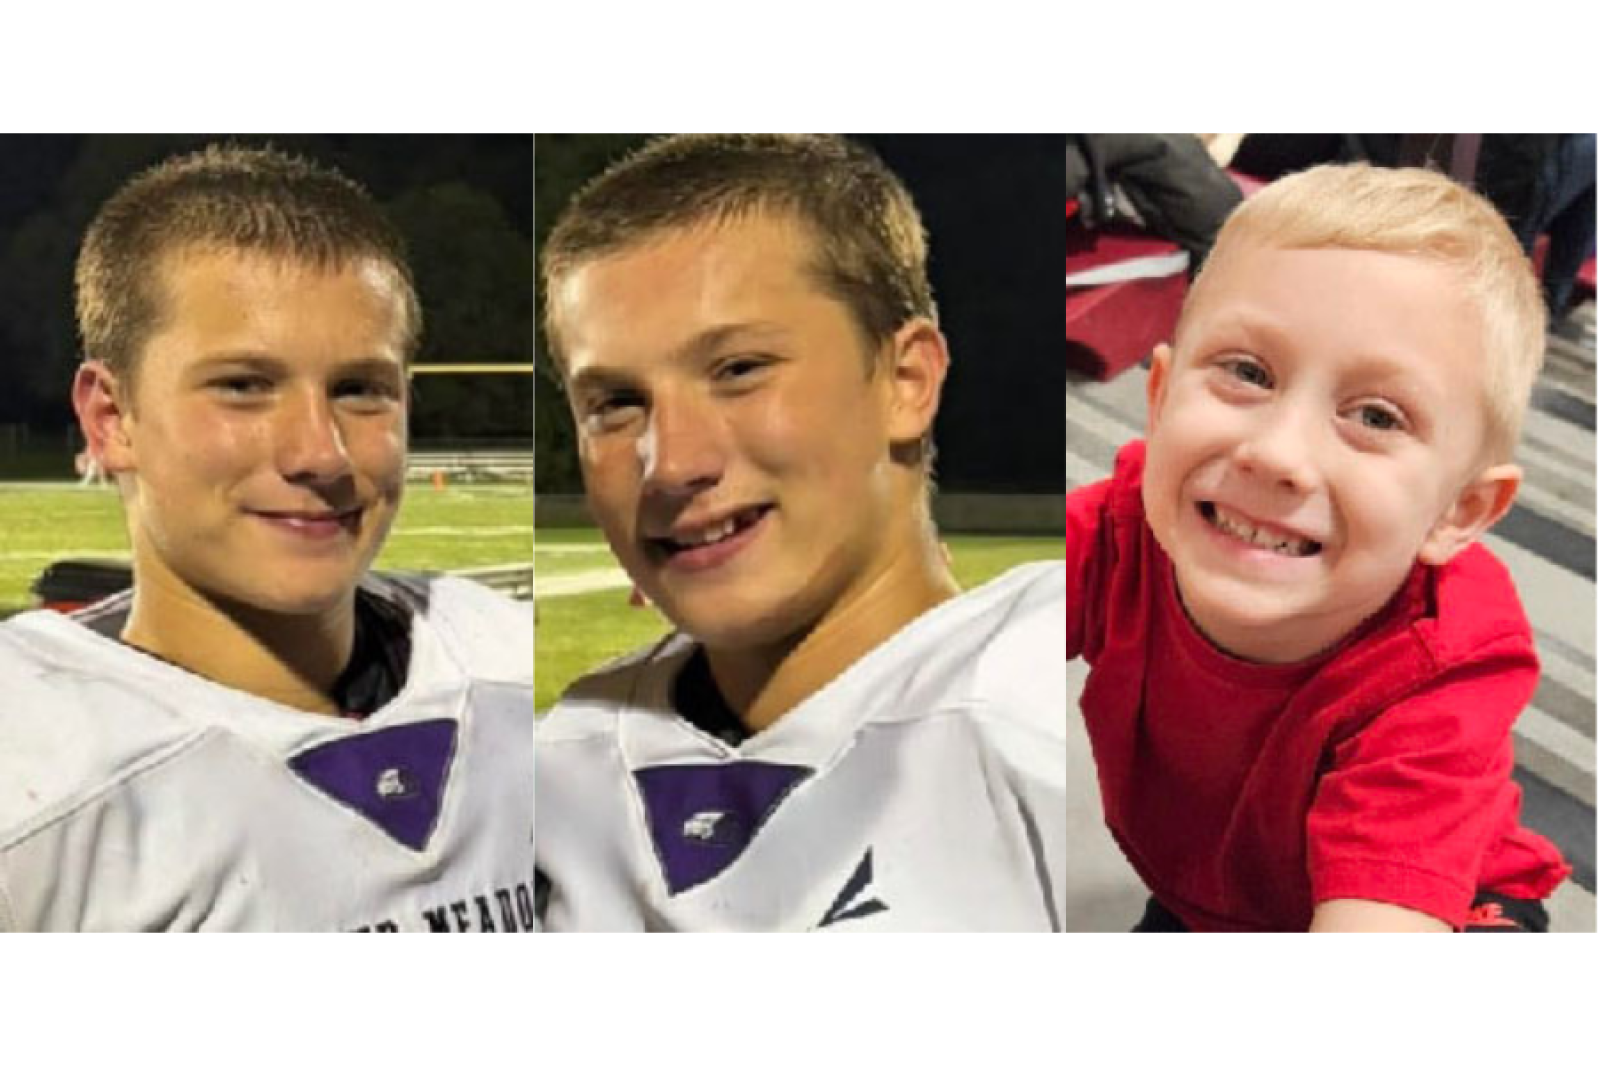
Christenson Family Deaths in Grand Meadow Fire Ruled Homicide and Suicide
Four family members discovered inside a fire-damaged Grand Meadow home Sunday died from gunshot wounds, the Mower County...

Two Die and 17 Are Injured in Brooklyn Building Collapse
Two people died and 17 others were hospitalized when a three-story building collapsed in Brooklyn on Wednesday afternoon,...
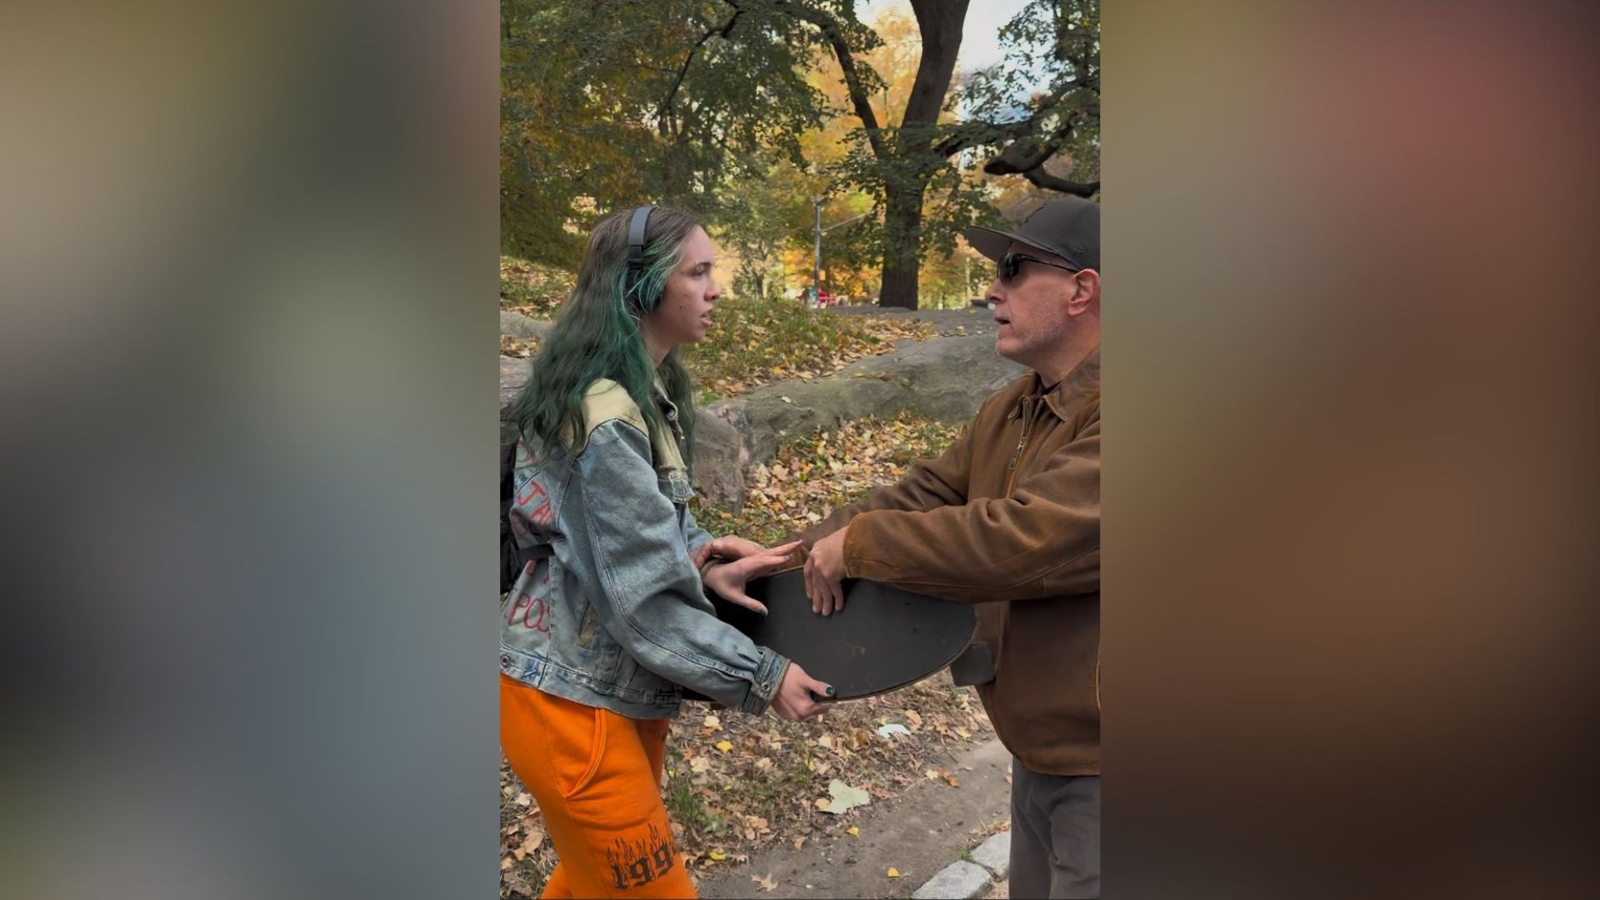
Philadelphia Woman Charged With Assaulting Central Park Carriage Drivers
Abigail Holbrook, 27, of Philadelphia was arrested and charged with two counts of assault following a confrontation with...
Alessia Mirhashemi Joins Notre Dame Women’s Soccer
The Fighting Irish announced the incoming class, which includes defender Alessia "Lolly" Mirhashemi from Rancho Santa Fe, California....