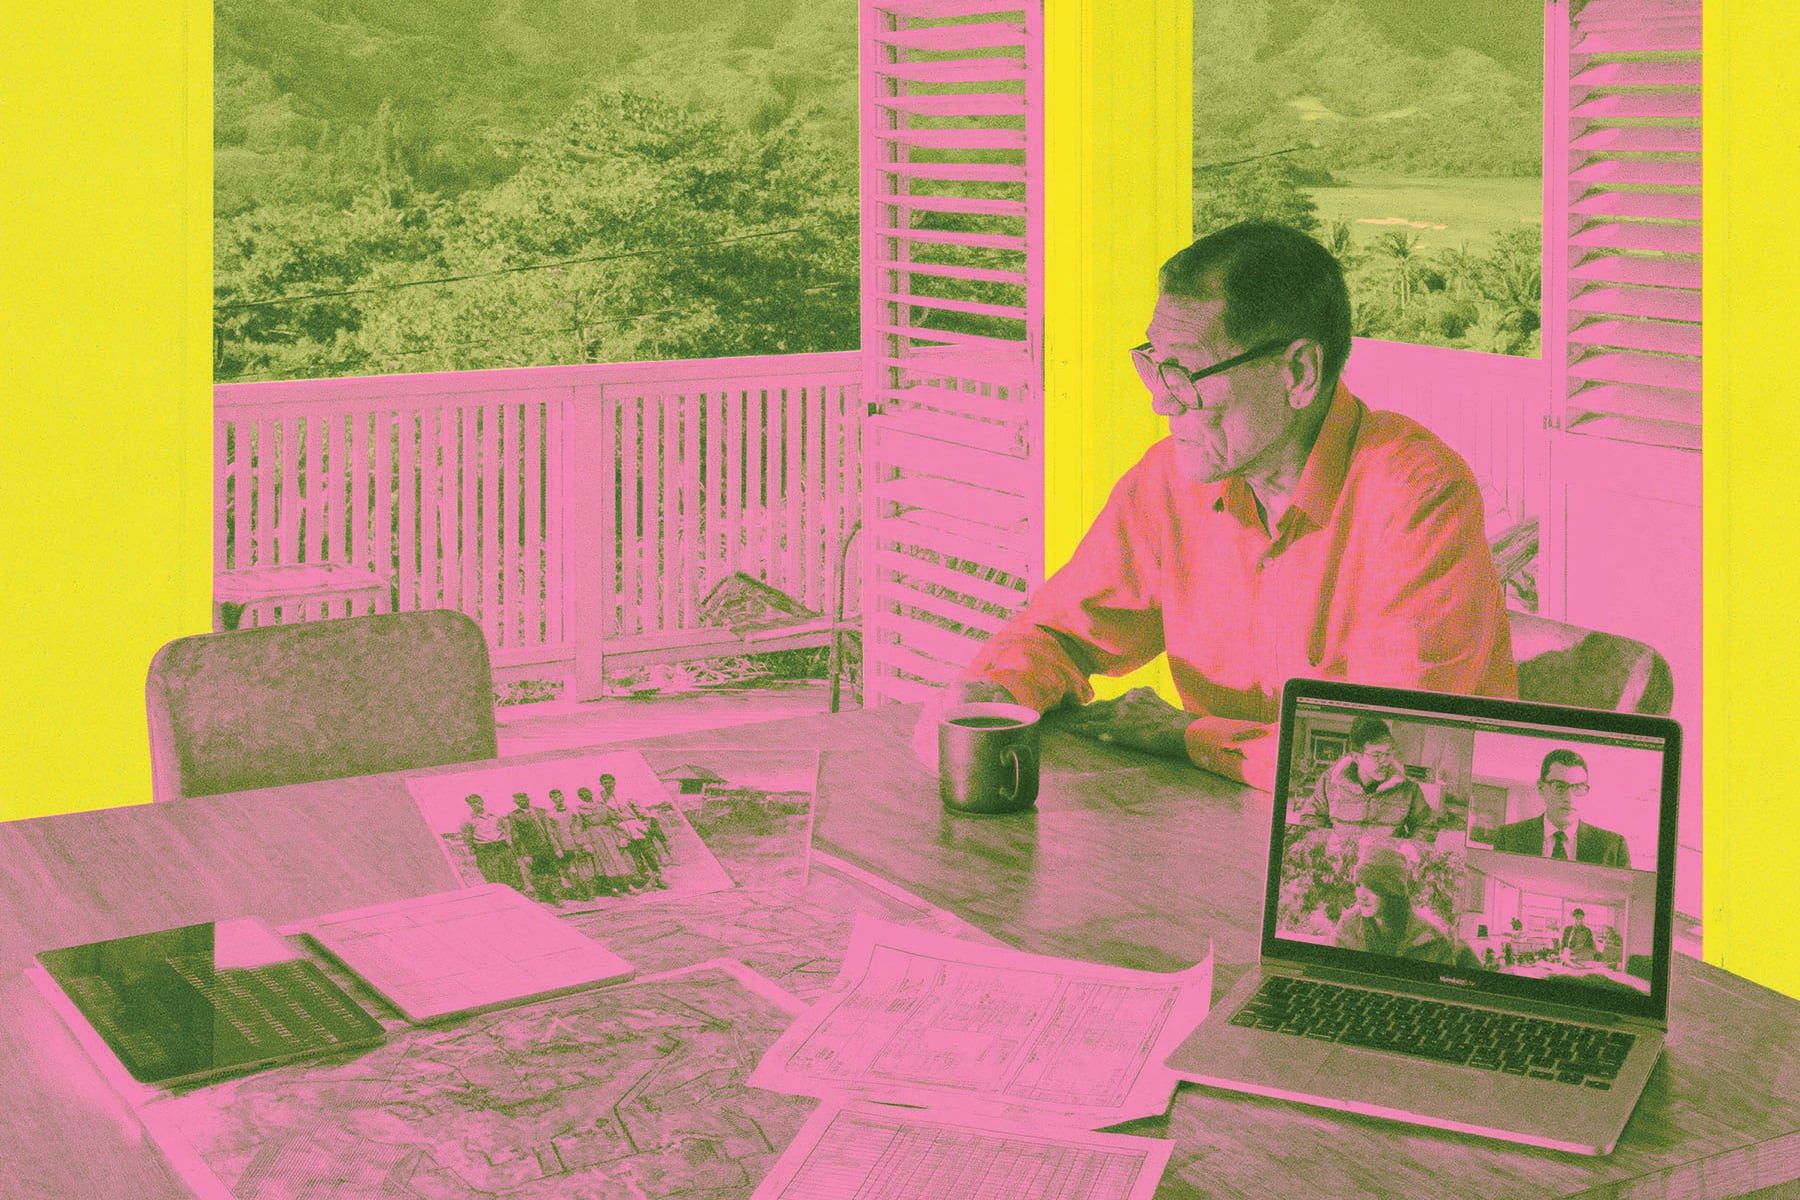
Hawai‘i families are increasingly confronting a quiet, generational crisis: the struggle to manage inherited real estate portfolios that no longer align with the disparate lives of their heirs.
The traditional mandate to hold land indefinitely—once the bedrock of local wealth—is colliding with the modern realities of estate taxes, diverse financial needs, and the geographic dispersion of family members.
For decades, the standard approach to land in Hawai‘i was simple and absolute: hold the land, do not sell. This strategy built significant fortunes, but it created a structural problem for the current generation. While the land remains a store of value, it is notoriously illiquid.
Such holdings are ill-suited to covering an estate tax obligation, funding a grandchild’s new business venture, or facilitating a buyout for a relative who prefers liquidity over owning a partial share of a property they have never visited.
The challenge is compounded by the rising costs of stewardship. As property taxes, insurance premiums, and construction and renovation budgets climb, the burden of maintaining these assets often falls on descendants who may have never negotiated a lease or walked the property line. The result is a growing tension between preserving a family’s cultural history and ensuring its financial health.
“The right question is: What job is each property actually doing for this family?”
This perspective, shared by Ray Tsuchiyama, highlights a fundamental shift in strategy. Tsuchiyama, a Hawai‘i real estate executive specializing in property portfolio strategy, suggests that families often err by starting with a valuation of their holdings. Instead, he argues, they should categorize assets by their specific utility: income generation, growth potential, or cultural legacy.
Consider a portfolio that includes a neighborhood retail center in Kapolei, a minority stake in a Kaka‘ako residential project, and a family cattle ranch on the Big Island. Treating all three as untouchable assets ignores their distinct roles.
The retail center might provide essential cash flow, the Kaka‘ako stake could represent a strategic exit for liquidity, and the ranch may remain a non-negotiable cultural anchor. The risk lies in applying a “hold everything, forever, by default” strategy to all three, which can lead to missed opportunities for refinancing or restructuring.
The economic stakes are significant. Investors from the mainland and abroad still see Hawai‘i real estate—even long-term ground leases—as an attractive and reliable asset class, giving local families a wider range of choices than their predecessors had, including the possibility of swapping their holdings for mainland properties.
Some families are already opting to recapitalize or restructure ground leases or reevaluate agricultural parcels for their highest long-term use.
The most successful families are those who initiate these, often difficult, kitchen-table conversations before a crisis—such as the sudden death of a patriarch or a tax-driven deadline—forces a decision. Tsuchiyama emphasizes that these meetings should include trustees, attorneys, accountants and real estate advisers to address four core pillars: purpose, the distinction between legacy and investment, liquidity needs, and the integration of the next generation into leadership roles.
Ultimately, the definition of stewardship is evolving in the islands. It no longer means merely keeping the deed in the family vault at all costs. Modern stewardship requires the discipline to sell, refinance, or restructure assets when doing so strengthens the family as a whole.
The families who navigate this transition successfully are those who know, with precision, which parcels are worth protecting and which can be let go in service of the family that is still here.
Keep reading
Omaha Police Investigate Linked Assaults Following Metro Bus Attack by Teens
Omaha investigators are widening their net following a violent assault on a Metro bus last week, now linking...

Raiders Staying Home for Saturday’s Opening Round to Face Montana Tech
For the fourth time in five seasons, the Southern Oregon University Raiders will open their postseason journey on...
Shops in Portage Park, Jefferson Park, Norwood Park and Gladstone Park Stock holiday gifts
Independent businesses across Portage Park, Jefferson Park, Norwood Park, and Gladstone Park are stocking shelves with locally made...
Muslim Leaders Seek FBI Probe Into ‘Heinous’ Attack on Somali Uber Driver in Hopkins
"We know it did not happen in a vacuum," Jaylani Hussein said. Muslim community leaders called for a...