The U.S. Treasury market is undergoing a fundamental structural shift as regulators and market participants move toward central clearing and digital asset integration.
The 12th annual U.S. Treasury Market Conference, held in September 2026, highlighted these transitions through discussions on modernization, innovation, and operational efficiency, according to a report from the Federal Reserve Bank of New York.
This gathering brought together the U.S. Department of the Treasury, the Federal Reserve, the SEC, and the CFTC to address how to maintain market resilience during these changes. The stakes involve the deepest and most liquid government securities market in the world, which serves as the primary financing mechanism for the U.S. federal government and a critical benchmark for global investors.
Regulators implement new Treasury clearing rules
Regulators are moving quickly to implement new rules that change how trades are settled and how liquidity is managed. SEC Commissioner Mark Uyeda provided a progress report on the implementation of the Commission’s Treasury Clearing Rule, noting that compliance deadlines remain firm. He emphasized the need for continued industry engagement to ensure the transition remains smooth, while also outlining efforts to expand clearing access through new margin-efficiency offerings.

The Federal Reserve is also refining its operational toolkit to keep pace with changing market conditions. New York Fed President John Williams discussed the evolution of the Fed’s framework, specifically pointing to the use of tri-party repo transactions and the overnight reverse repurchase facility (ON RRP) as key innovations. These tools allow the Fed to manage reserves and implement monetary policy with greater precision.
At the Treasury level, officials are looking for ways to make market programs more inclusive. Deputy Secretary of the Treasury Francis Brooke detailed recent adjustments to the enhanced Supplementary Leverage Ratio (eSLR), explaining that these reforms aim to position the ratio as a backstop to risk-based capital requirements rather than a binding constraint for banks.
He also discussed expanding the Treasury buyback program to include a limited number of non-primary dealers, which he noted “provides liquidity support directly to more market participants, reduces operational friction, and improves our trade execution through additional competition.”
Digital assets and the rise of tokenization
The intersection of traditional finance and blockchain technology emerged as a primary driver of market innovation. Panelists at the conference debated the growing presence of stablecoins and tokenized deposits, specifically whether these digital tools will expand the investor base for U.S. Treasuries or simply reallocate existing capital.
There is a growing consensus among participants that connecting digital payment rails with traditional banking rails will be essential as these technologies mature.
CFTC Chairman Michael Selig noted that the commission has been actively supporting innovation, including work on cross margining and the approval of tokenized assets in financial transactions. This push toward digitalization is expected to smooth over current market frictions through the use of tokenized products.
“Our role is to be prepared for the evolution so that there never is a cloudy day,” said New York Fed President John Williams.
Operational efficiency through repo and electronic trading
Beyond digital assets, the mechanics of how cash moves through the system are being redesigned for speed and predictability. One major proposal discussed involved investing Treasury General Account cash balances in repo to optimize the Treasury’s balance sheet. Participants suggested that early tri-party settlement would be a critical component in ensuring this process does not disrupt market functioning.
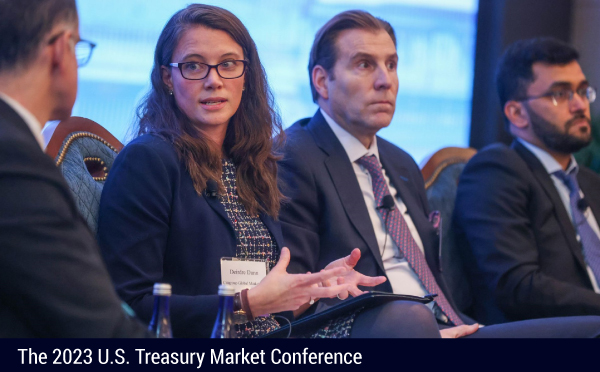
The evolution of electronic trading was another central theme. Experts discussed new protocols designed to match less-liquid products and reduce execution slippage. By bringing together cash electronic trading and futures, the market is working toward creating a more cohesive cash-futures-basis product. The transition toward central clearing for cash and repo is also underway, with interdealer brokers working to move clients toward prime brokerage and clearing models.
The following table summarizes the key regulatory and institutional focus areas identified during the conference:
| Agency/Entity | Primary Focus Area | Key Objective |
|---|---|---|
| SEC | Treasury Clearing Rule | Expanding clearing access and margin efficiency |
| Federal Reserve | Operational Framework | Refining reserves management and the discount window |
| U.S. Treasury | Buyback Programs & eSLR | Increasing liquidity support and reducing bank constraints |
| CFTC | Digital Assets & Margining | Supporting tokenized assets and cross-margining agreements |
The path toward a modernized market
While the SEC’s central clearing mandate is approaching its deadlines, the work on market structure is far from finished. The continued expansion of tokenized assets will necessitate ongoing changes to both trading behavior and underlying infrastructure. As these new policy implementation ideas from the Treasury and the Fed affect the economy, the industry faces a period of technological recalibration.
The central question remains how the market will balance the drive for efficiency with the absolute necessity of stability. As regulators push for more transparency and automation, the industry must determine if the speed of innovation can stay ahead of the systemic risks that come with a more interconnected, digital financial plumbing.
Worth a look

Columbia Mother Arrested After 9-Month-Old Baby Goes Missing
Lillian Scruggs arrested after 9-month-old goes missing A Columbia woman faces child abuse and neglect charges after her...

Harrisburg Data Center Uses Rooftop Solar for 40% of Energy
Alerify CEO defines the physical reality of the cloud A data hosting facility near Harrisburg uses rooftop solar...

Portland Trail Blazers Injury Report Ahead of OKC Thunder Matchup
The Portland Trail Blazers face the Oklahoma City Thunder at the Moda Center on Tuesday at 8 p.m....

Fargo Man Sentenced to 55 Years for Murder of Nadin Khoury
Levi Larteh sentenced to 55 years for Fargo murder A Fargo man received a 55-year prison sentence on...