The American Institute of Architects (AIA) has updated how it tracks the relationship between architecture billings and construction spending, changing how the industry anticipates economic momentum.
In a white paper titled “Clarifying the Construction Outlook by Integrating Architecture Billings with Broader Economic Indicators,” the organization reveals that while the Architecture Billings Index (ABI) remains a vital bellwether, its predictive timing has evolved.
Launched in 2005, the ABI was designed to provide a leading indicator for construction activity, operating on the logic that design work must precede the breaking of ground. However, the latest analysis from the AIA shows a slightly weaker correlation between current billings and immediate construction spending. This divergence is not a failure of the data, but a reflection of a more complex reality on the ground.
Extended project schedules are now the norm, driven by persistent supply chain bottlenecks, fluctuating material costs, and the ongoing volatility of interest rates. Because design firms are often the first to see the pipeline of future work, this shift in timing provides a new, albeit longer, lens through which developers and contractors must view the market.
According to the report, the industry is increasingly relying on a broader dashboard of metrics, including the AIA’s own Consensus Construction Forecast, to make sense of the current economic climate.
The relationship between design and construction has been tested repeatedly over the last two decades. The 2014 update to the index, titled “Designing the Construction Future,” originally sought to refine these projections by adding design contracts as a leading indicator.
That adjustment was necessary to account for the slow, uneven recovery of the nonresidential sector following the Global Financial Crisis. Today, the challenges have morphed again, with pandemic-era disruptions and political uncertainty complicating the once-predictable cadence of planning and development.
For firms operating in the AEC—architecture, engineering, and construction—space, this change matters because of the capital at risk.
When projects stall during the design phase, the ripple effects are felt across the entire supply chain, from material suppliers to financing institutions. The AIA’s updated analysis suggests that while the "lead time" for construction activity has stretched, the data provides an early warning system for those managing the current cycle.
The reliance on these indicators is not without its critics. Some analysts argue that the sheer number of variables now influencing construction—from local zoning hurdles to global commodity pricing—makes any singular index less predictive than it was in the mid-2000s.
Yet, the AIA maintains that by integrating these billings with broader economic markers, firms can better calibrate their operations against the reality of today’s extended development timelines.
As the industry looks toward the next fiscal year, the updated framework shows that the path from initial design to completed structure is rarely linear. The AIA report confirms that while the historical connection remains, the timing of that connection is now firmly tied to the broader, often turbulent, economic environment.
Related reading
Bond Denied for South Carolina Man Michael Comer in Baby’s Burial Case
A South Carolina man remains in custody after a judge denied bond for the alleged attempt to bury...

Saint Louis Volleyball Completes Reverse Sweep Against Rhode Island
Saint Louis University volleyball overcame a two-set deficit on Thursday evening to defeat Rhode Island 3-2 in Kingston,...

Jason Kelce Says Nick Sirianni Must Evolve Offense to Secure Eagles Job
Philadelphia Eagles legend Jason Kelce believes Nick Sirianni must demonstrate immediate offensive evolution and increased discipline to secure...
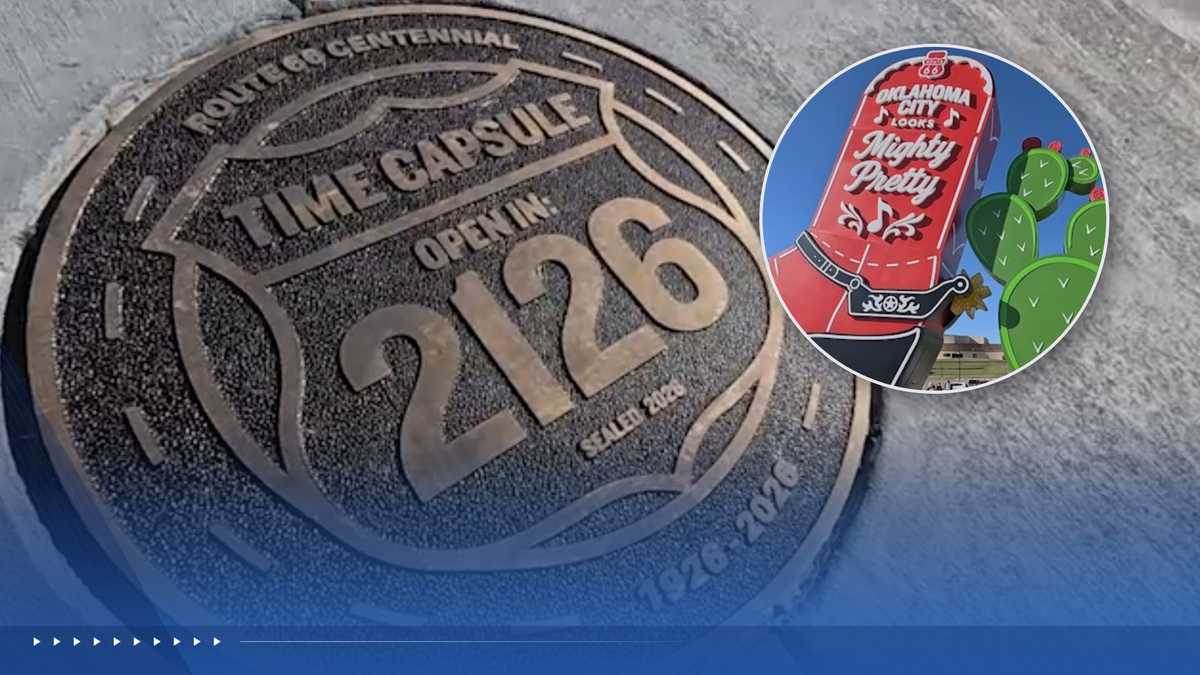
Oklahoma City Buries Route 66 Time Capsule to Open in 2126
Oklahoma City commemorated the 100th anniversary of Route 66 by burying a time capsule at the Kicks 66...