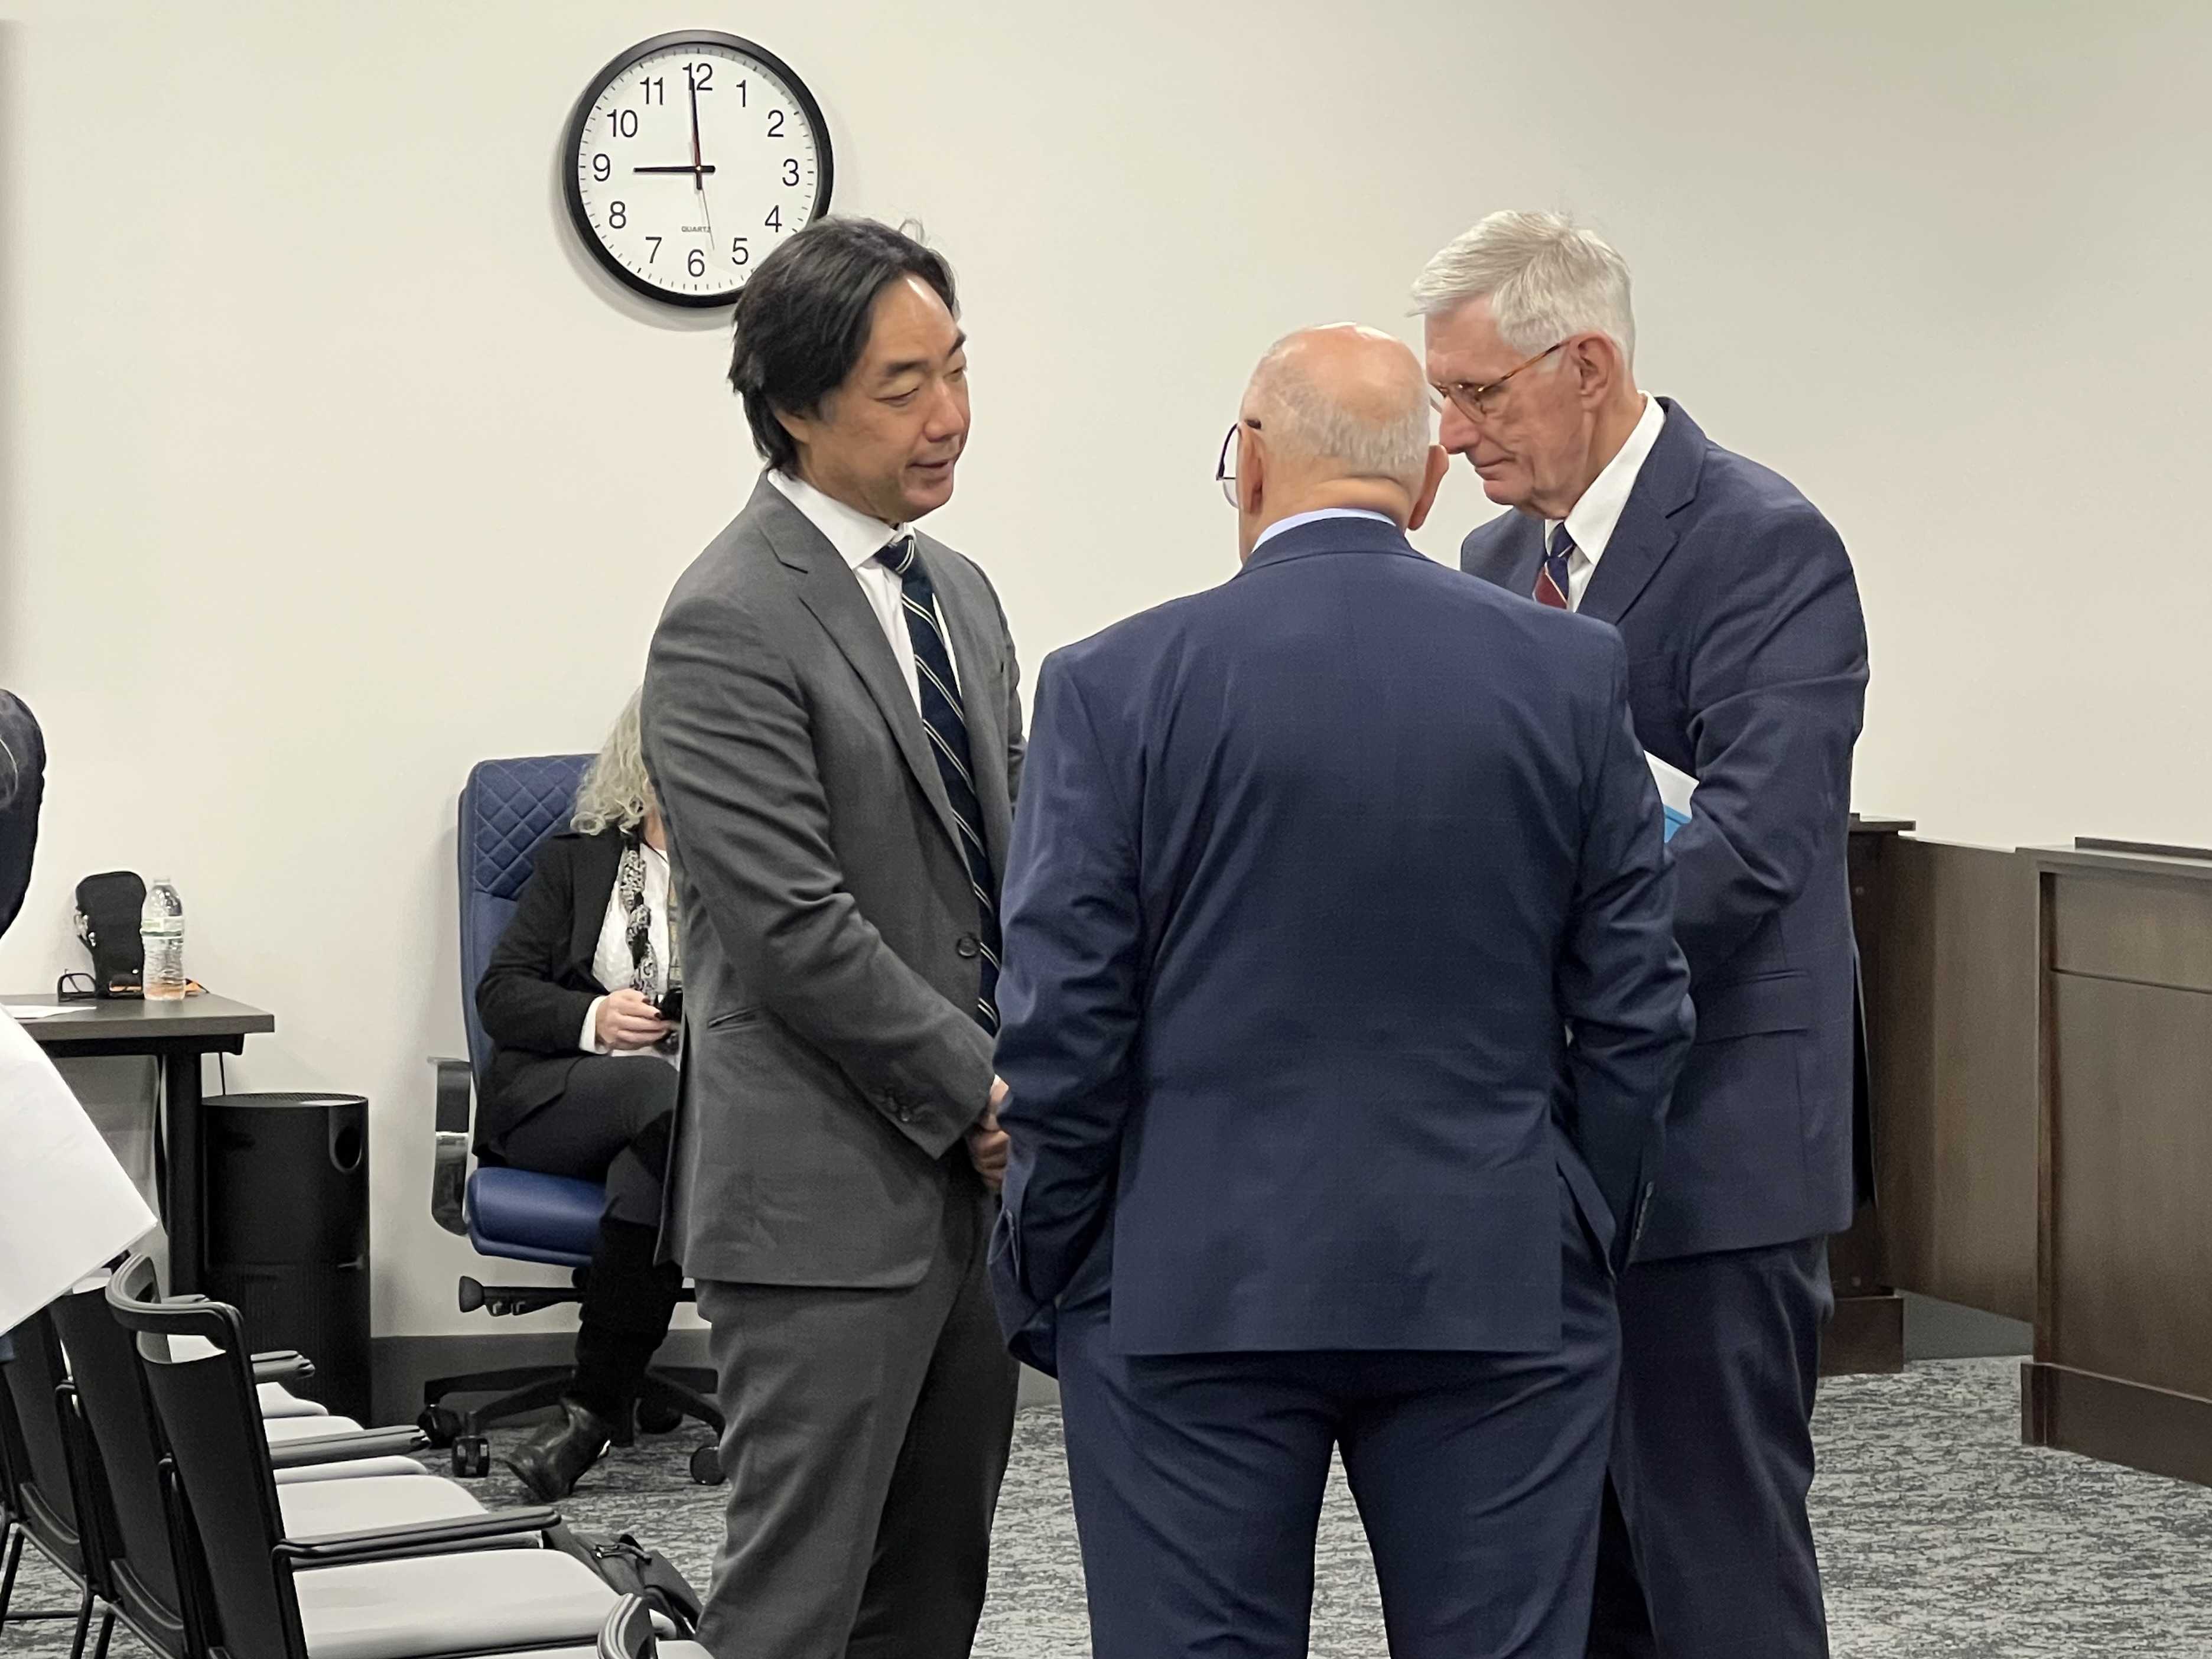
“We don’t intend to let down the state, the board, the county or the city,” Bally’s Corp. Chairman Soo Kim told the Nevada Gaming Control Board on Thursday, committing to cover an initial $250 million in financial obligations for the Athletics’ new ballpark.
The pledge came during a tense 10-minute exchange with Board Chairman Mike Dreitzer, who questioned whether the gaming company — juggling multibillion-dollar casino projects in Chicago and New York — was treating its Las Vegas obligations as “the bottom of the barrel,” The Nevada Independent reported. Kim insisted the stadium and the team are “really important assets” and that completing the work is squarely in Bally’s economic interest.
Bally’s is responsible for the northwest plaza entrance that will serve as the main access from Las Vegas Boulevard when the $2.1 billion stadium opens in April 2028.
The owner of the 35-acre site, Gaming and Leisure Properties, indicated it would cover an expected shortfall and has already earmarked $125 million from the October 2024 Tropicana demolition for Bally’s planned $1.9 billion entertainment district. The real estate trust’s commitment to the Chicago project now stands at $1 billion after a $60 million loan announced last week.

“You have an obligation to make sure that the projects that you start, you have the ability and the responsibility to finish all these projects in the best way you can,” Dreitzer said at the hearing. “It isn’t a matter of OK, let’s see what happens, especially in the state of Nevada. That’s not acceptable.”
Kim acknowledged the three-party negotiations with the A’s and Gaming and Leisure are “complicated” but said there is “still plenty of time” to build the podium connecting the Strip corners to the stadium, along with shared accessibility, utilities and parking. The Las Vegas Stadium Authority is expected to address the matter at a hearing Dec. 3.
Financial pressure on the company has intensified in recent months. Bally’s used the term “going concern” in an August filing with the Securities and Exchange Commission regarding financing for its $4 billion New York City casino resort, a warning auditors issue when they believe a company might default on its debt within 12 months.
The company’s chief financial officer resigned shortly after that filing. Last week, Bally’s said it secured $500 million from lenders to help complete its Chicago resort.
Bally’s Corp., headquartered in Providence, Rhode Island, operates 19 casinos across 11 states and online sports betting in 14. Founded in 2004 as BLB Investors to acquire the Lincoln Park greyhound track in Rhode Island, the company filed for Chapter 11 bankruptcy in 2009 and emerged under lender control in 2010.
Hedge fund Standard General took a stake in 2016, and its principal, Soo Kim, became chairman in 2019. The company went public via a reverse merger with Dover Downs in 2019 and adopted the Bally’s name in 2020 after acquiring the brand rights from Caesars Entertainment for $20 million.
Workers installed a roof truss at the stadium on Oct. 7. According to Bally’s, its obligation for 27 acres of the overall development would be finished by 2030, though it remains unclear when construction on the entertainment district will begin. A casino-resort is part of the final phase.
Worth a look

RSL Stuns Sounders 4-2 on PKs to Reach West First Round, AP Says
Real Salt Lake stunned the Seattle Sounders 4-2 on penalty kicks Thursday night at Lumen Field after a...

Ohio State Buries 16 Threes, Dismantles UMBC 101-62 for Season’s Largest Win
Ohio State dismantled UMBC 101-62 at the Schottenstein Center, burying 16 three-pointers as six different Buckeyes hit from...

Eight residents decided the future of 57 miles of road in the Town of Richmond this week
Eight residents decided the future of 57 miles of road in the Town of Richmond this week, voting...
You Cannot Be Sentenced to Jail at a Georgia Preliminary Hearing
No, you cannot be sentenced to jail at a preliminary hearing in Georgia. The proceeding is a probable-cause...