Federal Reserve data released in October 2026 shows the median retirement account balance for families headed by someone 65 to 74 reached $257,000 in 2025, up 17% from 2022 after adjusting for inflation.
- Just 49% of families aged 65–74 held a retirement account in 2025, down from 51% in 2022.
- Median retirement account balance for that group rose to $257,000 in 2025.
- Median net worth for the same age group was $431,300.
- 8.6% of families 65–74 directed over 40% of income to debt payments in 2025.
The Federal Reserve’s 2025 Survey of Consumer Finances, released Oct. 9, found that 49% of families headed by someone 65 to 74 had a retirement account such as a 401(k) or IRA, FinanceBuzz reported. That share fell from 51% in the 2022 survey, meaning roughly half of this age group has no dedicated retirement account. Some may rely on traditional pensions or have drawn accounts down.
Among those with accounts, the median balance climbed to $257,000 in 2025 from $218,900 in 2022, a 17% increase in 2025 dollars, according to figures published by KMTR. The average balance was far higher at $767,500, pulled up by a small number of very large accounts. For families aged 55 to 64, the median rose 18% to $239,000 over the same period.
Money Talks News highlighted the median net worth for families 65 to 74 at $431,300 in 2025, compared with $411,900 for ages 55 to 64 and $504,900 for 75 and older. The average net worth for the 65–74 group was $1,897,600, a figure the outlet noted is skewed by the wealthiest families.
Debt pressure increased. The SCF showed 67.7% of families 65 to 74 carried some debt in 2025, FinanceBuzz reported. The share devoting more than 40% of income to debt payments rose to 8.6% from 6.5% in 2022.
The U.S. Census Bureau said about one in four of the 58 million adults 65 and older received pension income in 2022, roughly 15.2 million people. Fidelity’s 2026 estimate projects a 65-year-old retiring this year will spend an average of $185,500 on health care in retirement, up 7.5% from a year earlier, not including long-term care. Fidelity also found 54% of pre-retirees incorrectly believe Medicare covers all health costs.
Investopedia cited advisor Spencer Lazaroff warning that ranking near the top of savings benchmarks “can create false confidence, while being on the lower end might create unnecessary discouragement.”
He said the more useful question is how much of your retirement spending must come from savings.
“What matters is whether your savings, your Social Security and your spending add up to a life you can afford for as long as you live,” a CPA writing for Money Talks News said. “Do that math once a year, and you’ll know where you stand.”
Keep reading

On Saturday, the New York Mets Secured Center Fielder A.J. Ewing to an Eight-Year
On Saturday, the New York Mets secured center fielder A.J. Ewing to an eight-year, $95 million contract extension....
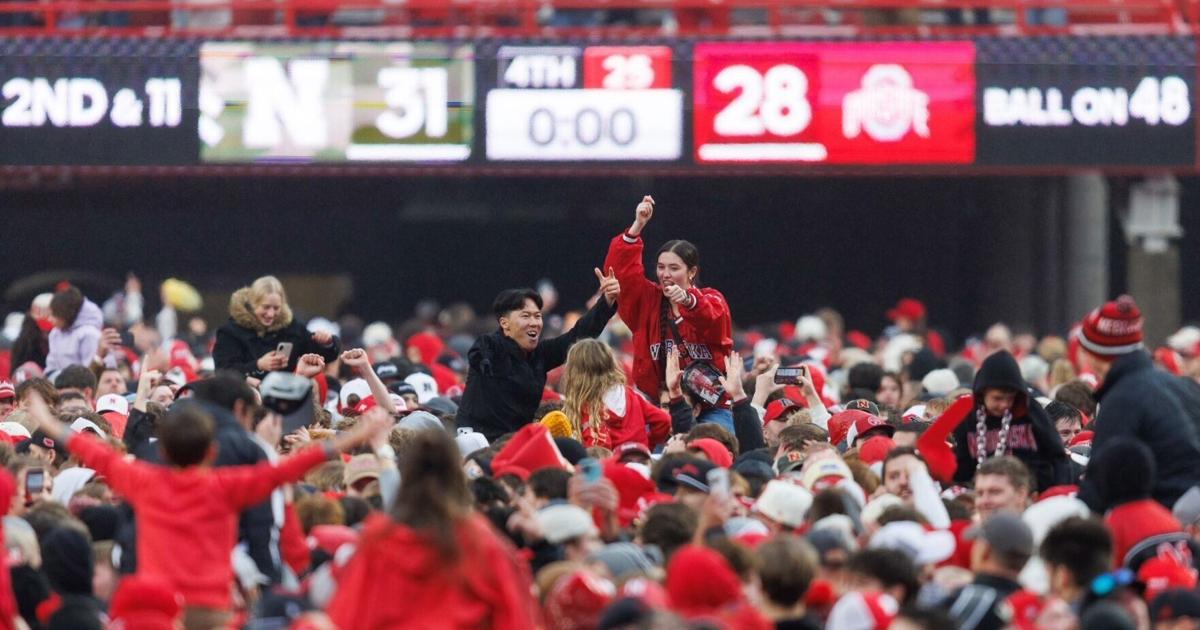
Nebraska Ends 31-Game Ranked Losing Streak, Eliminates Ohio State From CFP With 31-28 Win
Nebraska defeated No. 14 Ohio State 31-28 at Memorial Stadium on Saturday, ending a 31-game losing streak against...

Luther Burden III Outpaces Rome Odunze, Making Bears’ Top-10 Pick Increasingly Expendable
Luther Burden III is making a Bears veteran increasingly expendable as his explosive production outpaces Rome Odunze in...
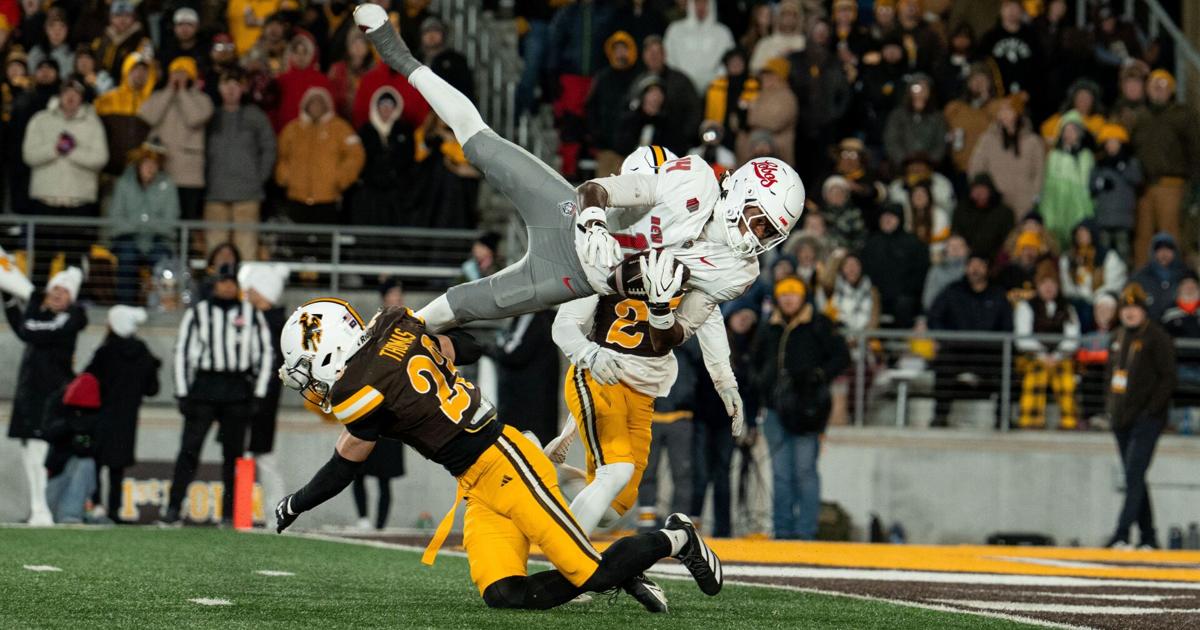
Wyoming Cowboys Fall 24-17 to New Mexico, Damaging Mountain West Championship Path
Friday night football brought heartbreak to Laramie as the Wyoming Cowboys fell 24-17 to New Mexico at War...