On November 20, Genki Forest held its 2026 National Distributor Conference in Zhuhai, Guangdong, where Tang Binsen, Zhang Renkun, and Fan Jun disclosed operating data detailing how the firm’s Alien Electrolyte Water and Haozizai wellness water achieved double-digit year-on-year growth.
Against an overall beverage industry divergence in 2026, these figures stand out. Based on tracking data from Mashangying across representative retail locations nationwide, the second quarter saw declines ranging from 8% to 15% across standard segments including packaged water, energy drinks, sports drinks, carbonated drinks, sweetened ready-to-drink tea, and ready-to-drink juice, leaving sugar-free ready-to-drink tea as the only sector maintaining a positive market-wide expansion of 16.1%.
Electrolyte water grew 88.8% year-on-year in the first quarter of 2026, expanding from 2.7 billion yuan in 2022 to nearly 20 billion yuan in 2025, with expectations to exceed 33 billion yuan this year. Meanwhile, Chinese-style wellness water grew its market 35-fold in three years.
In the first half of 2026, electrolyte water gathered at least 28 brands and hundreds of SKUs, while 23 brands and 59 new products poured into wellness water in 2025 alone, according to Mashangying and Qianzhan Industry Research Institute data.
The Bottom Line:
- Alien Electrolyte Water defended its leading position, capturing a 46.54% sales share in the first half of 2025 according to Mashangying monitoring.
- Cumulative investment in self-built factories reached nearly 8 billion yuan across 7 facilities by May 2026 to shorten distribution radius.
- Partner outlets exceeded 1.28 million by the end of 2025 following a net increase of 120,000 locations for the year.
Market Battlegrounds and Pricing Strategy
Nongfu Spring bypassed “Scream” to push electrolyte water under its main brand, while Mengniu, Coca-Cola’s Powerade, Master Kong, Jinmailang, Mizone, and C’estbon entered the category. Products split into zero-sugar versions, sports versions, and functional waters as 1-yuan trade-ins and scan-code red packets became industry-wide standards.
Genki Forest avoided dragging its flagship items into the price war by utilizing tiered operations, maintaining price and mindshare on core products while everyday scenarios captured new customers.
Sales tracking figures compiled by Mashangying indicate that during the opening six months of 2025, Alien secured the top position in this segment with a 46.54% share of sales, with Buhuila following at 32.66% and Pocari Sweat holding 9.06%.
In 2026, despite 28 brands and hundreds of SKUs competing on the same field, Alien achieved double-digit growth. Wellness water shifted from concept germination to quality competition as Nongfu Spring, Master Kong, Uni-President, and retailer private labels like Freshippo entered the space.
Data from Qianzhan Industry Research Institute showed the share of brands disclosing raw material origin information rose from 47% to 55% between 2023 and 2025, while in-house production shares climbed from 21% to 34%. In the second quarter of 2026, offline sales of Chinese-style wellness water fell 20.1% year-on-year, and new products dropped to 49 from 134 a year earlier as small brands exited.
Haozizai secured growth by co-building nearly 10,000 mu of red bean planting bases in Heilongjiang with Shiyue Daotian in 2025, sourcing coix seed from Guizhou, red dates from Xinjiang, and goji berries from Ningxia.
| Metric Category | Reported Figure | Context & Timeline |
|---|---|---|
| Electrolyte Water Growth | 88.8% | Year-on-year growth in Q1 2026 |
| Market Expansion | 2.7B to 33B yuan | Growth from 2022 to 2026 forecast |
| Alien Sales Share | 46.54% | First half of 2025 market share |
| Haozizai Market Share | 50.8% | Recorded share base in 2025 |
Supply Chain and Distributor Alignment
Tang Binsen described this year’s operational shift as cutting SKUs to achieve growth, noting that Genki Forest maintained the fewest items on sale and best inventory situation in recent years. For 2027, Zhang Renkun outlined plans to upgrade sparkling water refreshing sensations, extend Alien Electrolyte Water into professional sports nutrition scenarios, deepen co-built production regions for Haozizai, and expand Full-Score Vitamin C water.
Supporting this distribution network, cumulative investment in self-built factories reached nearly 8 billion yuan across 7 facilities by May 2026. The seventh factory in Xuchang, Henan, covers 223 mu with a total investment exceeding 1 billion yuan, housing eight aseptic production lines designed for an annual capacity of 1.2 billion bottles and shortening the regional response radius to under 300 kilometers.
Delivery times from production to consumer hands dropped from an industry average of seven days during the contract-manufacturing era to within two days following nationwide capacity rollout.
In March 2026, Genki Forest unveiled a 200 million yuan one-stop R&D and innovation testing base in Xianning, Hubei, to handle taste testing, process validation, and small-batch trial production. Partner outlets surpassed 1.28 million by the end of 2025, covering an additional 64 cities.
“Ten years ago, Genki Forest won on a single product; ten years later, what it must win with is a system that can continuously launch good products and serve the market well,” Tang Binsen said.
Disclaimer: The information provided in this article is for educational and market analysis purposes only and does not constitute financial, investment, or legal advice. Always consult with a certified financial professional before making investment decisions.
Worth a look

House Democrats Nominate Bowman as Next Speaker, Denying Fahey Second Term
“First, I want to thank Speaker Fahey for her service to the state. She is a talented legislator...
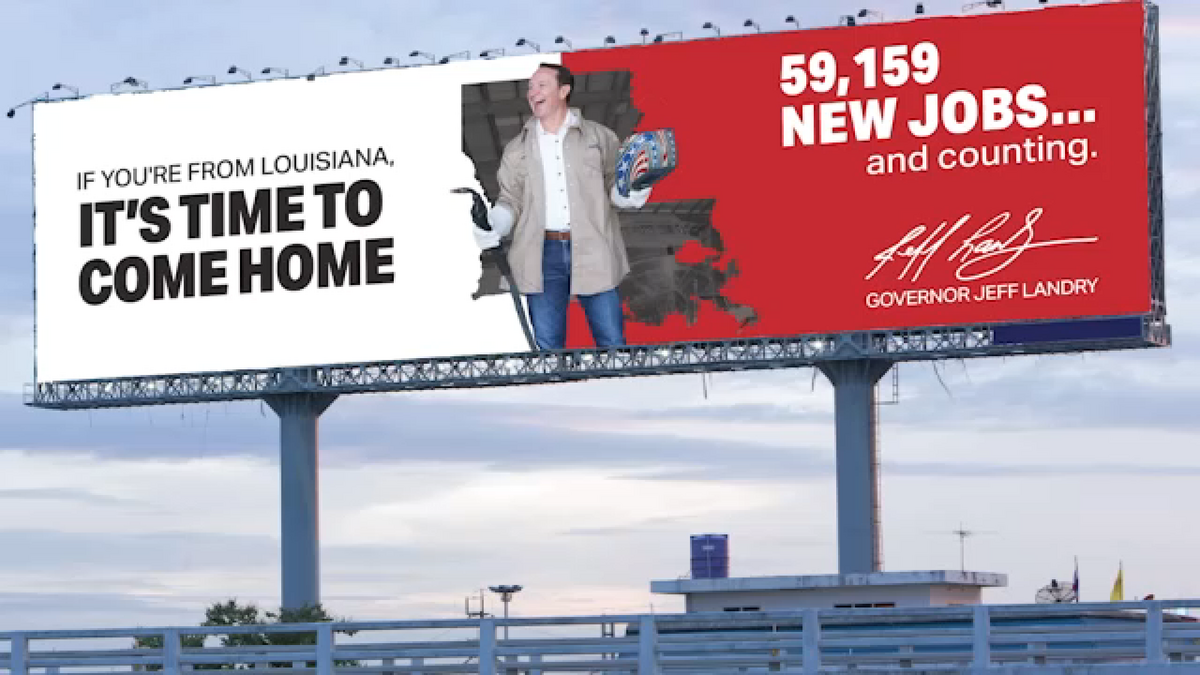
Louisiana Economic Development Agency Launches Billboards Near Houston
Louisiana state leaders are launching a new billboard campaign along I-10 in the Houston area to convince former...

Delaware Edges CSUN 97-92 in Overtime Thriller
The CSUN men’s basketball team fell 97-92 to Delaware in an overtime thriller on Friday afternoon at the...

New Mexico Fugitive Arrested on Interstate 84 in Idaho for Child Sexual Assault
Timothy James Valenzuela, 37, was arrested on Interstate 84 on Friday after traveling across multiple state lines. The...