
Idaho business owners hunting for debt settlement help in 2026 face a market with no official rankings and a thicket of new licensing rules.
The situation changed in August 2025 when the Idaho Supreme Court ruled that tax debt settlement firms must hold a license under the state's Collection Agency Act. Lawyers are exempt only if the debt relief work is incidental to their law practice, and attorneys who run a separate settlement business cannot claim that exemption, according to the court.
Idaho fee caps limit charges to 20 percent of principal
Before signing with any firm, the Idaho Department of Finance can confirm whether a company holds the required license. Under Idaho law, firms that do not hold a client’s money may charge no more than 20 percent of the principal of the unsecured debt at signing.
The Federal Trade Commission’s Telemarketing Sales Rule also bars upfront fees for debt relief before a debt is settled and paid, though the rule exempts calls initiated to a business.
Evaluating a specific firm
MCA Resolve of Delray Beach, Florida, illustrates the due diligence the outlets recommend. As of September 2, 2026, the Better Business Bureau gave the company a B grade with 23 complaints over three years; it is not accredited. Trustpilot showed a 2.7 rating from 86 reviews.
Court records list MCA Resolve as a defendant in several funder lawsuits, including Newco Capital Group VI v. MCA Resolve filed in New York. Those are allegations, not findings, and the firm focuses on merchant cash advance debt.
The sources warn to be suspicious of any debt relief agency that promises guaranteed savings in a set percentage at the start of your first call and never to sign a deal after a single call.
Forgiven debt over $600 triggers taxable income reporting
Any forgiven debt of $600 or more typically triggers a Form 1099-C, counting the canceled amount as taxable income. Insolvent or bankrupt taxpayers may exclude it by filing Form 982, which generally reduces losses, credits, or asset basis. In Idaho, written contracts give a funder five years to sue. Subchapter V bankruptcy remains an option for debts up to $3,424,000.

Staying open versus shutting down
The threshold question is whether the owner wants to stay in business or shut down. Settlement damages business credit, which can scare off future suppliers. Companies that intend to keep operating must prioritize relationships with secured creditors who hold liens on inventory, equipment, or real estate — losing those assets often means failure.
Many small-business loans from major banks such as Chase, Wells Fargo, American Express, and Capital One carry personal guarantees, exposing the owner’s personal assets if the firm defaults.
Settling too soon can backfire. Creditors resist negotiating when it appears the business could pay but simply wants a discount, and the credit damage makes future borrowing harder and more expensive. The chances of achieving pennies-on-the-dollar settlements have fallen since the Great Recession as creditors grew more sophisticated.
Verifying the exact legal name and address of any firm is essential; similar-sounding names such as MCA Resolve and Coastal Debt Resolve are different businesses.

Proper Hospitality to Convert Historic Yamasaki Tower into Minneapolis Proper Hotel
"This is one of the most iconic buildings in the entire Midwest. It's irreplaceable," said Chad Tepley, founder...

Bruins Host Kings Tuesday Night; Kuraly and Lohrei Return to Lineup
The Boston Bruins host the Los Angeles Kings on Tuesday night at 7 p.m., closing a four-game homestand...
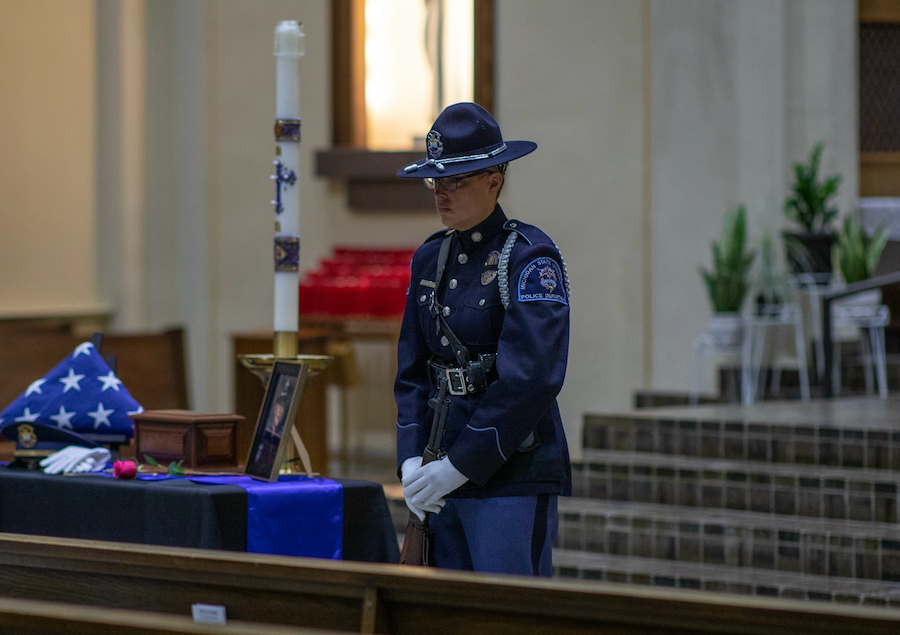
Episcopal Priest and MSU Officer Marks 28 Years on Force, East Lansing Info Reports
Melissa Congleton marked her 28th year as a police officer with the Michigan State University Department of Public...

Ravens Lose 23-20 to Winless Chargers; Hamilton Calls It Disgrace to Standards
Baltimore expected a lifeline against the NFL's only winless team; instead the Ravens absorbed a 23-20 loss on...