
A Jefferson City Retiree’s Path to a $2 Million Nest Egg
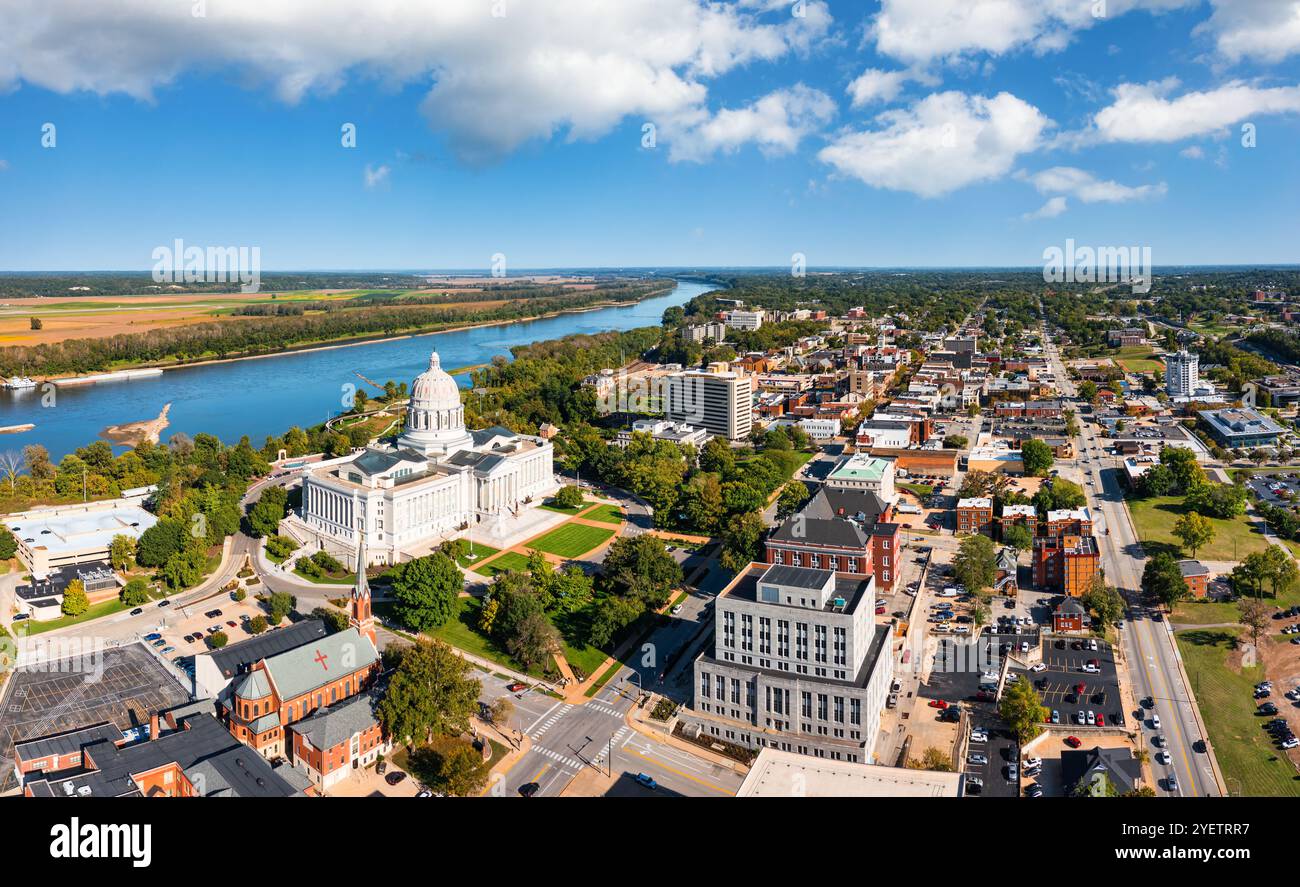
In a recent profile for Kiplinger, a 62-year-old state government retiree from Jefferson City, Missouri, shared his journey to accumulating a net worth exceeding $2 million. The retiree, who spent his career as a program manager earning between $60,000 and $70,000 annually, attributes his financial standing to a decades-long commitment to disciplined, low-cost investing rather than high-income windfalls.
The retiree’s strategy centered on maximizing annual contributions to his individual retirement account (IRA) and his state-sponsored deferred-compensation plan. By consistently funneling these savings into low-cost equity mutual funds over a period spanning more than 30 years, he achieved an average annual return of approximately 9.5%. He reached the $1 million milestone roughly a decade ago and has since doubled that figure.
The Role of Tax-Advantaged Accounts and Early Choices
Reflecting on his financial trajectory, the retiree identified a specific regret regarding his early tax planning. He focused his initial contributions on traditional IRAs to secure immediate tax refunds, a strategy that now presents a challenge as he approaches the age for Required Minimum Distributions (RMDs). He noted that he did not have access to Roth options when he first began his career, and he currently plans to execute annual Roth conversions to mitigate future tax liabilities.
The importance of tax-sheltered growth is backed by long-standing federal guidelines. According to the Internal Revenue Service, the structural differences between traditional and Roth accounts significantly impact long-term withdrawal strategies, particularly for those in higher tax brackets during retirement. The retiree’s experience highlights the tension many middle-income earners face when balancing current tax relief against the eventual tax burden of deferred growth.
Maintaining a Consistent Investment Philosophy
Despite his current wealth, the retiree reports that his lifestyle and investment approach have remained largely unchanged. He continues to hold his assets in equity index funds and intends to keep them there, expecting them to grow over time. While he has recently increased his charitable giving and funded a few vacations, he maintains that he has always been comfortable living below his means, prioritizing financial security and the freedom to manage his time as he chooses.
The retiree’s success underscores a recurring theme in personal finance: the impact of compounding returns on modest, consistent contributions. His father provided the initial guidance on the mechanics of mutual funds and the necessity of long-term holding, a foundation the retiree credits as the primary driver of his success. He did not utilize a professional financial advisor throughout his career, nor did he rely on investment literature.
Looking Toward Future Financial Management
As he enters retirement, the former program manager remains focused on the mechanics of his portfolio. He noted that while he can no longer contribute to traditional IRAs, the continued performance of his equity index funds is expected to drive further growth. He intends to manage his estate through a will and views his financial independence as a source of peace of mind.
The retiree’s story serves as a case study in the effectiveness of the Securities and Exchange Commission’s long-term investing principles, which emphasize that individual investors often benefit from the simplicity of broad-market funds. By avoiding the temptation to chase volatile trends or overcomplicate his strategy, he managed to build a multi-million-dollar portfolio on a salary that rarely exceeded $70,000. He remains anonymous, sharing his experience to demonstrate that high earnings are not a prerequisite for achieving significant retirement savings.
Keep reading
North Charleston woman Nakyah Denae Odom charged after Dollar General incident
North Charleston Police Charge Woman Following Dollar General Armed Confrontation Nakyah Denae Odom, a 22-year-old resident of North...
Massillon Crushes Columbus DeSales 48-0 in Playoff Opener
Massillon Tigers Dominate Columbus DeSales in Playoff Opener The Massillon Tigers signaled their postseason intentions with a decisive...

Harwood, North Dakota voters reject data center restriction proposal
Harwood, North Dakota, has found itself in a position that is increasingly rare in the American landscape. While...

South Carolina Tourism Campaign Drives 84 Percent Website Traffic Increase
South Carolina’s $1.5 Million Bet on New York City When South Carolina officials decided to transform Grand Central...