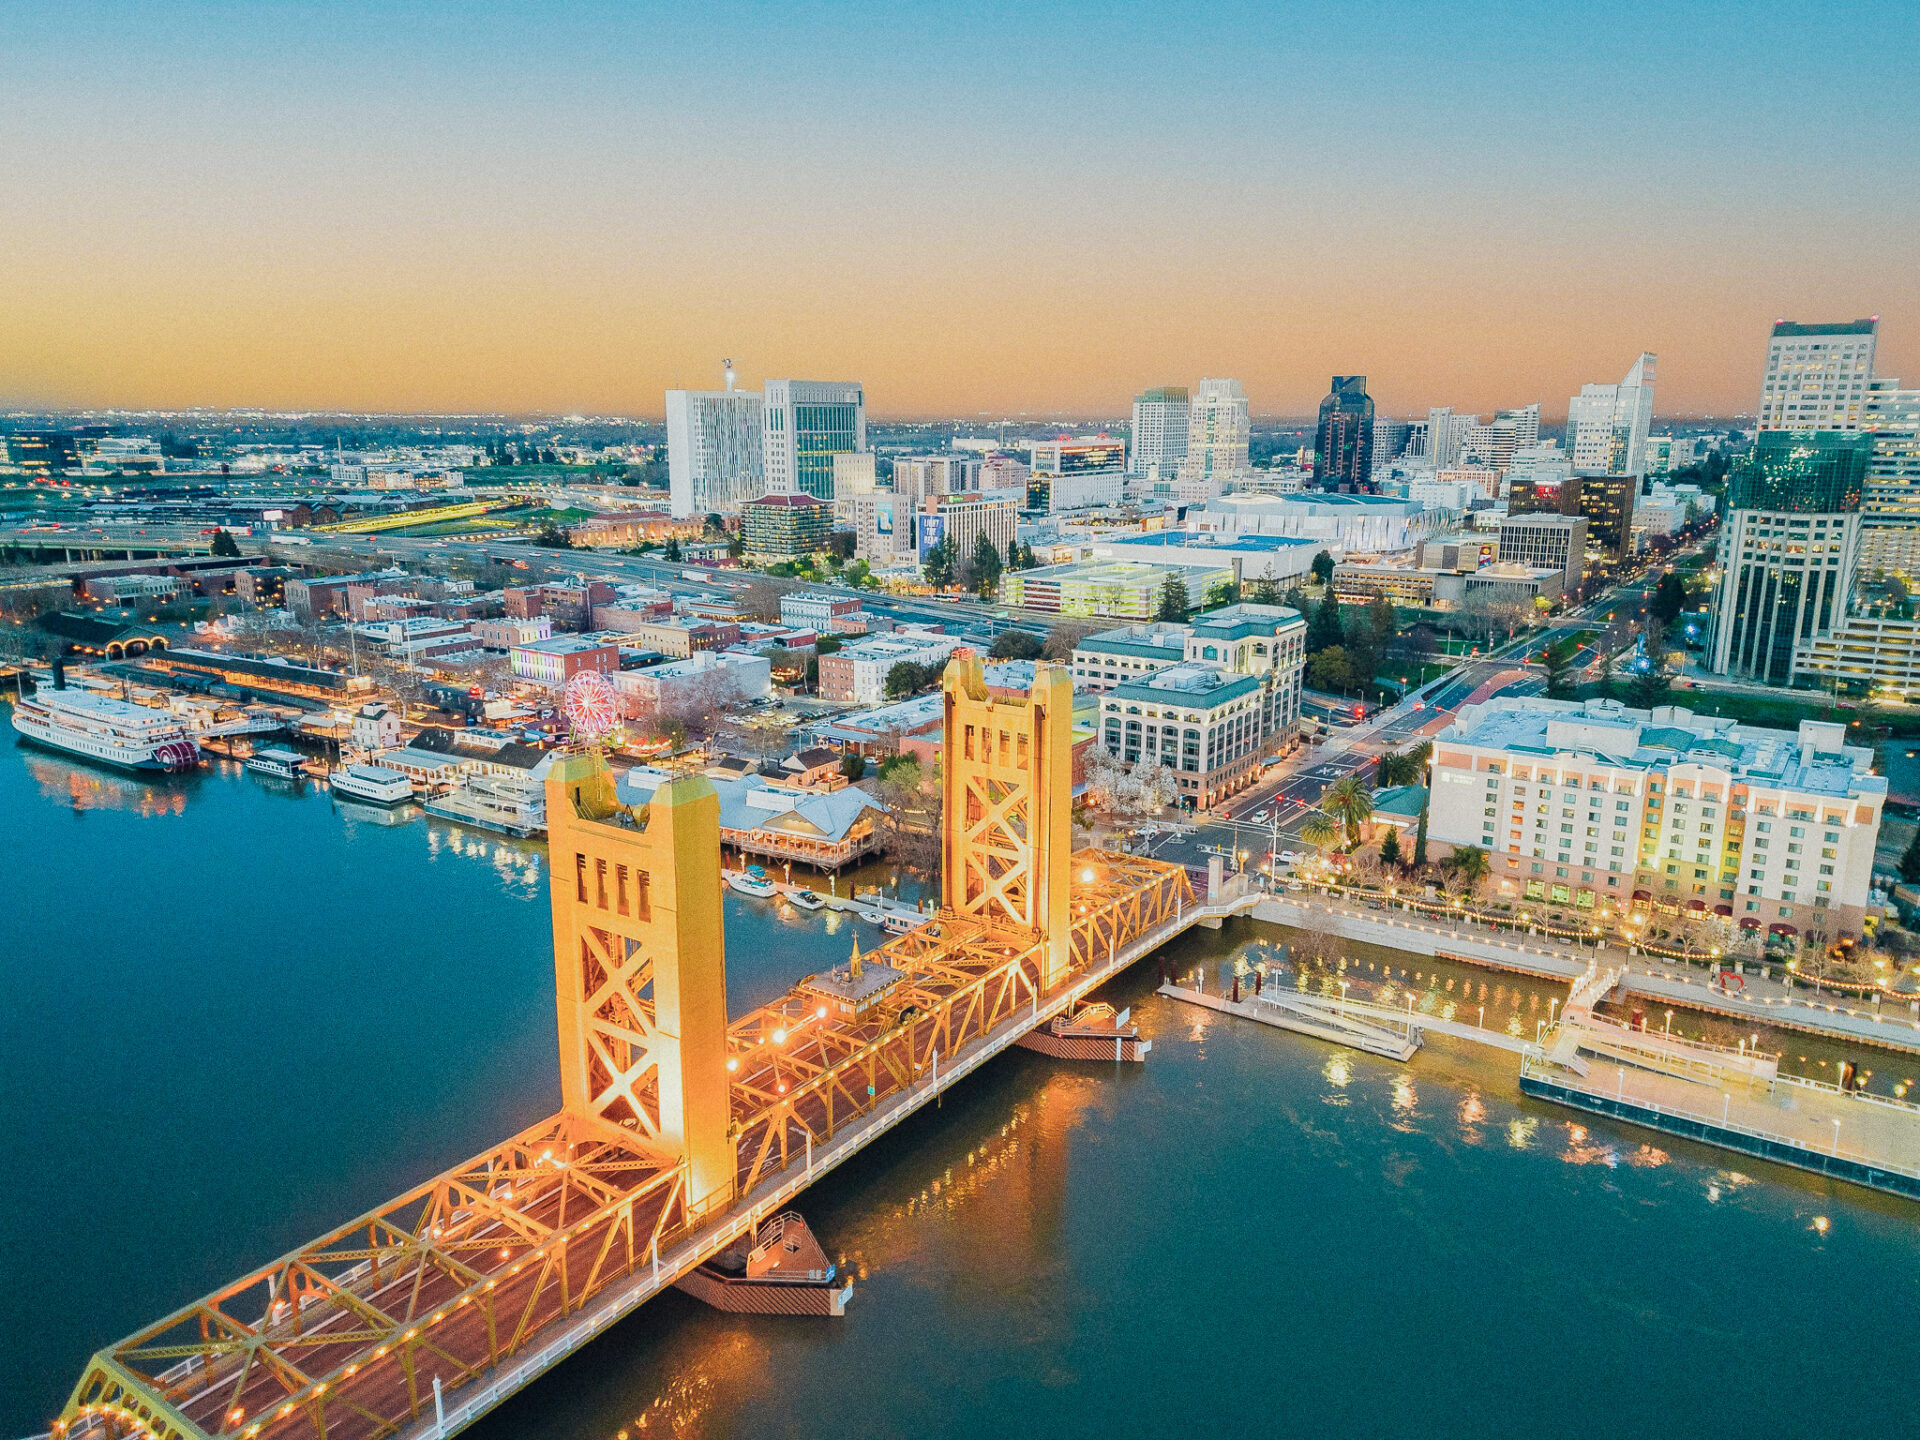
The Sacramento multifamily market is experiencing a notable tightening as construction pipelines shrink and rental demand stabilizes.
A Matthews™™ Research report shows regional sales volume jumped 52% to $1.5 billion over the trailing 12 months, pointing to renewed activity even as developers pull back on new projects. This shift arrives as the region grapples with a delivery slowdown that has left the construction pipeline at just 0.9% of total inventory.
For property owners and investors, the current climate is defined by record-high rents and a vacancy rate that has tightened to 4.4%, a 25-basis-point drop compared to the same period last year. Although the broader market shows signs of resilience, new unit deliveries have dropped sharply. Matthews™ reported that trailing-12-month completions hit 987 units, a 61% decrease from the prior period, marking a sharp departure from the 2024 peak of 3,354 units.
The average rent in the region has reached a record $2,029, reflecting a 1.2% year-over-year increase. However, performance varies significantly by geography. Data from CBRE highlights that while the Folsom/Orangevale/Fair Oaks submarket leads with 5.2% rent growth, other areas face different pressures. For instance, the Natomas submarket has seen a 2.7% decline in rents, a trend occurring alongside the delivery of 303 new units.
| Metric | Matthews™ Reported Q3 2026 | CBRE Reported Q3 2026 |
|---|---|---|
| Average Rent | $2,029 | $2,039 |
| Vacancy Rate | 4.4% | 4.6% |
| Quarterly Deliveries | 290 units | 1,030 units |
Differences in delivery figures between reporting firms show how hard it is to track current inventory. CBRE said that 1,030 units were delivered in the third quarter alone, which lifted total inventory by 1.7% year over year. Despite these deliveries, year-to-date absorption of 3,186 units continues to outpace new supply, keeping upward pressure on rent levels in high-demand pockets.

Pricing remains a point of contention for those entering the market. While sales volume reached $1.5 billion, per-unit pricing sits at $210,000. This figure has declined for four consecutive years, remaining roughly 10% below the $235,000 peak recorded in the second quarter of 2022. The average cap rate has now risen for 19 straight quarters, reaching 5.76%.
This environment means owners have strong pricing power because supply is tight, but investors face a market where asset values are still recalibrating from post-pandemic highs. Transaction activity remains cautious; twelve trades totaled $160 million in the third quarter, about half the second quarter total.
Investors looking at the region often weigh the long-term viability of these assets against current interest rate environments and local economic shifts.
What is the current state of vacancy in Sacramento?
Vacancy remains tight at 4.4% according to Matthews™™, though CBRE data indicates a slight quarterly rise to 4.6% as new inventory enters the market.
How do current rent levels compare to historical highs?
Rents reached a record $2,029, marking the first annual gain in four quarters, according to CBRE, despite some submarkets experiencing localized stagnation.
Are developers continuing to build at the same pace as 2024?
No, the construction pipeline has slowed significantly. Annual completions fell to 987 units over the trailing 12 months, a 61% drop from the 3,354 units delivered during the 2024 peak.
As the market moves into the final quarter of the year, the tension between limited new supply and the absorption of existing units will likely dictate the next phase of rent growth. For now, the combination of a 0.9% construction pipeline and positive net absorption provides a buffer for current owners, even as the broader investment market remains sensitive to pricing corrections.
Related reading

Idaho Lawmakers Urged to Support 11,000 Kinship Caregivers as First State Blueprint Nears
Idaho Caregiver Alliance program manager urges lawmakers to support 11,000 kinship caregivers as first state blueprint nears completion....

Feds Seize Kalihi Spam Array Capable of 230,000 Texts Per Minute
Federal agents seized a Kalihi spam array capable of transmitting 230,000 texts per minute during a pre-dawn search...

Lalani Ventures Buys Office Portion of Historic Portman Tower at Peachtree Center
Lalani Ventures, the real estate firm currently steering the massive redevelopment of Underground Atlanta, has expanded its downtown...
Wilmington Honors Fallen Officer Thomas Zebley With Headstone 107 Years After Death
On the 107th anniversary of his death, the final resting place of Wilmington Patrolman Thomas Zebley was finally...