Rhode Island treats software as-a-service (SaaS) as taxable vendor-hosted prewritten computer software, applying a flat 7% state sales tax to the full charge. Because the state maintains no local sales tax jurisdictions, that 7% rate applies universally whether a business sells to a corporate enterprise or an individual consumer.
How Rhode Island Taxes Cloud Software and Digital Goods
The Ocean State has taxed vendor-hosted prewritten software since October 1, 2018, according to guidance from the Rhode Island Division of Taxation, including Advisory ADV 2018-38. Byteorca.com reported that this tax applies when customers access software through the internet or a vendor-hosted server, regardless of whether that access is temporary or permanent.
The state treats downloaded software as equally taxable. If a customer installs a local desktop application, an agent, or an offline client—even if the underlying product runs primarily online—the transaction triggers the 7% rate. Digital goods such as e-books, music, and video face the exact same tax treatment, alongside AI tools and API access.
Meanwhile, custom software built from scratch for a single client remains exempt from sales tax. Cloud infrastructure and platforms like IaaS and PaaS generally escape taxation unless the package includes prewritten software components.
Invoice Structuring and Professional Services
How a company writes its invoice dictates whether setup and implementation fees escape taxation. Galvix reported that setup, implementation, and training fees are fully taxable when they are required to complete the software sale. However, separately stated installation fees are exempt from the 7% tax.
To prevent overpayment or audit penalties, sellers must list installation services on their own dedicated invoice lines rather than bundling them into a single software price. Technical support contracts that cover only support services are also generally exempt, whereas general maintenance and support fees remain taxable.
Economic Nexus and Registration Rules
Sellers must collect and remit tax based on where the end user is located rather than the physical headquarters of the business or its servers. Rhode Island features an economic nexus threshold of $100,000 in gross sales or 200 separate transactions over the previous calendar year. Exempt sales count toward reaching this threshold.
Businesses that cross this threshold must register with the Rhode Island Division of Taxation through the Rhode Island Tax Portal or the Streamlined Sales Tax registration system. Sellers must file returns monthly, or quarterly if approved by the Division, with each return due by the 20th of the month following the reporting period.
| Product or Service | Rhode Island Tax Treatment |
|---|---|
| Vendor-hosted SaaS | Taxable at 7% |
| Downloaded Software | Taxable at 7% |
| Custom Software | Not Taxable |
| Digital Goods (E-books, Video) | Taxable at 7% |
| Separately Stated Installation | Not Taxable |
Failing to collect required taxes exposes a business to the state’s 10% late penalty and 18% annual interest rate. Companies can utilize a voluntary disclosure agreement to mitigate penalties if they come forward before an audit begins. Resellers, qualifying nonprofits, and government agencies can present exemption certificates at the time of sale to purchase software tax-free, which vendors must carefully retain for future audits.
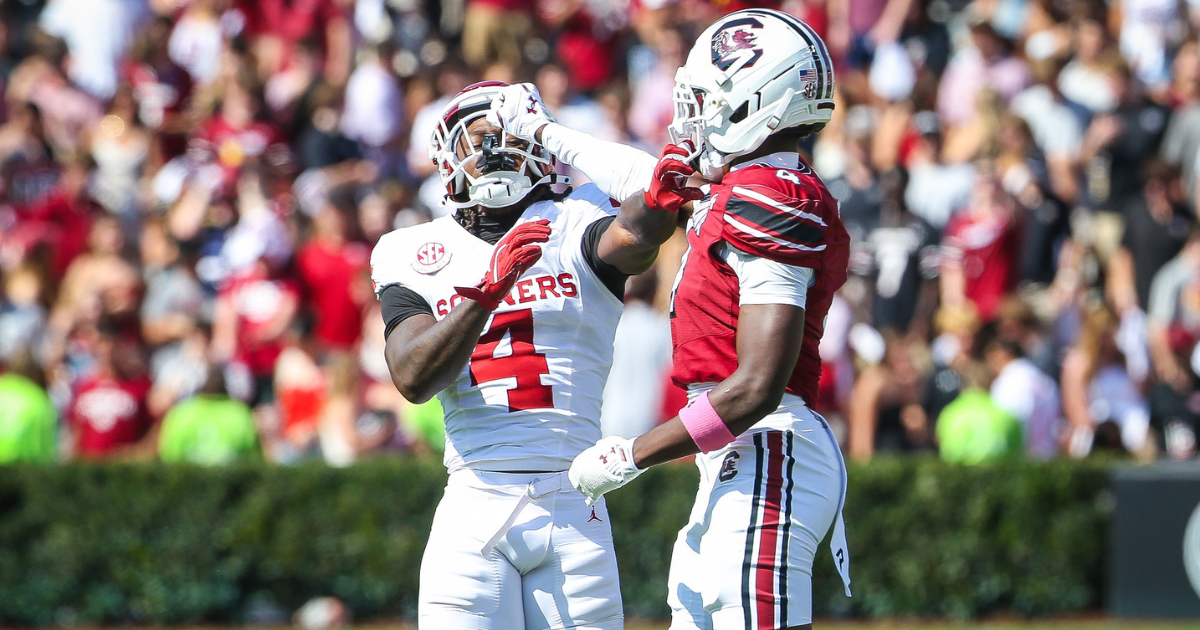
South Carolina Gamecocks Face Oklahoma Sooners in SEC Matchup
The Stakes in Norman: South Carolina Meets Oklahoma for a Halloween Showdown Saturday afternoon brings a high-stakes clash...

Stars Coach and Teammates Praise Jamie Benn for Resurgent Play
Jamie Benn is adding to his franchise record for games played at 1,265 while closing in on the...

UTEP Faces North Dakota State in Fargo Following Bye Week
UTEP is coming off its bye week sitting at 1-6 overall and winless in Mountain West play, staring...
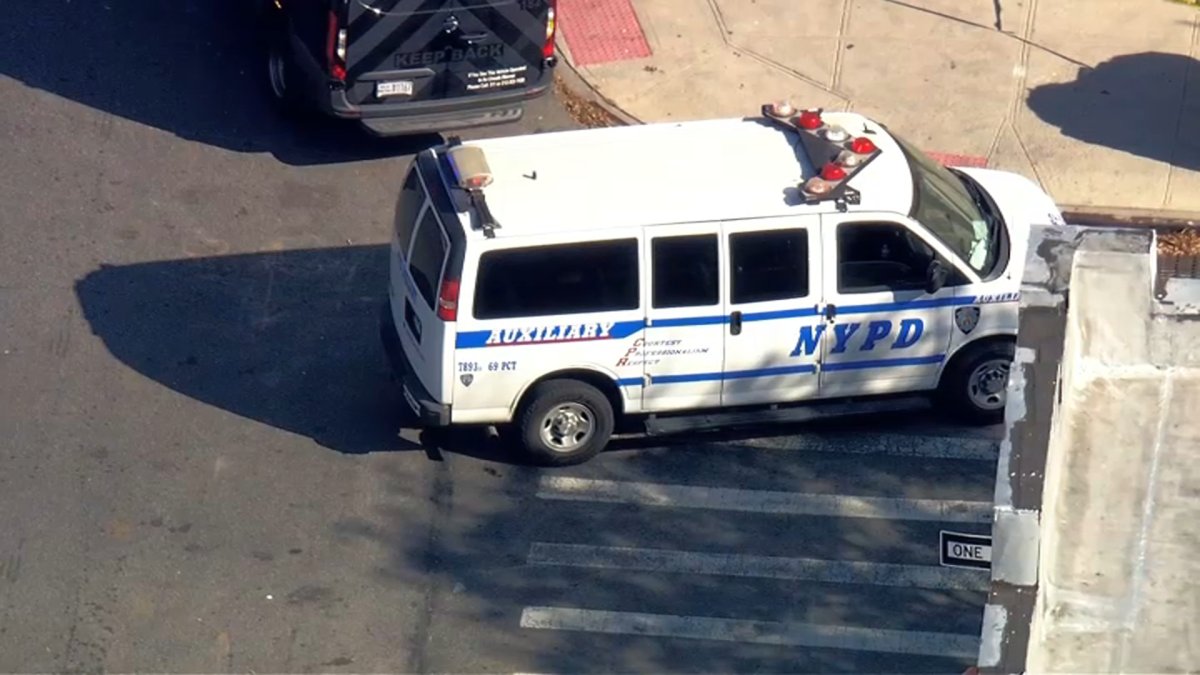
Body Found in Bag on Brooklyn Street After Surveillance Captures Dump
A routine morning in the Canarsie neighborhood of Brooklyn transformed into a homicide investigation on Friday, October 30,...