
Stock futures moved higher on Monday morning as traders assessed whether technology shares could sustain a recovery from a sharp sell-off last week.
S&P 500 futures gained 0.42% while Nasdaq 100 futures added 0.18%. Contracts tied to the Dow Jones Industrial Average climbed 375 points, or 0.73%, as markets braced for upcoming inflation readings and corporate earnings.
The Bottom Line:
- S&P 500 futures advanced 0.42% and Nasdaq 100 futures rose 0.18% in early Monday trading.
- Taiwanese equities led Asian markets higher, with the Taiwan Weighted Index surging 4.94% to close at 41,664.7.
- Following news of a board investigation, a Hyperliquid proxy for Nvidia stock dropped 2% during the previous 24-hour period.
China’s October inflation figures are also being evaluated by Asian investors, with the producer price index reaching a peak of 5.7%—its highest level in more than four years—while consumer inflation arrived at 0.7%, missing anticipated levels.
Renewed buying interest helped chip stocks recover on Friday, allowing the market to partially bounce back from Thursday’s severe AI-focused decline. The Nasdaq Composite, heavily weighted toward tech, gained 1.09% to finish at 24,579.42, while the S&P 500 broad-market index climbed 0.31% to 7,376.86. Conversely, the blue-chip Dow index fell 0.46%, or 237.33 points, closing at 51,285.73.
Broader investor sentiment remained cautious following a batch of stronger-than-expected jobs data. Anxiety persists regarding the impact of the Democrats’ significant midterm election gains, with growing fears that more stringent rules concerning data center energy consumption, development expenses, and construction could hamper the expansion of AI infrastructure.
The tech sector will also be focused on the bombshell announcement Sunday that Nvidia’s board of directors is opening an investigation into co-founder and CEO Jensen Huang’s relationship with a businesswoman who U.S. intelligence agencies say is a Chinese spy. On Hyperliquid, a proxy for Nvidia stock saw a 2% decline over the trailing 24 hours.
Liz Ann Sonders, chief investment strategist at the Schwab Center for Financial Research, highlighted that the Nasdaq and Nasdaq-100 are currently oversold as traders engage in significant de-risking. Thursday marked the biggest day of retail selling since the Covid pandemic, according to Vanda Research.
Retail traders haven’t been taking advantage of the selloff, Sonders said. “Retail has not proven to be the dip buyers that they have been in the past,” she told CNBC’s “Fast Money” on Friday. “You saw a really heavy amount of net selling … we may not fully be washed out yet, but we’ll have to see whether that retail trader at some point decides to step back in.”
Sonders indicated that attention should shift in the near term toward how firms adjust their capital expenditure strategies and what they anticipate for profit margins moving forward.
As investors evaluate the tech outlook and the possibility of further declines, they are turning their attention to upcoming AI-focused earnings reports from CoreWeave, Cisco, and Applied Materials. Additionally, they will monitor the consumer price index on Tuesday and the producer price index on Friday for insight into the Federal Reserve’s potential next steps.
On Monday, traders will get September wholesale inventories data at 10 a.m. ET. Take-Two Interactive Software, Occidental Petroleum, KKR, Constellation Energy and Skydance are scheduled to report quarterly earnings.
Disclaimer: The information provided in this article is for educational and market analysis purposes only and does not constitute financial, investment, or legal advice. Always consult with a certified financial professional before making investment decisions.
Worth a look

Nevada Women’s Basketball Falls 70-60 to Sacramento State in Home Opener
The Nevada women’s basketball team saw their home opener at the Lawlor Events Center slip away on Saturday,...

Florida Soccer Ends Season With Loss to Arkansas in SEC Tournament Opener
The Florida Gators’ 2026 soccer season came to a silent, abrupt end Sunday night at the Ashton Brosnaham...
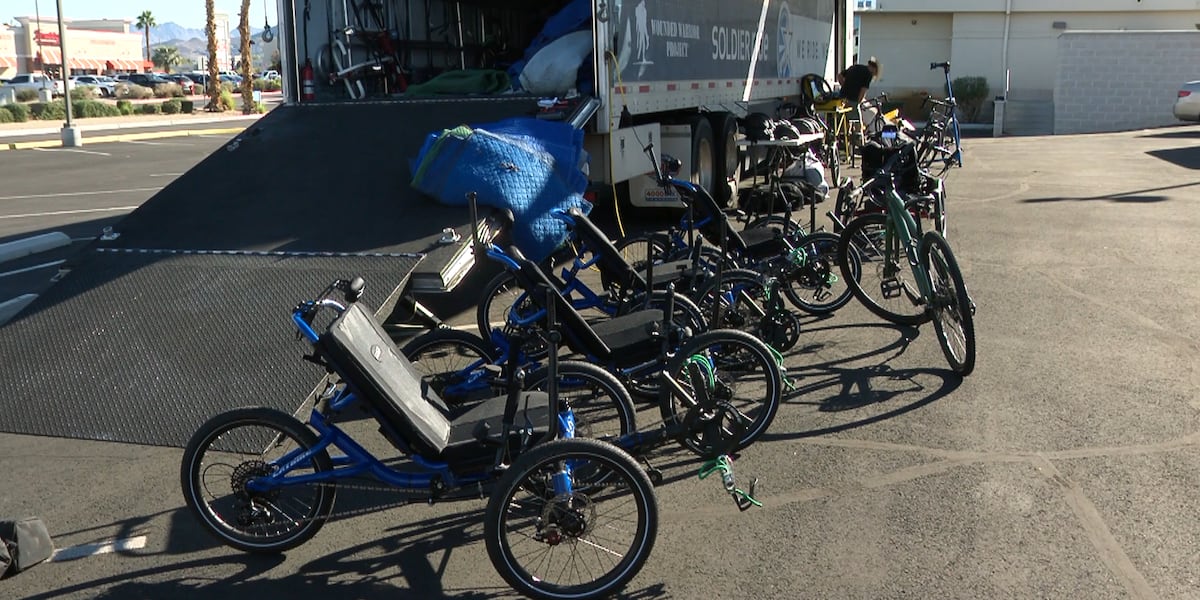
Wounded Warrior Project, NFL Team up for Soldier Ride From Las Vegas to Phoenix
Dozens of veterans are currently cycling from Allegiant Stadium in Las Vegas to Phoenix, a collaborative effort between...
Parangal Dance Company Visit Aims to Revive Filipino Culture in Juneau
“Bringing culture bearers to our community is really important. We can have the opportunity to learn and also...