
Apollo Global Management walked away from a $2 billion loan to City Football Group in the days after an independent commission found Manchester City guilty of 114 breaches of Premier League financial rules, the Financial Times reported on Wednesday.
The collapse of the financing, which had been in its final stages, is the first concrete commercial casualty of the September ruling. That judgment concluded City had artificially inflated its financial position by more than £900 million over nine years through what the commission described as “sham” commercial deals orchestrated by an Abu Dhabi investment vehicle ultimately controlled by Sheikh Mansour bin Zayed Al Nahyan, the club’s owner since 2008.
Apollo, which manages more than $1 trillion in assets, had been negotiating the loan to refinance existing credit facilities and fund infrastructure projects across CFG’s network of 12 clubs, which includes New York City FC, Girona and Troyes.
People familiar with the discussions told the Financial Times the US private capital group decided not to proceed once the commission’s findings became public. Apollo and CFG both declined to comment when approached by the FT and The Athletic.
The ruling has left the ownership group in a state of profound uncertainty.
Sanctions — ranging from a fine and points deduction to expulsion from the Premier League — have yet to be determined. The appeal is set to be heard next month, according to people with knowledge of the matter cited by the FT, with any punishment likely to be handed down next year if the appeal fails.
“The collapse of the Apollo talks underlines the uncertainty surrounding Manchester City’s financial future pending the outcome of its appeal and the scale of any sanctions imposed against it if the commission’s ruling is upheld.”
the Financial Times reported, citing sources briefed on the negotiations.
The episode also illustrates how tightly CFG’s financial architecture is bound to Abu Dhabi’s sovereign wealth ecosystem. Last month Apollo agreed to take a minority equity stake in Mubadala Capital, the asset management arm of the Abu Dhabi sovereign wealth fund. That entity is chaired by Sheikh Mansour; its chief executive, Khaldoon Al Mubarak, chairs both Manchester City and CFG. In the month after the commission published its findings, Companies House filings show Sheikh Mansour injected £100 million of equity into CFG via his Newton Investment and Development vehicle — a signal, perhaps, that the group is relying on internal capital while external markets digest the ruling.
Private equity is not new to CFG. Silver Lake bought a minority stake in 2019 in a deal that valued the group at $4.8 billion, according to the FT.
Apollo itself has been accelerating its push into sport: it agreed last year to buy a majority stake in Atlético Madrid at a valuation above €2 billion, lent £80 million to Nottingham Forest in December 2024, and in August extended $2.6 billion of financing to the holding company of the New York Yankees.
City continue to deny wrongdoing.
The club said it would appeal “on the basis that the opinion contains clear material errors, of law, principle and fact, and is unsafe,” according to the FT.
Premier League clubs voted Thursday to indemnify the league’s board, including chief executive Richard Masters, against personal legal action from any of City’s sponsors — a procedural move that shows how far the fallout has spread beyond the pitch.
The appeal hearing begins next month.
City Football Group was founded in 2013 as a holding company to oversee Manchester City and the newly created New York City FC, realising a global football vision first developed by Ferran Soriano during his time at Barcelona. It is now the largest multi-club ownership group in the world by number of clubs, with stakes in teams across the United States, Australia, Spain, Brazil, Uruguay, China, Belgium, France, Italy and Turkey.
Leon County Offices, Libraries Closed Three Days for Thanksgiving, Family Day; Tallahassee Shuts Two Days
Leon County offices, libraries and community centers will stay dark for three straight days starting Wednesday, a longer...

Democratic AG Leader Sean Rankin Steps Down After 2026 Election Wins
The head of the Democratic Attorneys General Association is stepping down after a 2026 election cycle that saw...

Carson Council Approves First Reading of Drive-Thru Ban Near Existing Sites
Carson will likely ban new restaurant drive-thrus from opening within 500 feet of existing ones after the City...
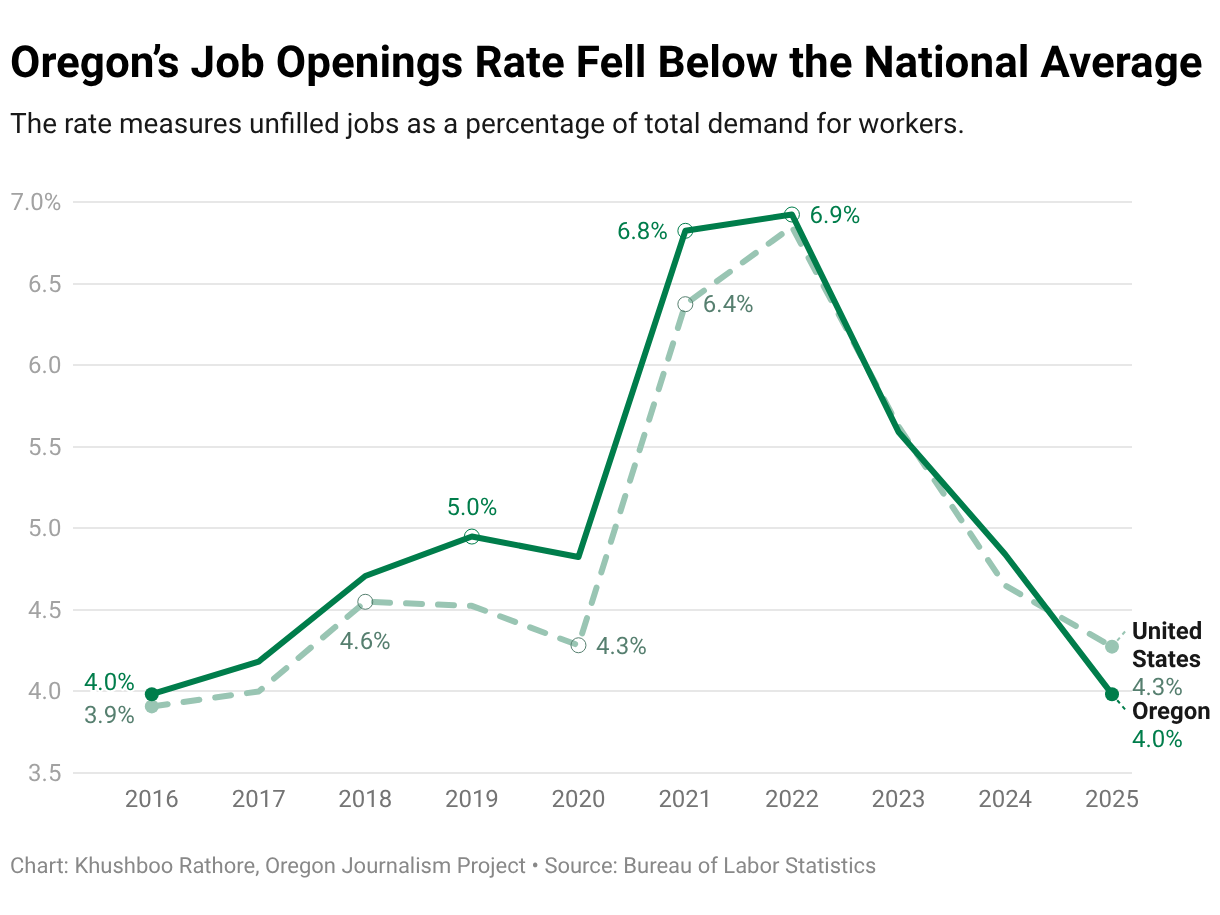
Oregon Job Openings Trail Nation by 75,000 in 2025, Unemployment High in 2026
New federal data shows Oregon's economy stalled in 2025, with job openings falling below the national average for...