
Bank of England Ends Three-Year Pause, Hikes Rate to 4%
The Bank of England raised its main interest rate by 25 basis points to 4% on Thursday, ending a run of more than three years without an increase. The decision, driven by accelerating inflation fueled by the ongoing Iran war, marks the last major central bank to begin a tightening cycle since the conflict began. Andrew Bailey, the Governor of the Bank of England, stated that the current level of inflationary pressure in the pipeline, stemming from increased energy prices, justifies a rise in the Bank rate.
The Bottom Line:
Faced with the Bank staff's new forecasts, it was surely inevitable that the MPC would vote unanimously to raise rates today… 🤔 In particular, CPI inflation is "now expected to rise to around 5% by the middle of next year". This may be too pessimistic, depending on what…
- The Bank of England’s key rate now sits at 4%, its first increase in over three years, with an 8 to 1 majority vote in favor of the quarter-point increase.
- Inflation is projected to rise to around 5% by the middle of next year, a consequence of the Iran war’s impact on global energy prices.
- For the 13% of UK mortgage borrowers on variable rates, the hike will increase monthly payments, while new fixed-rate buyers face costs at a three-year high.
The Hidden Cost of Geopolitical Tension
This is not an ordinary rate hike. It’s a direct response to an external shock. The Bank of England explicitly cited the conflict in the Middle East as a driver, noting that global energy prices have continued to rise from an already elevated level. The UK economy, being particularly vulnerable to external energy shocks, has seen its CPI inflation climb to 3.5% in September. The bank now expects this figure to rise to around 5% by the middle of next year before a gradual decline as restrictive monetary policy bears down on inflation.
The timing is critical. The bank’s move comes as energy prices have shown a sharp decline following the U.S. midterm elections. Governor Bailey acknowledged this encouraging news but stressed it is too early to declare victory. The entire path for UK interest rates, and likely those of other central banks, is now hanging in the balance, with U.S.-Iran hostilities holding the key, according to Suren Thiru, ICAEW’s chief economist.
As widely expected, the Bank of England hiked interest rates by 25 bps. The vote was 8-1, with one dissenter pushing for 50 bps. The policy move comes alongside a warning that inflation could peak at 4.9% next year.#economy #markets #boe @bankofengland #centralbanks
Alpha Metric: The 5% Inflation Threshold
The single most important number in this story is the Bank of England’s projection that inflation will near 5%. This figure is the canary in the coal mine. It's not just a statistic; it's the trigger that forced the bank's hand and defines the risk environment for the coming year. The dissenting vote from Monetary Policy Committee member Catherine L Mann, who advocated for a larger 50-basis-point hike to 4.25%, highlights the severity of this risk. She voted for greater tightening to lean against non-linear inflation risks and uphold the bank’s credibility.
Reading the raw transcript from the Monetary Policy Committee’s statement, the rationale is stark. The committee is explicitly attempting to prevent a one-off energy shock from becoming embedded in the broader economy. They are watching for second-round effects and an acceleration in goods and services inflation. If these signs solidify, the bank will be forced to act more aggressively, potentially derailing the modest UK economic growth seen recently.
NEW Bank of England RAISES rates to 4% for first time in 3 years 8-1 vote (with 1 vote for 0.5% rise) Q3 GDP growth now forecast at 0.7% Inflation set for 4.9% in spring
The Main Street Bridge: Mortgages and Savings
While the Bank of England governs the UK, its policy shift reflects global pressures that directly influence everything from corporate borrowing costs to the price of goods. For the 87% of UK homeowners on fixed-rate mortgages, the immediate impact is minimal. Their monthly payments will remain unchanged until their current deal expires. However, for those on standard variable rates (SVRs), the pain is real. A standard SVR borrower will face an additional £14.28 each month, provided the increase is fully passed on.
The bigger story is the new reality for homebuyers and those remortgaging. The financial data provider Moneyfacts reports the average new mortgage rate has risen to a three-year high of 5.89%. For a borrower coming off a 2021 fixed deal at 2.59% and refinancing to a new five-year fix at 5.99%, the increase is significant. On a £175,000 mortgage with 25 years remaining, that translates to an extra £334 per month, or £4,000 a year.
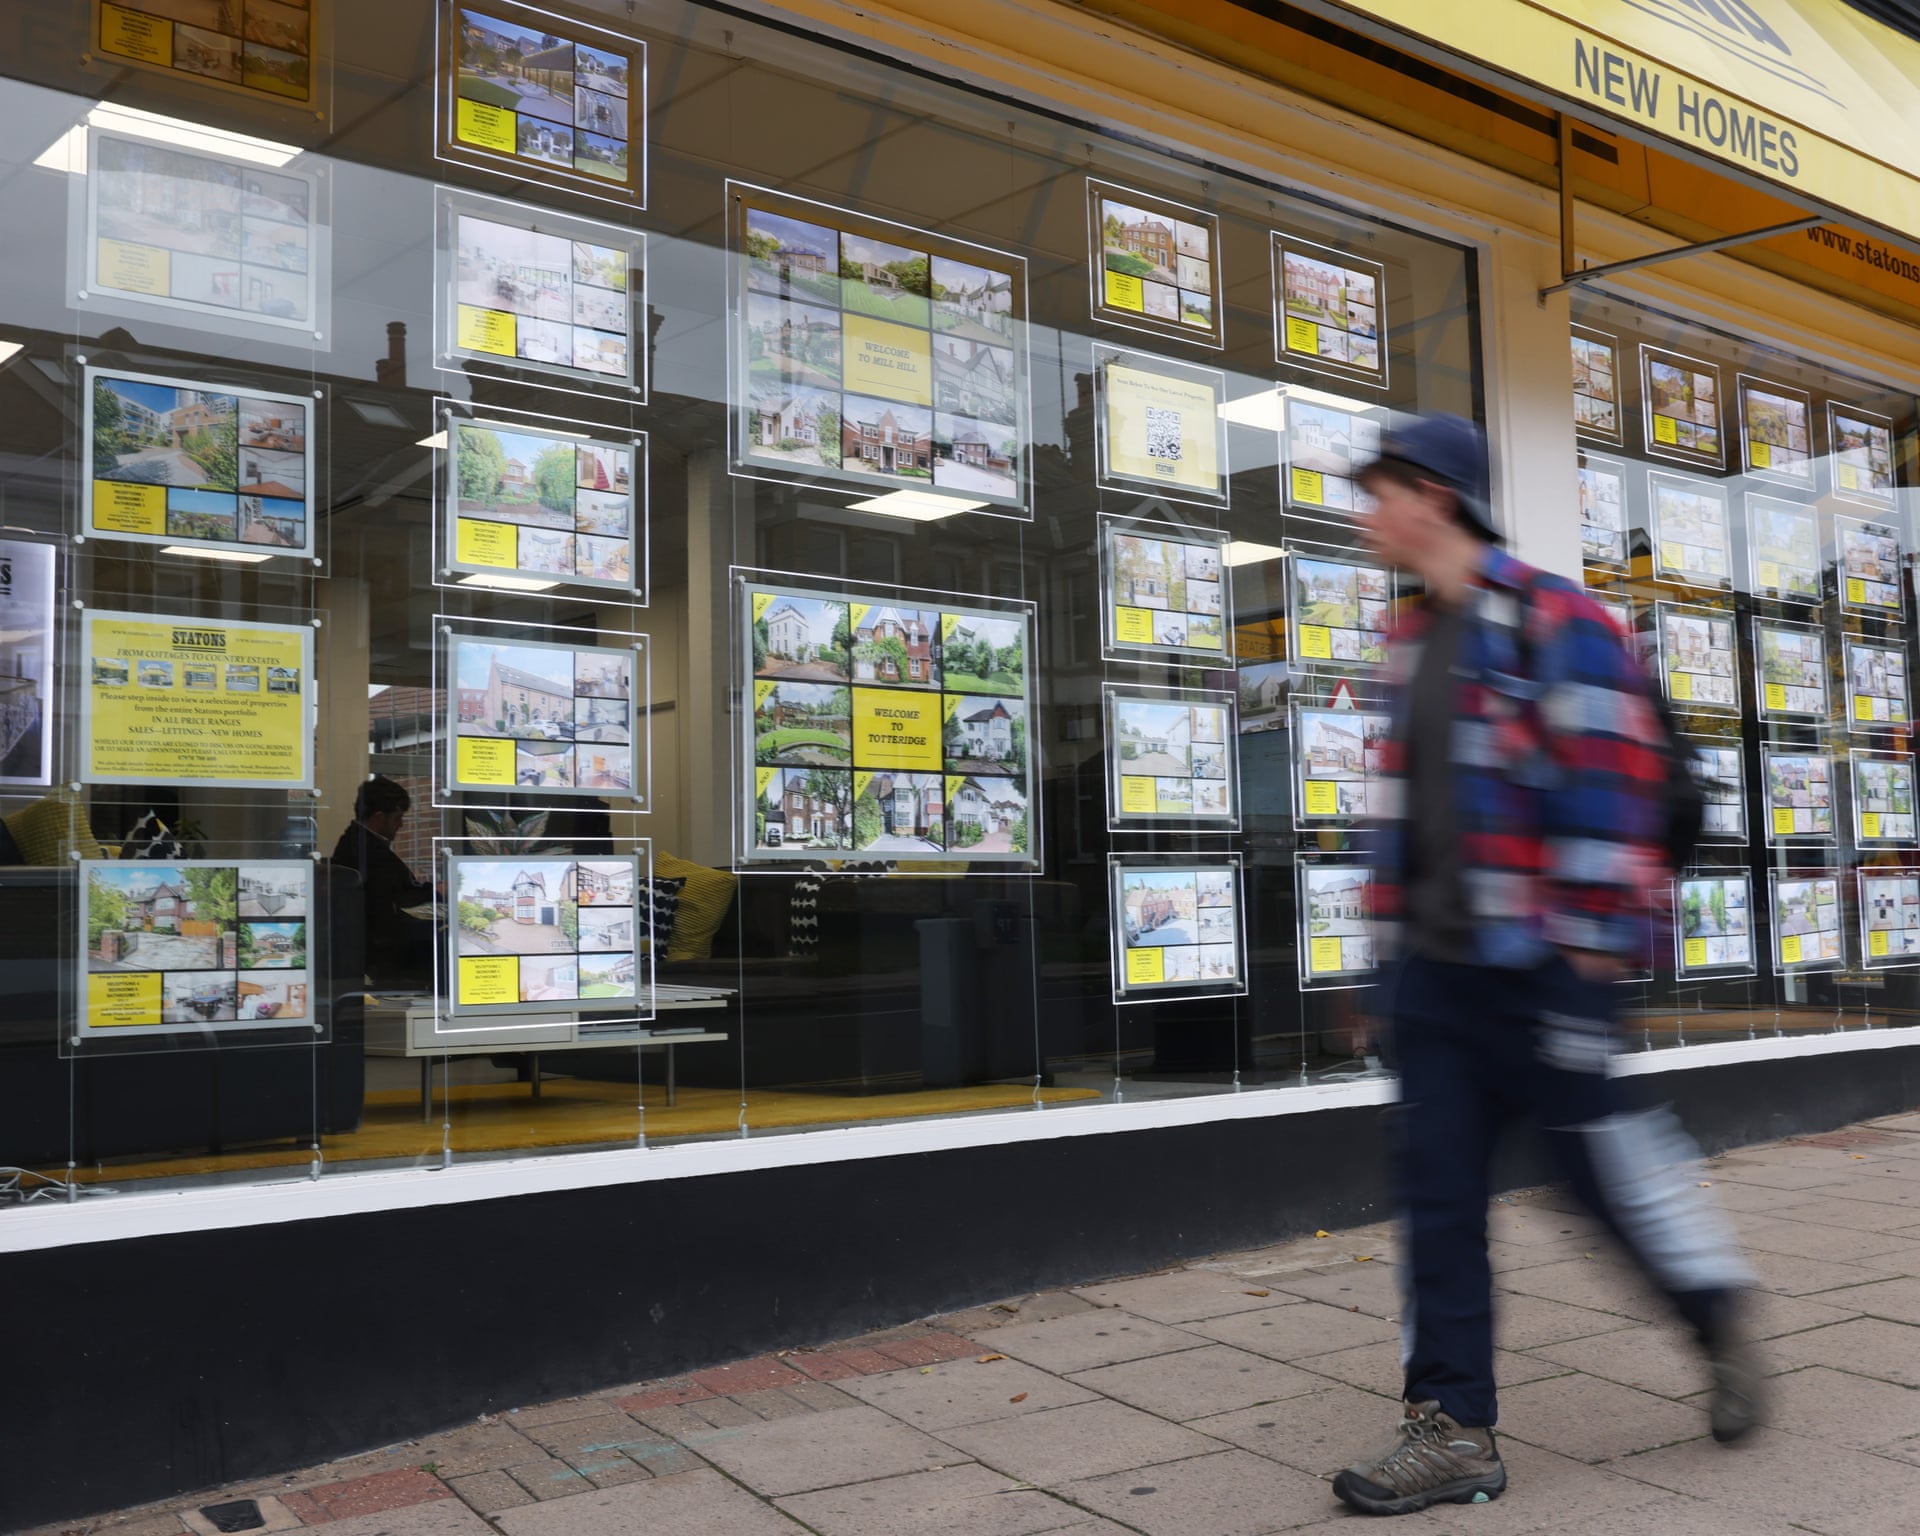
On the flip side, savers may see some relief. The base rate hike is expected to help numerous savers with easy-access accounts or other accounts that don’t have fixed interest rates. While the average easy-access savings rate was 2.58% on Thursday morning, the best buy easy-access accounts pay up to 5%. Fixed-rate savings bonds are paying even more, with some top deals at 5.4%. However, savers should be aware that banks are not obligated to pass on the full increase and may delay adjustments.
Bond Markets Price in Further Tightening
The financial market’s reaction was immediate and telling. Yields on U.K. government bonds, known as gilts, climbed. The yield on the benchmark 10-year gilt was last seen 2 basis points higher at 5.1546%, while the 2-year gilt yield rose by 4 basis points to trade at 4.782%. This pricing in by the bond market indicates traders expect further tightening. In fact, markets were pricing in a one-in-four chance of a further hike in December.
Gold, a traditional inflation hedge, proved resilient. Spot gold last traded at $4,128.54 an ounce, up 1.74% on the day. This suggests that while the rate hike is a factor for non-yielding assets, the underlying inflationary pressures remain a dominant narrative for precious metals traders. The bank’s own statement acknowledged that policy is not on a pre-set path, leaving the door open for volatility as incoming data on energy prices and wage growth will dictate the next move.
The Bank of England said the conflict in the Middle East is now in its ninth month and global energy prices have continued to rise from an already elevated level. The UK CPI inflation increased to 3.5% in September and is now expected to rise to around 5% by the middle of next year.
The path forward is precarious. The Bank of England has taken its first step to combat inflation, but its success depends entirely on events outside its control. A de-escalation in the Middle East could ease pressure on energy prices and the cost of living, potentially allowing the bank to pause. A further escalation or a failure to contain inflationary expectations would force more aggressive action. For now, the market is watching the Strait of Hormuz as closely as it is watching Threadneedle Street.
Disclaimer: The information provided in this article is for educational and market analysis purposes only and does not constitute financial, investment, or legal advice. Always consult with a certified financial professional before making investment decisions.
Keep reading
Albany Med CEO terminated amid assault allegations – WPTZ
The board of the Albany Med Health System terminated its president and CEO, Daniel T. Pickett III, on...

New Jersey Democrats rode a wave of Election Day triumphs into power this week, flipping seats in
Democrats' Affordability Mandate Echoes Through New Jersey Victories New Jersey Democrats rode a wave of Election Day triumphs...
Rebecca Christine Crawford Obituary 2026 Lynchburg VA
A Town Mourns Rebecca Christine Crawford News settled over the town like fog: Rebecca Christine Crawford, a 62-year-old...

Montana Republicans Retain Legislative Control Amid National Blue Wave
A Purple Tinge on the Big Sky: Montana's Electoral Shift The larch trees have turned gold in western...