
A Carson City homeowner tapped $110,000 in equity through a bank statement refinance
A homeowner in Carson City, Nevada, successfully accessed significant home equity through a specialized cash-out refinance that closed on November 3, 2026, emortgagecapital.com reported. The transaction involved a $110,000 loan against a property appraised at $380,000, leaving the borrower with approximately 71.1 percent equity and a loan-to-value ratio of roughly 28.9 percent.
This specific financing move highlights a growing trend among self-employed individuals in the Nevada market who find themselves “house rich” but “tax poor.” While traditional mortgage products often rely heavily on W-2 documentation or tax returns, this case utilized a 30-year fixed Bank Statement program. By focusing on actual cash flow rather than adjusted gross income—which is often lowered by legitimate business deductions—the borrower was able to qualify for liquidity that standard underwriting might have denied.
The complexity of the file required manual underwriting, a process where a human professional reviews the nuances of a borrower’s financial patterns rather than relying on an automated scoring system. This approach is essential for non-QM (non-qualified mortgage) products, as software often lacks the ability to interpret the consistency of business deposits or the legitimacy of irregular income streams common in contracting and professional services.
The mechanics of bank statement lending for self-employed residents
For many business owners and contractors in Washoe County, the gap between real earnings and taxable income can be a significant barrier to traditional credit. Standard underwriting frequently penalizes those who write off substantial expenses to manage their tax liabilities, as it creates a paper trail that suggests a lower capacity to repay debt than actually exists.
Im about to start a gofundme or some shit because i somehow have -150 dollars and there’s nothing in my bank statements that tell me why
The Bank Statement program bypasses this hurdle by analyzing 12 to 24 months of personal or business bank statements. Instead of looking at a single tax year, underwriters examine:
- The frequency and consistency of deposits.
- The overall pattern of business cash flow.
- The ability of the borrower to maintain a stable financial profile through deposits rather than just documentation.
In this Carson City instance, the borrower’s strong equity position acted as a secondary layer of security. Maintaining a loan-to-value ratio under 30 percent demonstrates a high level of “skin in the game,” which can mitigate the perceived risk of a manual underwriting process.
Carson City real estate stability and equity access
The ability to pull cash from a primary residence is heavily dependent on local property appreciation. Carson City occupies a unique economic niche within Nevada; as the state capital, it benefits from the stability of government employment, while its proximity to the Reno area and Lake Tahoe ensures a steady demand for residential real estate.
Property values in this region have shown notable resilience. For long-term residents, this appreciation has created a significant equity cushion. When a home appraises at $380,000, as seen in this recent closing, the gap between the debt and the value provides a window for capital infusion to fund other financial needs or business investments.
However, accessing this wealth is not a one-size-fits-all process. The efficiency of this particular closing—moving from application to funding in 41 days, with a “clear to close” status achieved by day 34—was largely attributed to three factors: organized documentation, a strong equity position, and clear communication regarding the specific requirements of non-QM lending.
Common questions regarding non-traditional refinancing
How does a bank statement loan differ from a standard refinance?
A standard refinance typically requires W-2s or tax returns to verify income. A bank statement loan uses 12 to 24 months of bank deposits to calculate qualifying income, making it more accessible for self-employed individuals whose tax returns may not reflect their true cash flow.
Is manual underwriting available in Nevada?
Yes, manual underwriting is a common component of bank statement and non-QM loans in Carson City and throughout Nevada. It involves a human underwriter performing a detailed analysis of a borrower’s financial situation rather than using an automated system.
What equity level is ideal for a cash-out refinance?
While requirements vary by lender, maintaining a high equity position strengthens an application. In the Carson City case, the borrower retained over 71 percent equity, which helped demonstrate financial strength during the underwriting process.
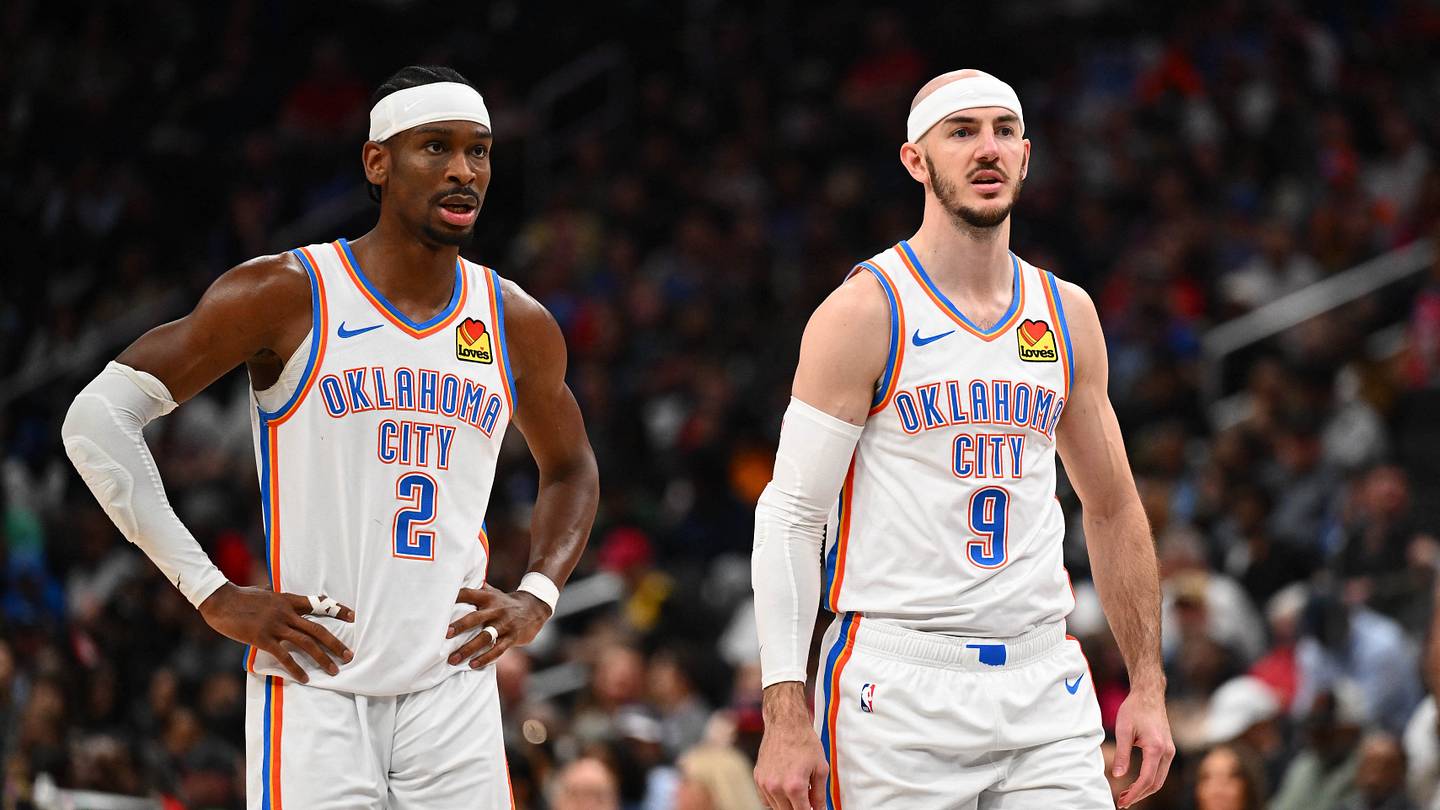
OKC Thunder host Washington Wizards with depleted roster
The Oklahoma City Thunder face a depleted roster on Saturday as they host the Washington Wizards at the...

Oregon Hammers Ohio State 41-28 to Stun Buckeyes in Columbus
Oregon overcomes early deficit to stun Ohio State in Columbus “We just kept stacking plays,” Dylan Raiola said...

New Mexico Experts Urge Winter Watering Despite Recent Rain
New Mexico homeowners face continued irrigation needs despite recent rainfall Recent rain has provided a much-needed reprieve for...
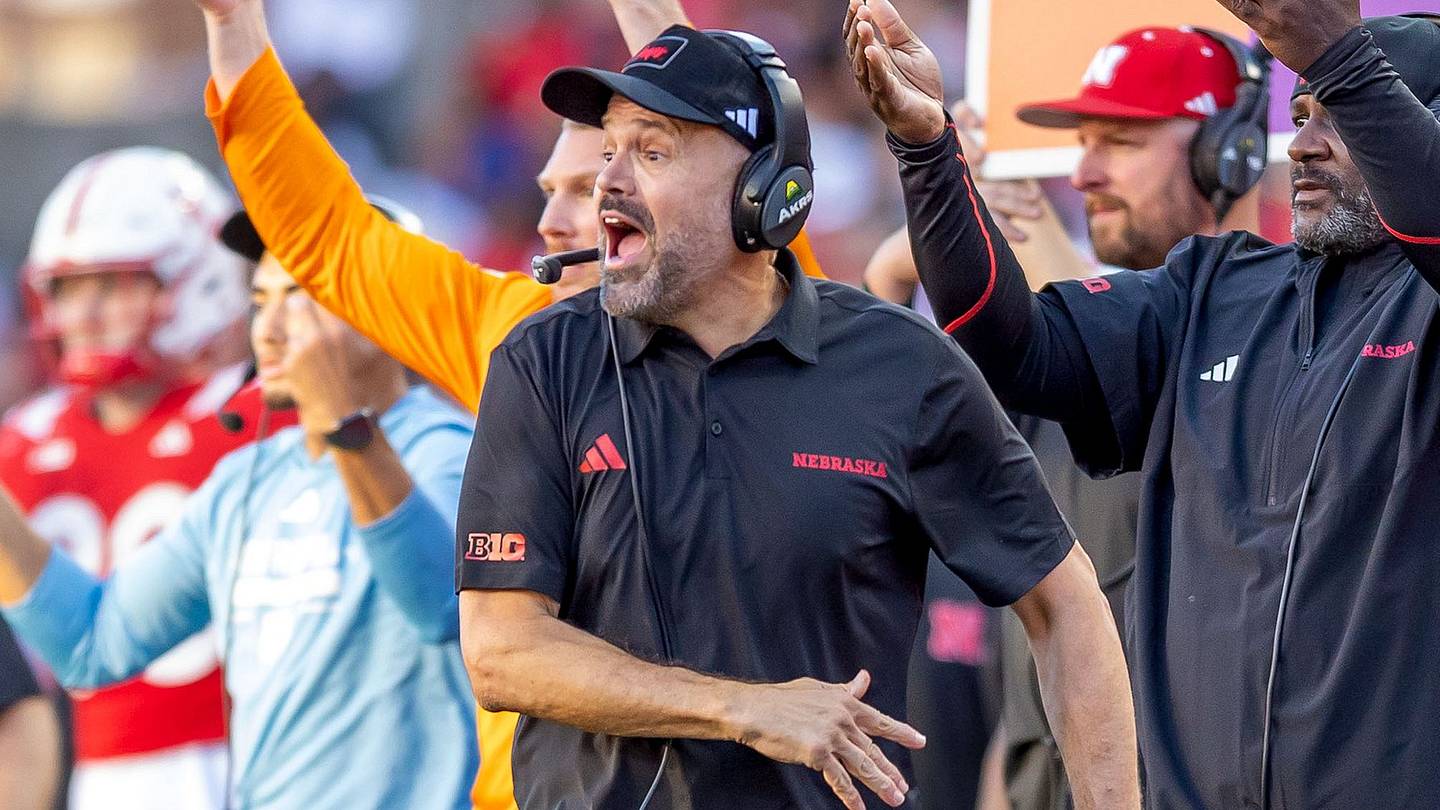
Six Candidates to Replace Dana Holgorsen as Nebraska Offensive Coordinator
Matt Rhule seeks new direction after firing Dana Holgorsen The Nebraska offensive landscape shifted abruptly on Saturday following...