
Boston Scientific is bracing for a difficult 2027, warning that a combination of pricing pressure in China and slowing demand for key heart-device technologies will likely stifle revenue and earnings growth. The medtech giant lowered its full-year profit forecast on Wednesday, triggering a 5.3% drop in share price as investors reacted to the outlook for its core growth drivers.
The company now expects 2026 adjusted profit to fall between $3.16 and $3.18 per share, a notable dip from its previous projection of $3.28 to $3.32. This shift puts the company below the average analyst expectation of $3.23 per share, according to data from LSEG. The immediate future looks equally lean; fourth-quarter sales are expected to slide between 1% and 3% year over year, with adjusted earnings projected at 77 to 79 cents per share—missing the 83 cents analysts had anticipated, Reuters reported.
China’s bulk buying squeezes margins
The primary headwind is a collapse in pricing power within the Chinese market. Beijing’s volume-based procurement (VBP) program—a system where the government purchases medical devices in bulk at sharply lower prices—is altering the economics of the region.
Chief Executive Mike Mahoney noted that these pricing headwinds will persist well into 2027. The impact is particularly acute in the company’s endoscopy business, where the pressure to lower prices is creating a ceiling on growth.
Watchman implant slump pressures cardiac portfolio growth
Beyond the pricing wars, the company is facing struggles with its cardiac portfolio. Specifically, the Watchman implant—a device designed to prevent blood clots and strokes—has seen a “softer uptake” in recent quarters.
The stakes here involve the company’s ability to offset losses. Mahoney warned that growth in other areas likely won’t be enough to counteract the combined pressure from the Watchman slump and challenges in electrophysiology.
The financial friction is further compounded by the cost of expansion. Boston Scientific’s $14.5 billion acquisition of Penumbra has been pushed back to the first quarter of 2027 due to longer regulatory reviews. This delay is more than just a calendar issue; in a high-interest-rate environment, the cost of financing such a massive deal increases, turning a strategic acquisition into a heavier drag on earnings.
The broader medtech trade-off
CFO Jon Monson was blunt about the trajectory, stating, We anticipate continued top-line pressure into 2027, which we expect will make it challenging to grow revenue and adjusted earnings per share.
The company now finds itself caught between a regulatory squeeze in Asia, a cooling market for its stroke-prevention tech, and the rising cost of borrowing to buy its way into new growth.
Related reading
Oklahoma early voting begins with four-day window and ID requirements
Oklahoma early voting is now officially underway, opening a critical window for residents to cast ballots before the...
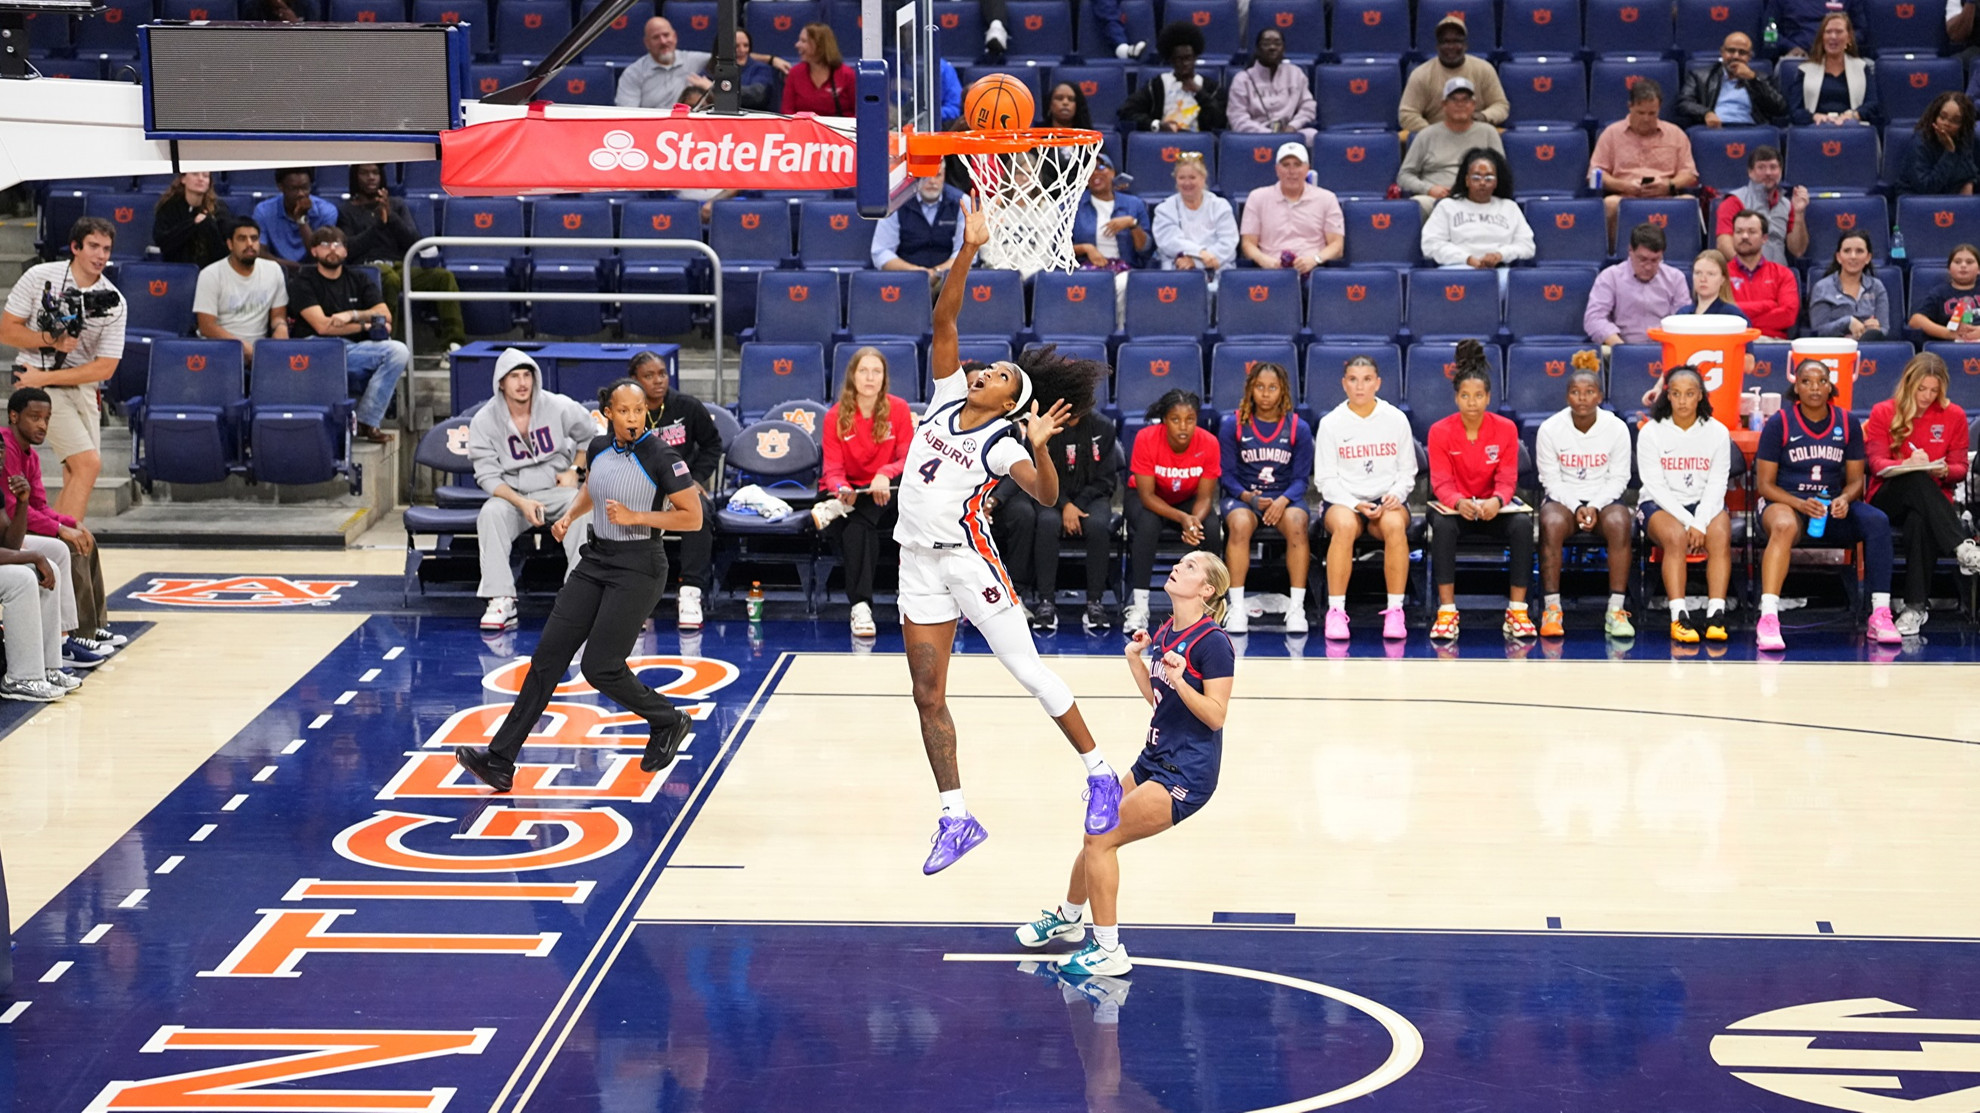
Auburn Women’s Basketball Dominates Columbus State 106-44
Auburn women’s basketball signaled its readiness for the 2026-27 season with a crushing 106-44 victory over Columbus State...

North Dakota farmers warn high fuel costs are unsustainable
North Dakota farmers are facing a precarious financial winter as high fuel costs continue to erode profit margins...
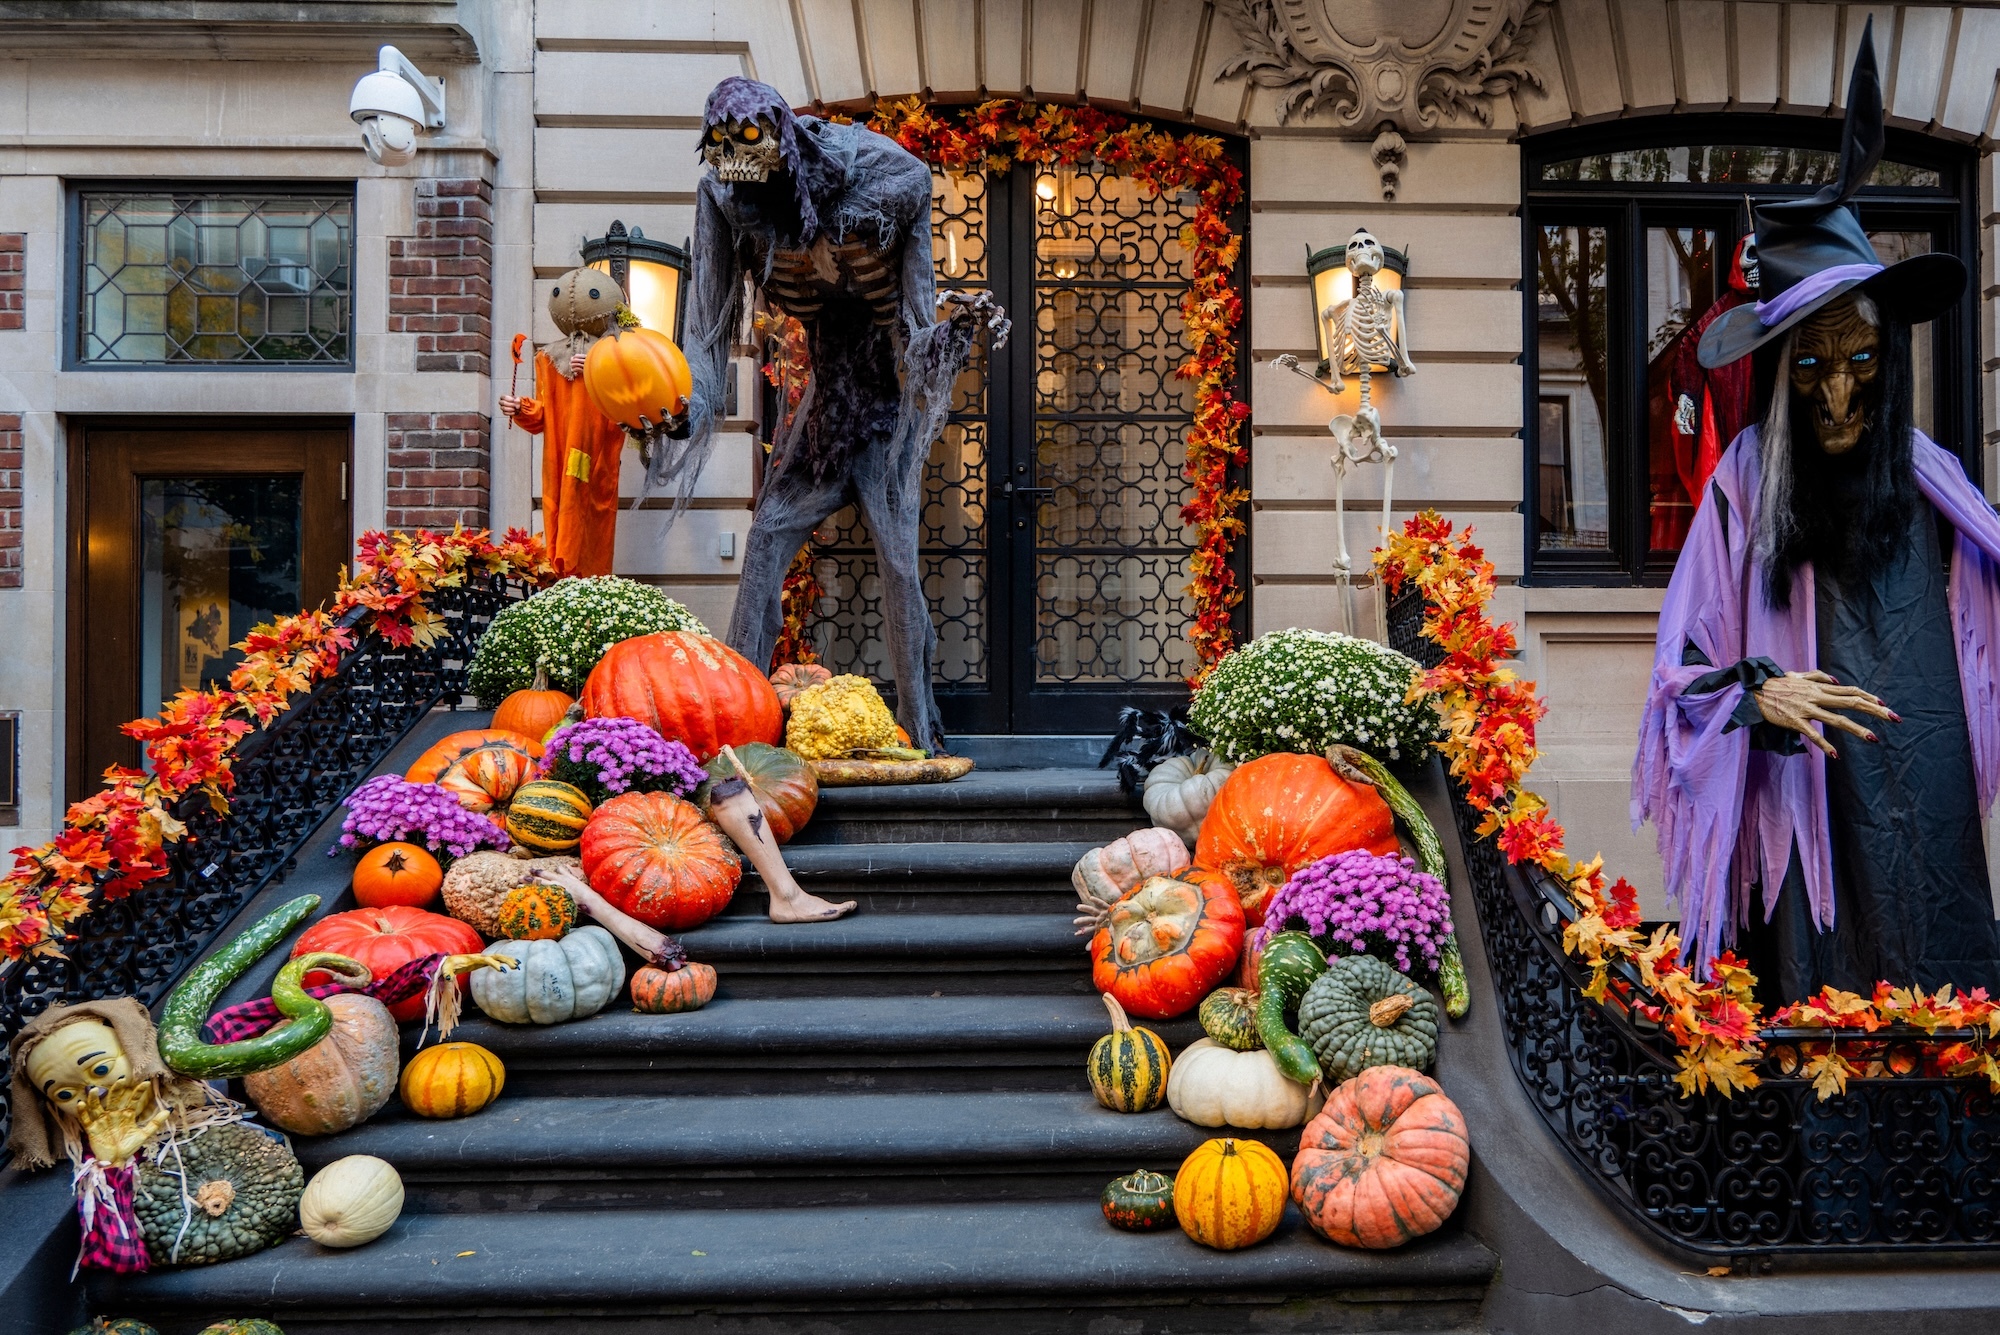
NYC Named Best US City for Halloween 2026 by WalletHub
New York City is officially the best place in America to celebrate Halloween in 2026, according to a...