
Venture Capital Limited Partners Face Concentration Risks and Pacing Pressure in AI Portfolios
Institutional investors providing capital to venture firms are navigating unprecedented valuations for market leaders like OpenAI and Anthropic, sparking widespread portfolio concentration across the private equity landscape. Limited partners are currently experiencing potentially lucrative returns alongside accelerated fund-raising cycles and faster capital deployment.
The Bottom Line:
- Top-tier artificial intelligence startups have driven massive portfolio concentration among venture capitalists backing the exact same handful of category leaders.
- Fund-raising cycles have compressed from traditional 24-to-36-month windows down to 12-to-18-month vintages as managers deploy capital faster into oversized late-stage rounds.
- Secondary markets have matured into a reliable third pillar of liquidity alongside traditional IPOs and corporate mergers and acquisitions.
The Shift From Diversification to High-Stakes Concentration
Traditional venture capital mechanics rely on diversified portfolios across generalist and specialist funds to minimize risk. However, skyrocketing valuations for foundational artificial intelligence developers have short-circuited that standard playbook. Nearly every major venture firm has piled into OpenAI and Anthropic simultaneously. Institutional backers describe the situation with cautious optimism, acknowledging the potential for massive windfalls while monitoring compressed funding timelines.
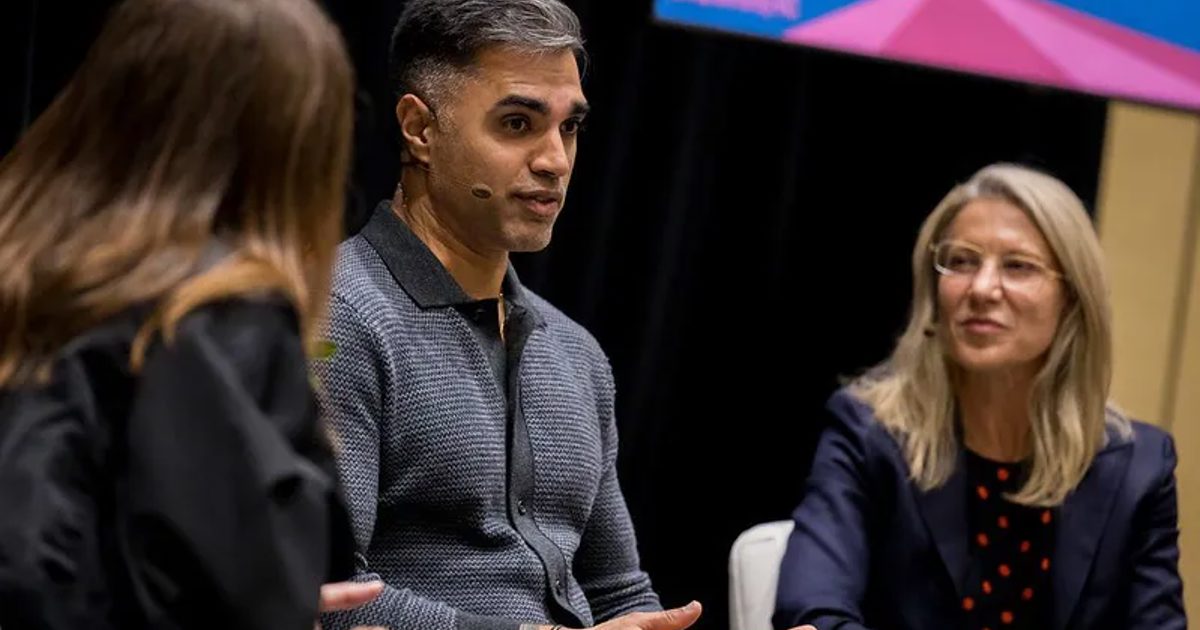
According to comments from Beezer Clarkson of LGT Capital Partners and Amit Bhatti of TrueBridge, the rapid consolidation resembles power-law outcomes seen in venture capital. Bhatti noted that mature funds naturally consolidate into breakout names like SpaceX, Stripe, and Databricks. At the same time, Clarkson emphasized that early-stage vehicles maintain greater diversity in smaller check sizes before aggregating upward.
Accelerated Pacing and the Yellow Light Warning
Fund deployment schedules have accelerated significantly from the historical norm of 24 to 36 months down to 12 to 18 months. Managers are frequently bumping up fund sizes mid-cycle to accommodate ballooning check sizes, particularly as seed rounds double and quantum capital requirements for artificial intelligence scale upward. Accelerated fund-raising cycles and faster capital deployment are raising yellow-light warnings among institutional investors.
Amit Bhatti of TrueBridge observed that venture has always been a power law business, so he views the concentration as a good thing, adding that in this generation of funds, he would hope there is a lot of Anthropic and a lot of OpenAI.
This aggressive pacing places severe strain on endowments, hospitals, and foundations that must meet operating commitments despite capital calls running hot with limited distributions coming back. Furthermore, vintages originated during the 2021 market peak continue to face valuation corrections, proving that compressed investment cycles carry outsized execution risks.
Secondaries Evolve Into Primary Liquidity Engines
To offset extended timelines for public offerings, secondary transactions have evolved from a distress signal into a sophisticated, highly utilized liquidity tool.
Disclaimer: The information provided in this article is for educational and market analysis purposes only and does not constitute financial, investment, or legal advice. Always consult with a certified financial professional before making investment decisions.
Related reading
Villa Vie Odyssey Passengers Stranded in Cambodia After Cruise Suspends Operations
California Sisters Stranded in Cambodia After Residential Cruise Halts Operations Two California sisters and over 200 other passengers...
Week 8 Fantasy Football WR/CB Matchups to Target and Avoid
As the NFL season reaches Week 8, defensive coordinators have accumulated seven weeks of film on every receiver...
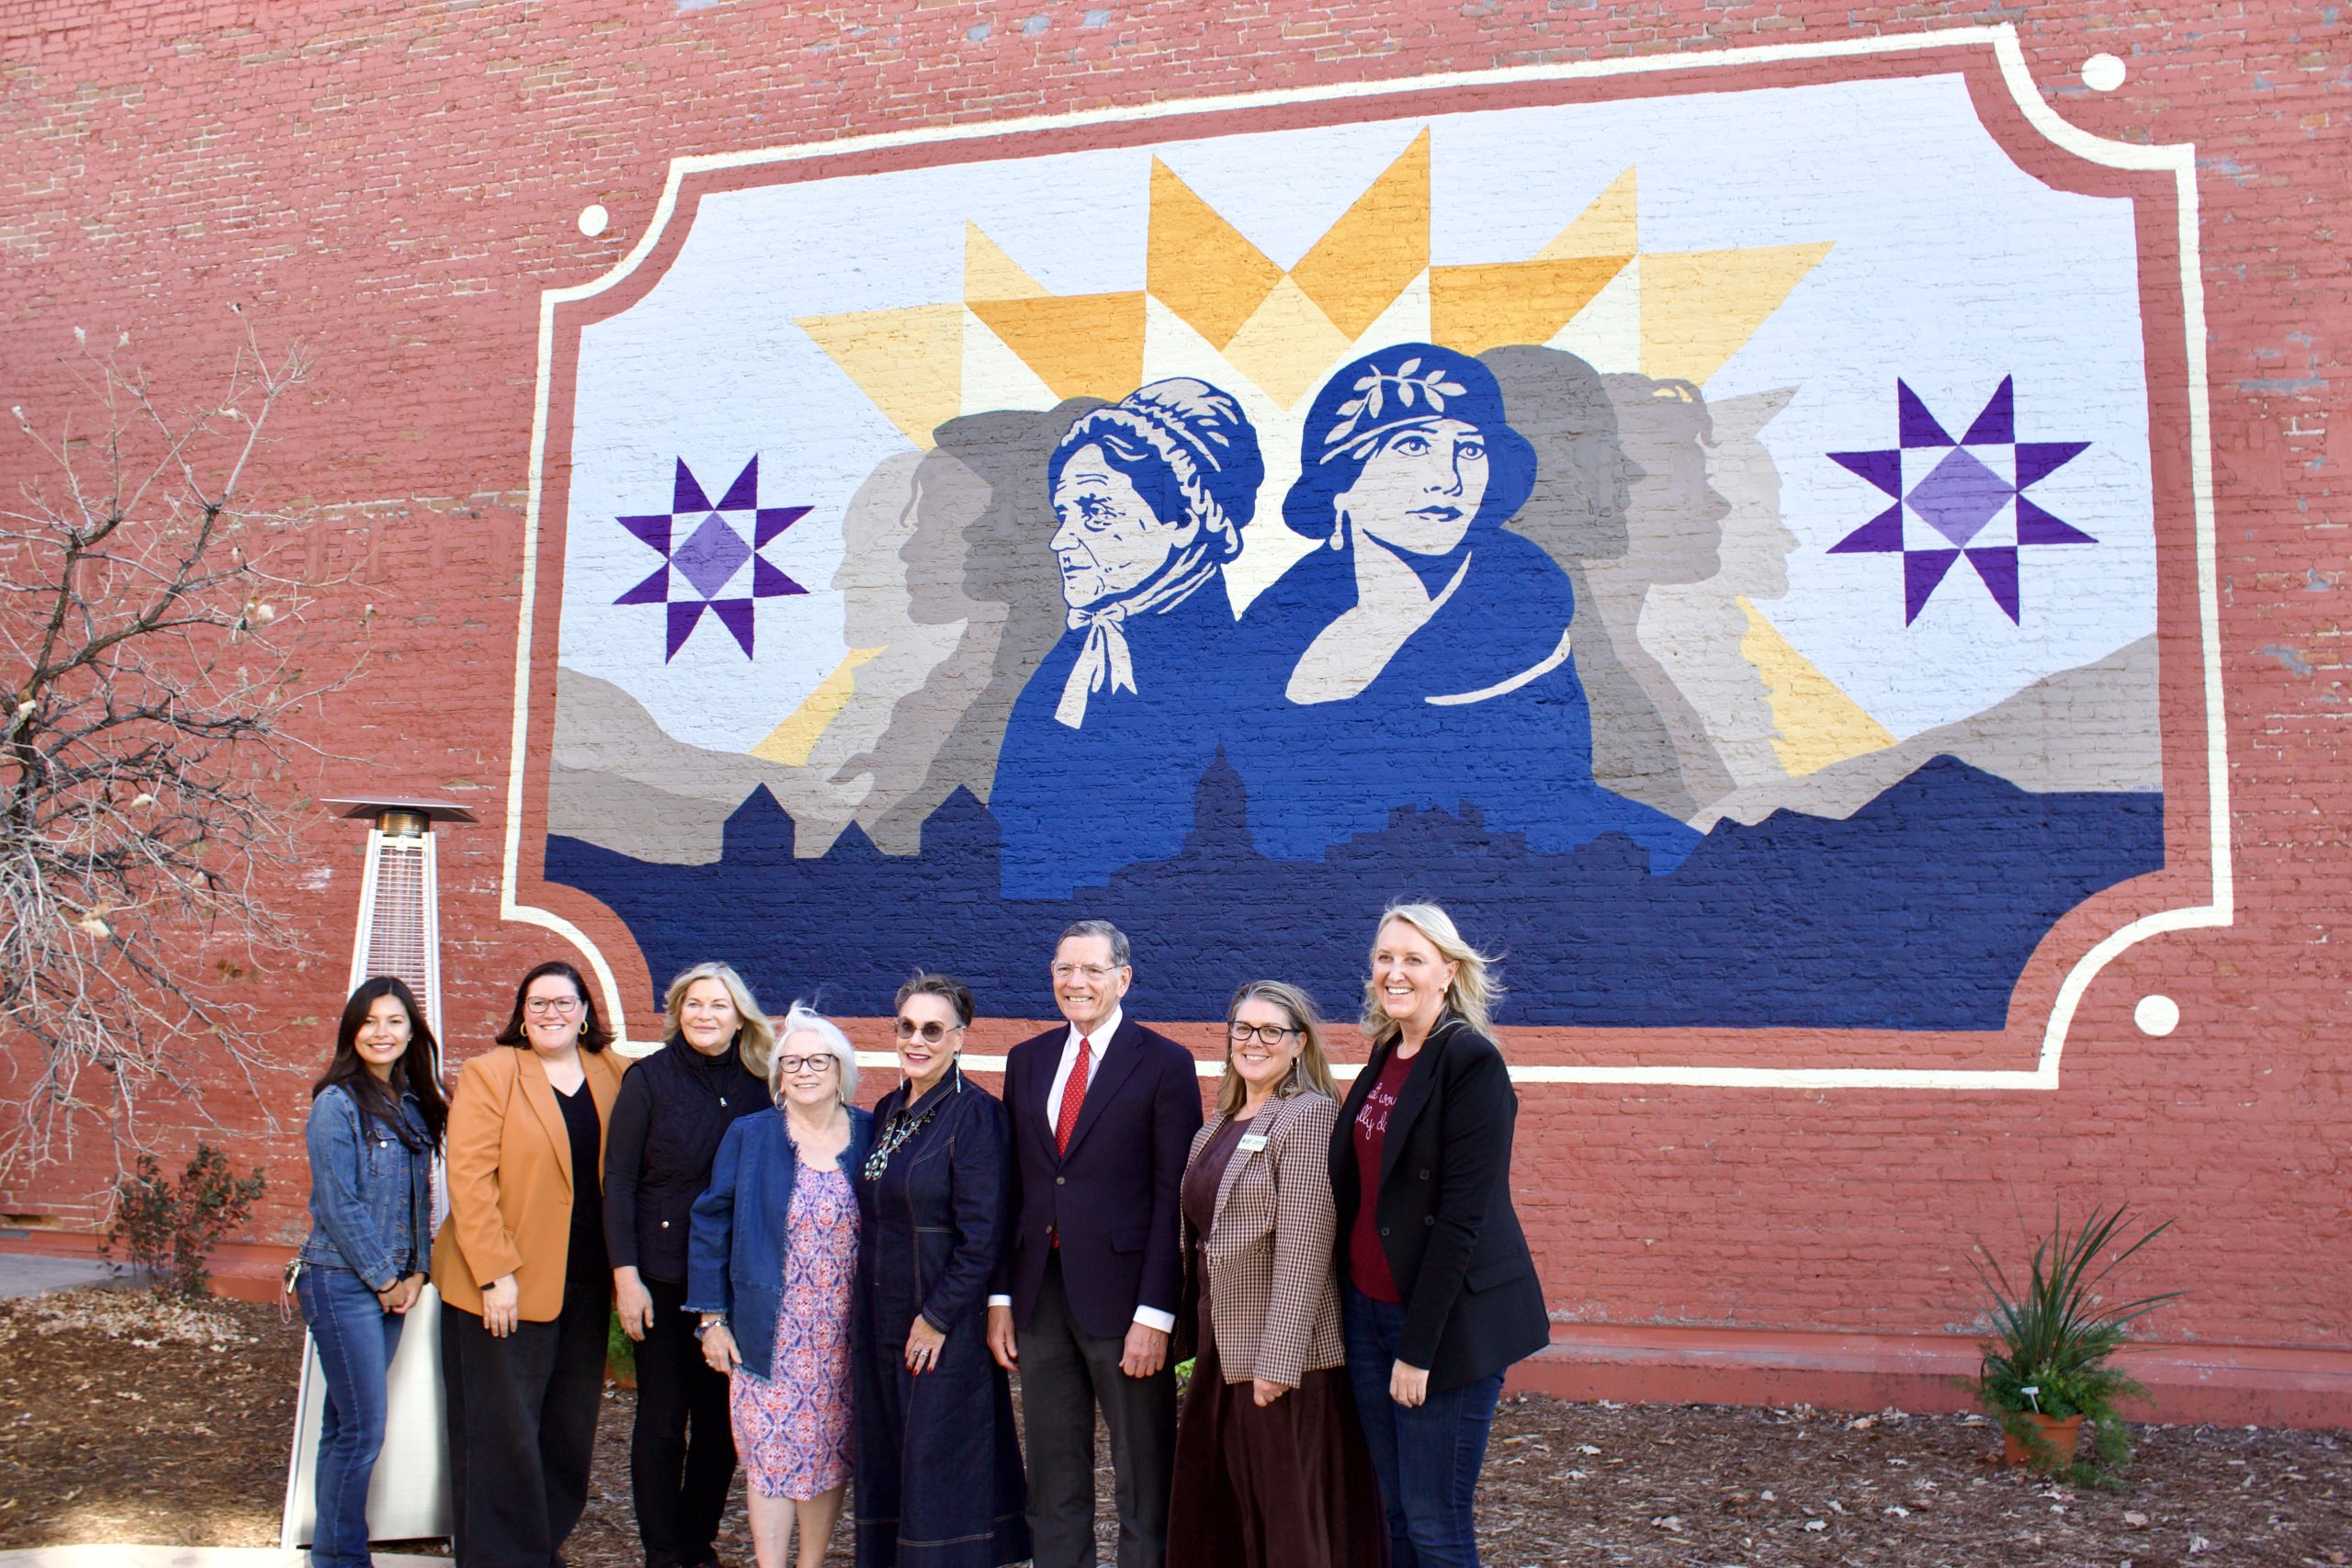
Wyoming Women’s History House Celebrates 25 Years With Courtyard Rededication
Twenty-Five Years of the Wyoming Women's History House in Laramie Twenty-five years ago, the Wyoming Women’s History House...

In-Person Absentee Voting Surges in Wisconsin as Mail-In Ballots Decline
As the final weekend before Election Day approaches in Wisconsin, voters are dramatically altering how they cast their...