
U.S. existing home sales fell to their lowest level since 2010 in October, according to new data from the National Association of Realtors (NAR).
The Bottom Line:
- Existing home sales dropped to an annual rate of 3.75 million in October, an 8.8% decline from the previous year.
- The 30-year fixed-rate mortgage hit a peak of 7.40% in October, the highest level recorded since 2023.
- Single-family home sales fell 5.8% from September, while condo and co-op sales hit a record low dating back to 2011.
Mortgage rates paralyze housing activity
High borrowing costs are effectively freezing the residential real estate market. The 30-year fixed-rate mortgage, the primary benchmark for home loans, hovered near 7.18% in October, according to The Guardian.
This surge follows a period of relative stability. Mortgage rates had been declining through 2024 and 2025, even dipping below 6% in February 2026, but rising inflation and geopolitical tensions related to the Iran war have pushed yields back up, The Guardian reported.
“It was a punch in the gut,” said Joel Berner, senior economist at Realtor.com, according to NPR.
Berner said that while a soft month was expected, the decline reached its lowest level since 2010.
Sales decline across most regions while Northeast holds steady
The slowdown is not uniform across the country. While sales in the Northeast held steady, significant declines were recorded in the Midwest, South, and West, The Guardian reported.
Specific regional data provided by Wolf Street highlights the severity of the slump:
| Region/Category | Metric Performance (October) | Historical Comparison |
|---|---|---|
| West (Single-Family) | Collapsed | Lowest since at least 1999 |
| Midwest (All Existing) | 900,000 annual rate | Lowest since 2011 |
| South (All Existing) | 1,730,000 annual rate | Lowest since January 2012 |
| Condos & Co-ops | 340,000 annual rate | Record low since 2011 |
Despite the drop in transactions, supply is actually increasing. Single-family home supply rose to 4.9 months in October, the highest level for any October since 2014, Wolf Street reported.
The Federal Reserve’s tightening impact
The contraction in the housing market appears to be a direct consequence of Federal Reserve policy. In September, the central bank raised its benchmark interest rate to combat inflation, a move that increased the cost of borrowing across the economy, NPR reported.
The Fed’s objective is to reduce economic activity to bring inflation under control. Policymakers have signaled that another rate hike could arrive in December, which may further depress housing volume, NPR reported.
“Home buying is difficult when mortgage rates have climbed to their highest levels since 2000, aside from a single month in 2023,” said Lawrence Yun, chief economist at the NAR.
This tightening cycle creates a “Main Street” squeeze. As mortgage rates climb, the barrier to entry for first-time buyers increases, while existing homeowners are often “locked in” to lower pandemic-era rates, preventing them from selling and contributing to the inventory imbalance.
Home prices fluctuate as specific metropolitan areas see drops
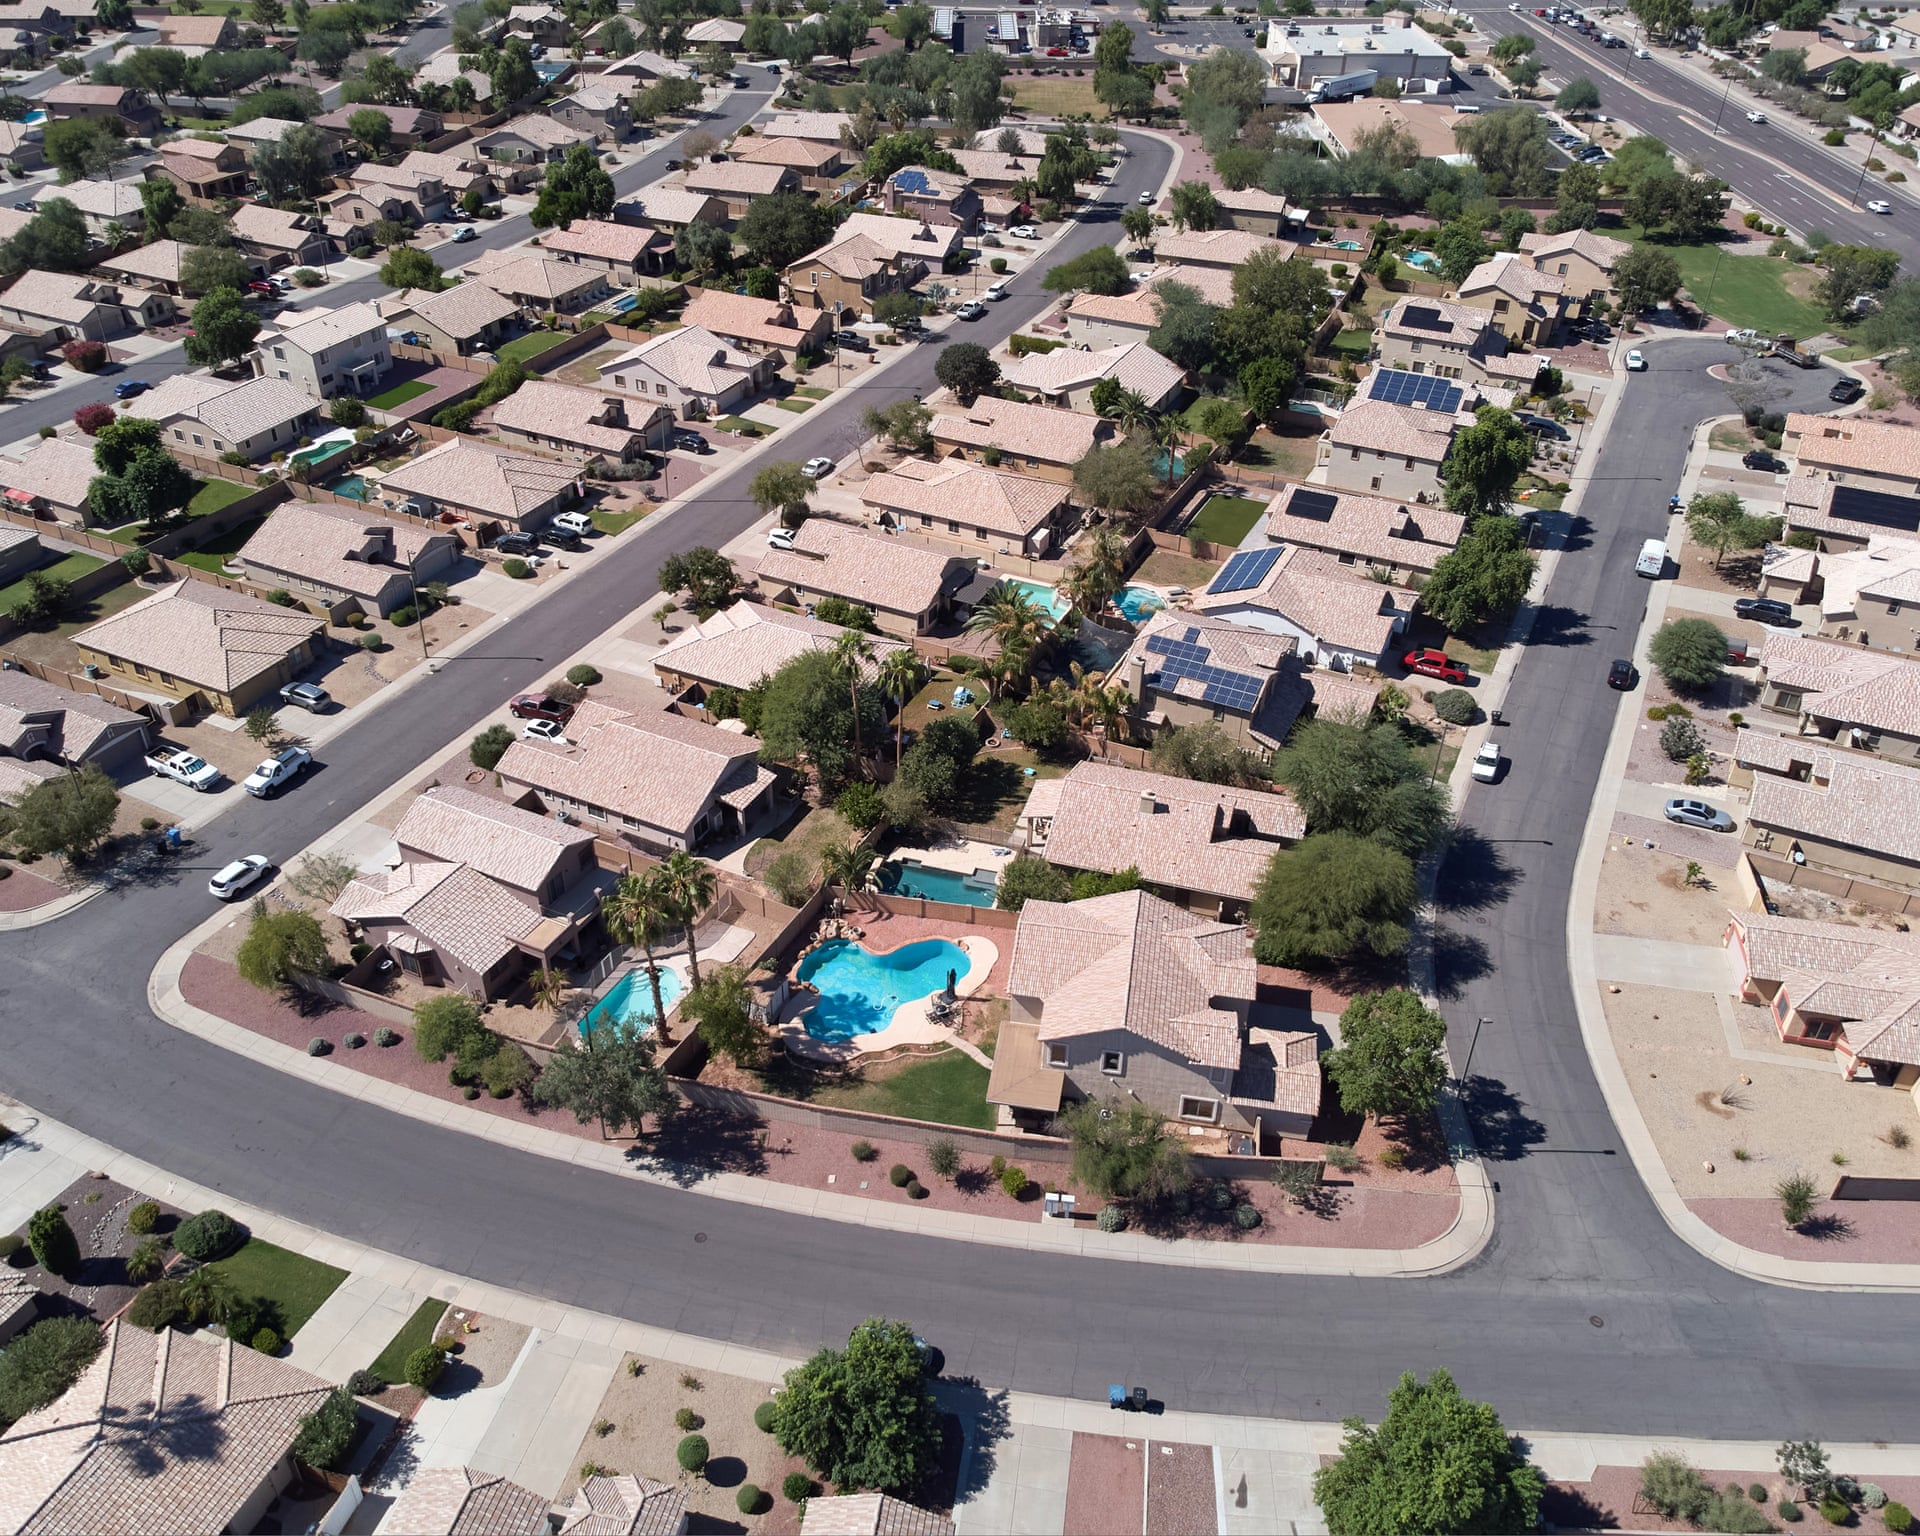
While sales volume has plummeted, home prices have not seen a uniform decline. The median existing-home sales price rose slightly to $416,700, The Guardian reported.
However, significant price drops are occurring in specific metropolitan areas. Wolf Street said that single-family home prices in Austin, Texas, fell by 26%, while Oakland, California, saw a 23% decline.
Conversely, some markets are seeing price increases that exacerbate affordability issues. In Chicago, prices rose 6.1% year-over-year, Wolf Street reported.
“I don’t think this is a new normal for home sales,” said Danielle Hale, chief economist at Realtor.com.
Hale suggested the current slump reflects a “perfect storm” of a shifting financial environment and pre-election economic uncertainty, The Guardian reported.
The market now looks toward the Federal Reserve’s December meeting to determine if the cycle of fiscal tightening will continue.
Disclaimer: The information provided in this article is for educational and market analysis purposes only and does not constitute financial, investment, or legal advice. Always consult with a certified financial professional before making investment decisions.
Related reading

Iowa Traffic Fatalities 15% Below Five-Year Average, Radio Iowa
Iowa traffic fatalities are running slightly higher than last year's record lows, according to data released during a...
Colts Must Rely on Jonathan Taylor to Stabilize Offense Against Dolphins
The Indianapolis Colts face a critical Week 10 matchup this Sunday against the Miami Dolphins at Lucas Oil...

ISU Office for Research Hosts Open House and Travel Award Raffle
Idaho State University will host a research-focused reception and open house on Monday, December 7. The event, organized...
USS Michael Murphy Returns to Pearl Harbor After 11-Month Deployment
The USS Michael Murphy returned to Joint Base Pearl Harbor-Hickam on Nov. 12, 2026, following an 11-month deployment...