Varonis Systems surpasses Q3 revenue and profit estimates
Varonis Systems (NASDAQ:VRNS) outpaced Wall Street’s expectations for the third quarter of 2026, driven by a significant jump in profitability and revenue growth. According to a report from StockStory, the data security firm generated $189.5 million in revenue, representing a 17.3% increase compared to the same period last year. This figure exceeded the S&P analysts’ consensus estimate of $186.7 million by roughly 1.5%.
🚨 $VRNS VARONIS Q3 2026: SAAS REVENUE SURGES 42%, EARNINGS BEAT EXPECTATIONS, AND FREE CASH FLOW REACHES $94.8M! Varonis Systems delivers solid quarterly results as demand for cloud-based data security and subscription services supports recurring revenue growth and improving… https://t.co/0HWstrAqBA
The company’s earnings per share also provided a major surprise to investors. While analysts had anticipated a non-GAAP profit of $0.03 per share, Varonis reported an adjusted EPS of $0.09, a result that Finance.Yahoo.com notes represents an earnings surprise of 200% relative to the Zacks Consensus Estimate. This performance marks a notable improvement over the $0.06 per share reported a year ago.
The underlying shift in Varonis’s business model is moving toward a software-as-a-service (SaaS) framework. This transition is not merely a technical change but a fundamental pivot in how the company captures value. As the company completes this migration, its ability to protect the “AI stack”—including automated red teaming and runtime protection—has become a central pillar of its growth strategy.
Profitability climbs as the SaaS transition nears completion
While the top-line revenue beat was narrow, the company’s ability to generate operating income was a standout metric. Varonis reported adjusted operating income of $7.59 million, which comfortably cleared the $3.05 million consensus estimate provided by analysts. This efficiency is particularly notable given the scale of the current transition.
The financial health of the company shows a mix of expanding margins and shifting cash flows. The following table summarizes the key financial results for the third quarter of 2026:
| Metric | Q3 2026 Actual | Analyst Consensus |
|---|---|---|
| Revenue | $189.5 million | $186.7 million |
| Adjusted EPS | $0.09 | $0.03 |
| Adjusted Operating Income | $7.59 million | $3.05 million |
However, the move to SaaS has introduced some complexities in how cash is collected versus how revenue is recognized. StockStory points out that while total revenue grew by 17.3%, billings—often viewed as “cash revenue”—rose by only 7.1% year-on-year to $192.9 million. This slower growth in billings suggests the company is recognizing revenue faster than it is collecting new cash, a trend that could create liquidity headwinds or signal a potential slowdown in future revenue cycles.
Management targets the end of on-premise support by year-end
The company is currently in the “late innings” of its migration from on-premise subscriptions to a SaaS model. During an earnings call, as reported by StockAnalysis.com, CFO Guy Melamed confirmed that SaaS now accounts for 89% of the company’s Annual Recurring Revenue (ARR). He noted that the company has set a firm deadline for the end of life for its on-premise products, scheduled for December 31, 2026.

The SaaS is in orders of magnitude a better product than what the on-prem subscription product is, the functionality, the value, the efficiency, what it requires from the customer. We are basically talking to customers about outcomes. We will do the stuff for you. You don’t have to manage it yourself as it was on the on-prem subscription side.
This transition was supported by a specific compensation structure throughout 2025, designed to incentivize sales representatives to convert existing on-premise customers to higher-value SaaS contracts. Melamed indicated that this focus on conversion is now shifting as the company nears the end of the migration period.
Market reaction remains cautious despite the earnings beat
Despite the strong numbers, the stock market’s immediate reaction was muted. Following the release, shares remained relatively flat at $48.66. This hesitation may stem from the discrepancy between the strong revenue/profit figures and the underwhelming 7.1% growth in billings. For long-term investors, the question is whether the new product offerings—specifically those targeting AI data security—can sustain the momentum required to drive the next phase of growth.
There is also the matter of sector volatility. Software companies often face high bars for performance due to the non-essential nature of certain services during economic shifts. While Varonis shares have climbed approximately 48.6% since the start of the year, significantly outperforming the S&P 500’s 10.2% gain, the “mixed” nature of the Q3 results—strong income but lagging billings—has kept analysts in a state of watchful waiting.
Looking ahead, the industry is watching closely as competitors prepare their own reports. Finance.Yahoo.com notes that Zscaler (ZS), another major player in the security industry, is expected to report its results soon, with analysts projecting a 19% revenue increase. The performance of Varonis will likely be measured against these broader industry trends as the company enters its final quarter of the on-premise era.

Southern Maine businesses embrace Nordic cuisine and lifestyle
Portland and Saco businesses embrace Nordic cuisine and lifestyle A growing number of restaurants and specialty shops across...

Trump and Beshear Clash Over Kentucky’s Key Congressional Race
Kentucky’s 6th District race serves as an early bellwether for the national election "Hello Kentucky, special place. I...
Children’s Mercy cuts 115 jobs and moves 473 staff to outside partner
Children's Mercy eliminates 115 jobs and transitions hundreds more to outside partner Children's Mercy is cutting 115 positions...
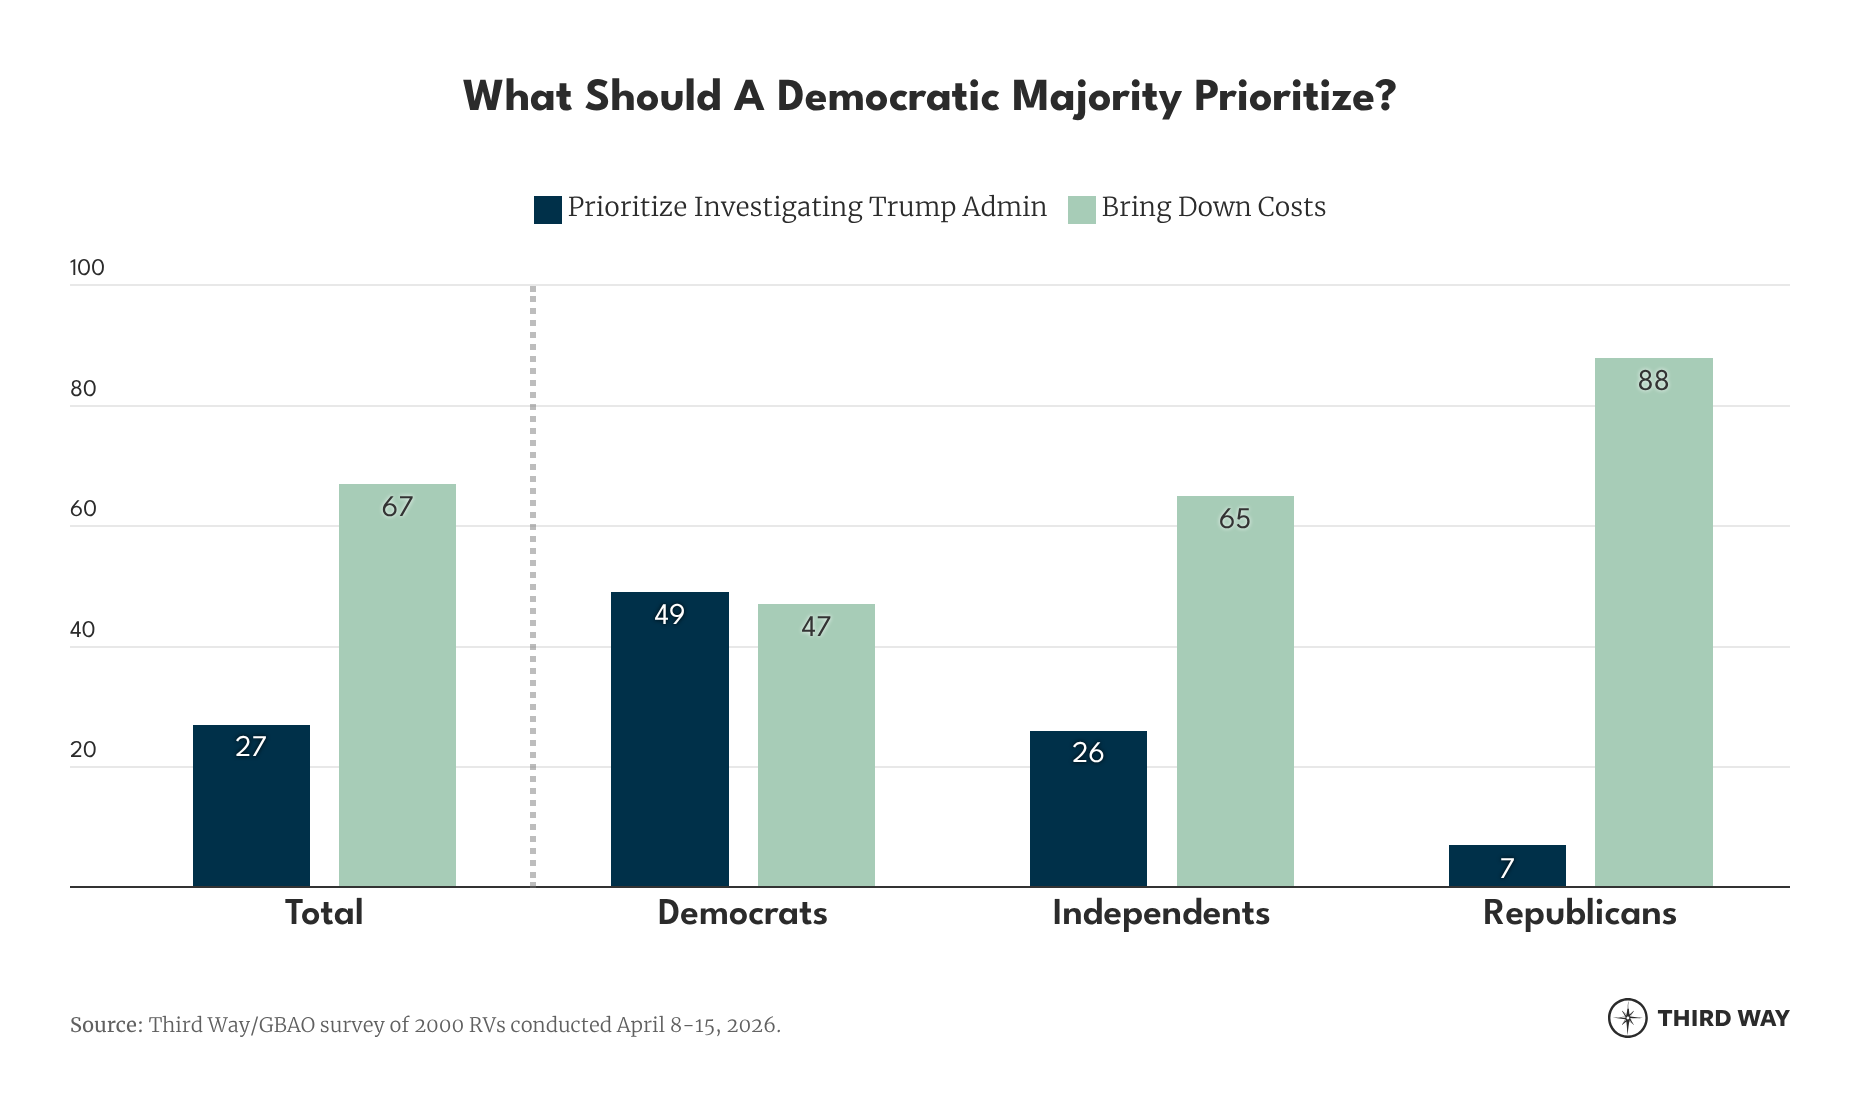
Democratic Priorities if They Retake the House of Representatives
If Democrats retake control of the House of Representatives, party leaders intend to prioritize a legislative agenda focused...