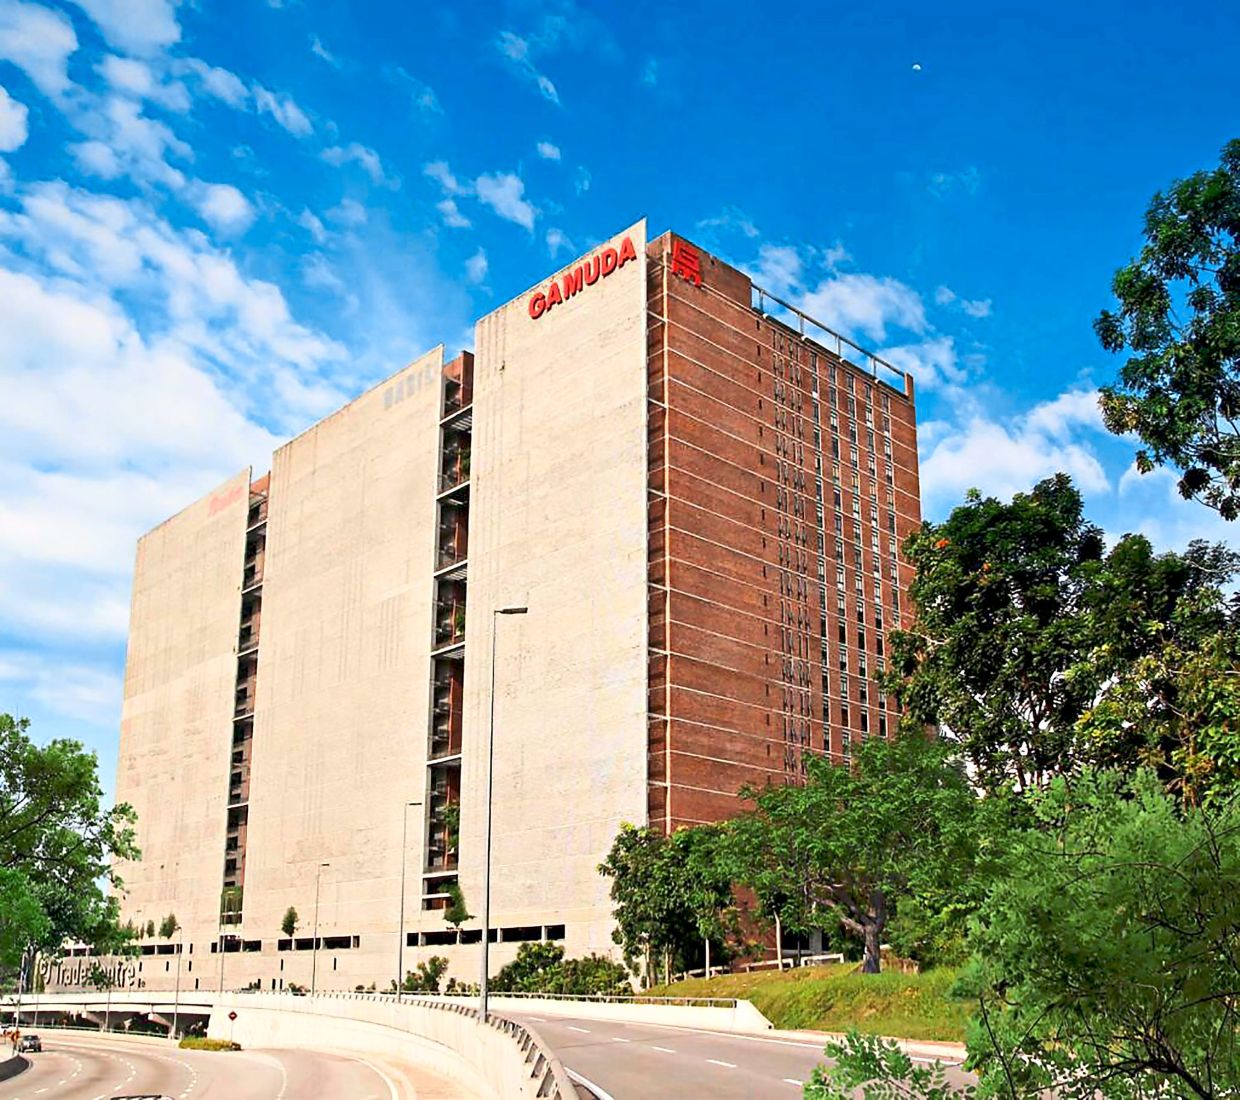
Gamuda Bhd posted a fifth consecutive year of record earnings for the financial year ended July 31, 2026, driven by domestic construction and overseas quick-turnaround projects.
Record Financial Results and Order Book Milestone
Gamuda Bhd closed its financial year ended July 31, 2026, with net profit topping RM1 billion for the second straight year, crossing into a milestone performance supported by robust construction activity. Full-year net profit rose to RM1.05 billion, representing a 5% increase from RM1 billion in the previous financial year.
In its filing with Bursa Malaysia, the company detailed that its growth marked its fifth consecutive year of record earnings. Earnings per share edged up to 17.80 sen from 17.61 sen a year earlier, while the group declared an unchanged dividend of 10 sen a share for the financial year. The sustained expansion of the business pushed its construction order book to an all-time-high balance of RM61 billion, accompanied by unbilled property sales totaling RM7.6 billion.
Fourth Quarter Performance and Division Drivers
For the fourth quarter ended July 31, 2026, net profit increased 5% to RM349.7 million from RM332.1 million in the same period a year earlier. Quarterly revenue advanced 18.9% to RM5.76 billion. The engineering and construction division anchored these gains, generating a pre-tax profit that accounted for 64% of group earnings.
Domestic construction earnings surged 49% to RM461 million, driven in large part by activity in the data centre segment. This domestic acceleration offset an 11% decline in overseas construction earnings as the first batch of projects in Australia neared completion. Overall construction earnings across both domestic and international markets rose 19% to RM742 million.
Conversely, the property development and club operations division experienced headwinds. Gamuda pointed to slower sales conversion across its Malaysian townships and noted that several newly acquired quick-turnaround projects alongside the Hanoi Parcel A development were still awaiting launch and regulatory approvals.
Geographic Shifts and Temporary Gearing Pressures
The geographic makeup of Gamuda’s balance sheet shifted during the year, with Malaysian operations expanding their share of the business. Consequently, Malaysian operations accounted for 51.2% of group net profit, up from 45.5% the prior year, while their share of revenue grew to 40.5% from 35.7%.
International expansion, however, brought short-term financial adjustments. Land acquisitions earlier in the year aimed at replenishing the quick-turnaround project portfolio in Vietnam and Singapore pushed net gearing to 72% at the end of July 2026. This temporarily exceeded the group’s self-imposed 70% limit, rising from 53% a year earlier.

Despite the elevated gearing, liquidity remained stable. The group generated nearly RM800 million in operating surplus cash during the year—with nearly all of that cash realized in the fourth quarter—allowing it to internally fund capital expenditure.
Outlook for Vietnam Projects and Construction Pipelines
Looking ahead to the financial year ending July 31, 2027, Gamuda anticipates that domestic construction projects, hyperscale data centres, and overseas quick-turnaround property developments will maintain earnings momentum. The company expects its gearing ratio to decline starting next year as cash inflows from its record order book and unbilled property sales materialize.
A primary driver for cash generation is the nearly sold-out Eaton Park project in Vietnam. Under Vietnamese property development rules, developers are permitted to collect up to 50% of the sales value during construction, with the remaining 50% collected upon handover. The company secured RM25.1 billion in new awards during FY26 and added another RM12.3 billion in FY27 to date, bringing total new wins to RM37.4 billion.
Market Reception and Analyst Revisions
Gamuda shares rose seven sen, or 1.4%, to close at RM4.98 on Tuesday, and climbed further in early trade on Wednesday to reach RM5.07 with shares traded, giving the group a market capitalisation of RM30.1 billion.
Market data compiled by AskEdge placed Gamuda’s price-to-earnings ratio at 28.7 times, positioning it higher than peer Sunway Construction Group Bhd, which traded at a price-to-earnings ratio of 24.5 times.
Keep reading
Aliko Dangote And William Ruto Set To Break Ground On Lamu Oil Refinery
Nigerian billionaire Aliko Dangote and Kenyan President William Ruto are set to break ground on a $16 billion...
China Factory Activity Returns to Growth in September as AI Demand Rises
China's official manufacturing purchasing managers' index rose to 50.1 in September, ending a two-month contractionary streak as easing...
Gold Hits Seven-Week Low as Treasury Yields and Crude Oil Prices Surge
Gold hovered near a seven-week low on September 29, 2026, stabilizing after a sharp four per cent rout...