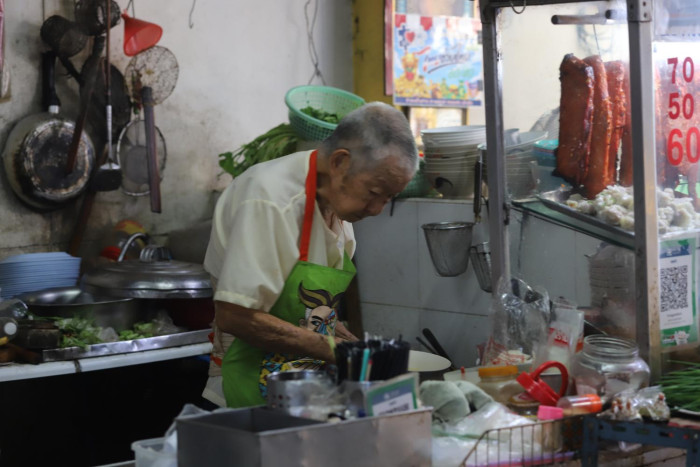
Thailand’s rapidly aging population is placing significant strain on the country’s pension system, with a recent study finding that nearly 70% of elderly citizens still rely on financial support from their children or continue working to earn a living. This situation arises despite projections that people over 60 will account for a third of the population within the next 25 years.
The Growing Demographic Challenge
Currently, individuals aged 60 and over comprise 24% of Thailand’s total population, according to a Kiatnakin Phatra Financial Group (KKP) study. The nation is transitioning towards a “fully aged society” – defined by a high proportion of older citizens – even as its income per capita remains relatively low. Thailand is ageing at a faster rate than its regional neighbors, despite having a lower income level.
Inadequate Savings and Limited Coverage
A key factor contributing to the pressure on the pension system is the widespread lack of adequate retirement savings among Thai workers. The KKP study revealed that 86% of Thais have either not established a savings plan or have been unable to maintain one. Furthermore, over 80% of existing savings are held in low-risk assets like bank deposits, which often fail to keep pace with inflation. More than half of Thai workers – 54% – are not covered by the social security system, and the old-age allowance covers only around 7% of living expenses.
Rising Costs and New Strategies
The strain on the system is further compounded by rising healthcare costs. Medical cost inflation in Thailand is forecast to reach 14.8% in 2026, significantly exceeding general inflation rates. Health insurance policies are also increasingly incorporating co-payment arrangements, requiring individuals to cover a larger portion of their medical expenses. In response, KKP introduced a two-stage retirement investment strategy on Monday, featuring funds designed to accumulate wealth before retirement and generate income afterward. These include KKP Ready Retire funds targeting retirement in 2035 and 2045, alongside KKP Lifelong Income and KKP Advanced Income funds, which focus on dividend-paying stocks and fixed-income assets.
Pipat Luengnaruemitchai, chief economist at KKP, stated that relying solely on government welfare is insufficient to maintain a reasonable quality of life after retirement
. He also noted that government social welfare benefits could decline over the next 20 years as the financial burden increases.
Worth a look

Wilma Emmalee Austin of Huntsville, Arkansas Passes Away at 84
A Life of Connection in Northwest Arkansas Wilma Emmalee Austin, a longtime resident of Huntsville, Arkansas, passed away...
Election Day is Tuesday. Here’s where you can vote in Juneau. – KTOO
Alaska’s Juneau Votes in a Crucible of Change On Tuesday, November 2, 2026, voters in Juneau, Alaska, will...
Jury Convicts Little Rock Woman of Conspiracy to Commit Sex Trafficking of a Minor
Federal Jury Convicts Little Rock Woman in Sex Trafficking Conspiracy In a case that underscores the relentless efforts...

Women’s Basketball opens with Mississippi State in Starkville – University of North Alabama Athletics
North Alabama Women’s Basketball Faces SEC Powerhouse Mississippi State in Starkville The University of North Alabama women’s basketball...