
As retail investors increasingly turn to automated algorithms for market research and portfolio tweaks, a sharp divide has emerged between what artificial intelligence can calculate and what human judgment must actually govern. A 2026 report by 1 Finance, titled What Personalized Financial Advice Is Actually Worth and highlighted by Livemint, argues that while software excels at pattern recognition, true financial health requires managing behavior, family priorities, and complex life events that raw math cannot decode.
The marketplace has already rushed to adopt these tools. According to a 2026 survey of 1,000 U.S. adults conducted by SoFi and reported by KQ2, 75% of everyday investors now utilize artificial intelligence for investing-related questions. Among those users, 84% report engaging with AI tools on a weekly basis, and 86% state they have executed an investment decision based directly on AI-generated insights.
The Bottom Line:
- 75% Adoption Rate: Three out of four U.S. investors now utilize artificial intelligence for investing questions, with 84% of those users relying on tools weekly, per SoFi survey data cited by KQ2.
- Pattern Recognition Value: Software efficiently handles high-cost fund detection, idle cash identification, and preliminary research, scoring a 9/10 in preliminary research capability according to analysis by The Villanovan.
- The Trust Deficit: While 80% of surveyed investors trust AI to some degree, only 26% trust it “a lot,” prompting 74% of users to consistently cross-check algorithmic outputs with secondary sources.
Assessing the Capabilities of Algorithmic Research
Artificial intelligence has fundamentally compressed the timeline for preliminary equity research. Traditionally, financial analysts spent hours reviewing corporate balance sheets, earnings statements, and macroeconomic indicators. Writing for The Villanovan, analysts note that AI can now complete much of this foundational screening in minutes, earning a 9/10 capability rating for research tasks.
The 1 Finance report corroborated by Livemint confirms that software is highly effective at isolating high-cost mutual funds and spotting idle cash sitting uninvested in brokerage accounts. Furthermore, KQ2 noted that nearly half of surveyed AI-using investors deploy the technology to compare investment options, screen equities, and evaluate portfolio risk or volatility.
Yet gathering data differs vastly from interpreting its wider implications. As The Villanovan points out, an algorithm can easily flag a declining profit margin, but determining whether that compression represents a temporary supply chain blip or a terminal operational failure requires contextual human judgment. Recognizing an inefficiency does not automatically establish the correct strategic countermeasure.
The Behavioral Barrier in Portfolio Management
Technology models mathematical outcomes efficiently, but it struggles to alter human impulse during market volatility. The 1 Finance report emphasizes that behavioral coaching—preventing investors from making emotional errors or abandoning long-term strategies—remains a primary value driver of personalized financial guidance.
When market stress hits, investors often contemplate halting systematic investment plan contributions or liquidating assets prematurely. While software can simulate the long-term mathematical penalty of such choices, persuading a household to reconsider a major capital reallocation requires empathy and an understanding of underlying family priorities.
Autonomous trade execution presents an even starker contrast. Systems permitted to trade independently without human oversight have yielded mixed experimental outcomes, with some models generating positive alpha while others incur steep losses. As The Villanovan observed, raw computational speed does not automatically translate into successful long-term investing.
Evaluating the Six Core Pillars of Household Wealth
Judging financial advice solely by short-term portfolio returns overlooks critical vulnerabilities across a household’s broader financial architecture. The 1 Finance study outlines six essential dimensions that comprehensive planning must cover: estate planning, liabilities, investments, cash flow, insurance, and tax management.
An equity portfolio can post strong gains while severe risks remain hidden elsewhere in the financial plan. Outdated beneficiary designations, inadequate term life insurance, inefficient debt structures, or a lack of short-term liquidity for unexpected expenses can trigger severe financial friction that conventional performance benchmarks completely ignore.
SoFi’s survey data reveals that inaccurate or misleading information remains the primary fear for 42% of AI-using investors, followed by privacy and security risks at 38%. Consequently, three-quarters of these investors maintain a strict verification protocol, cross-referencing automated insights before committing capital.
Ultimately, artificial intelligence functions as an effective analytical assistant rather than an autonomous fiduciary. As algorithmic tools continue to evolve across personal finance platforms, their primary utility lies in organizing data and accelerating research, leaving the burden of judgment and behavioral discipline firmly in human hands.
Disclaimer: The information provided in this article is for educational and market analysis purposes only and does not constitute financial, investment, or legal advice. Always consult with a certified financial professional before making investment decisions.
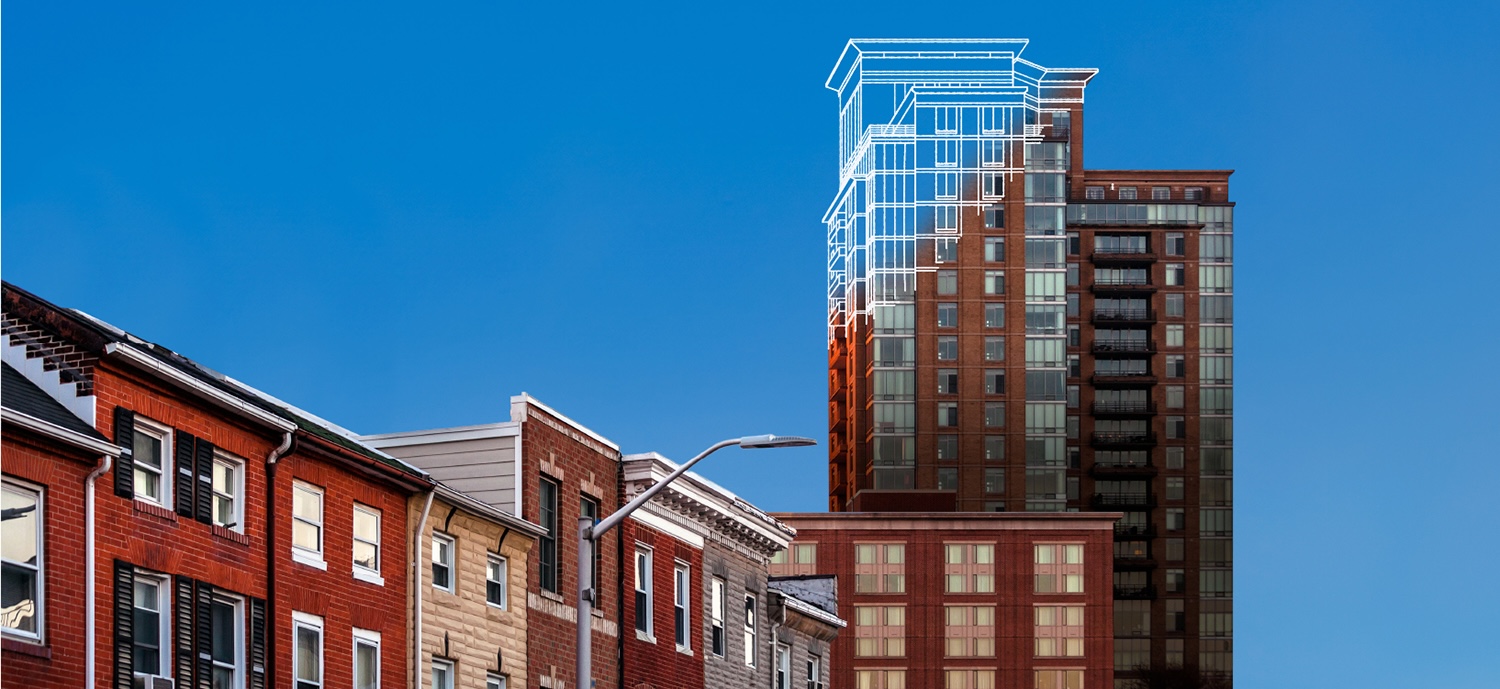
Building for Tomorrow is Better for Business Today – New York YIMBY
New York State is doubling down on a simple premise: building multifamily housing that barely touches the planet...
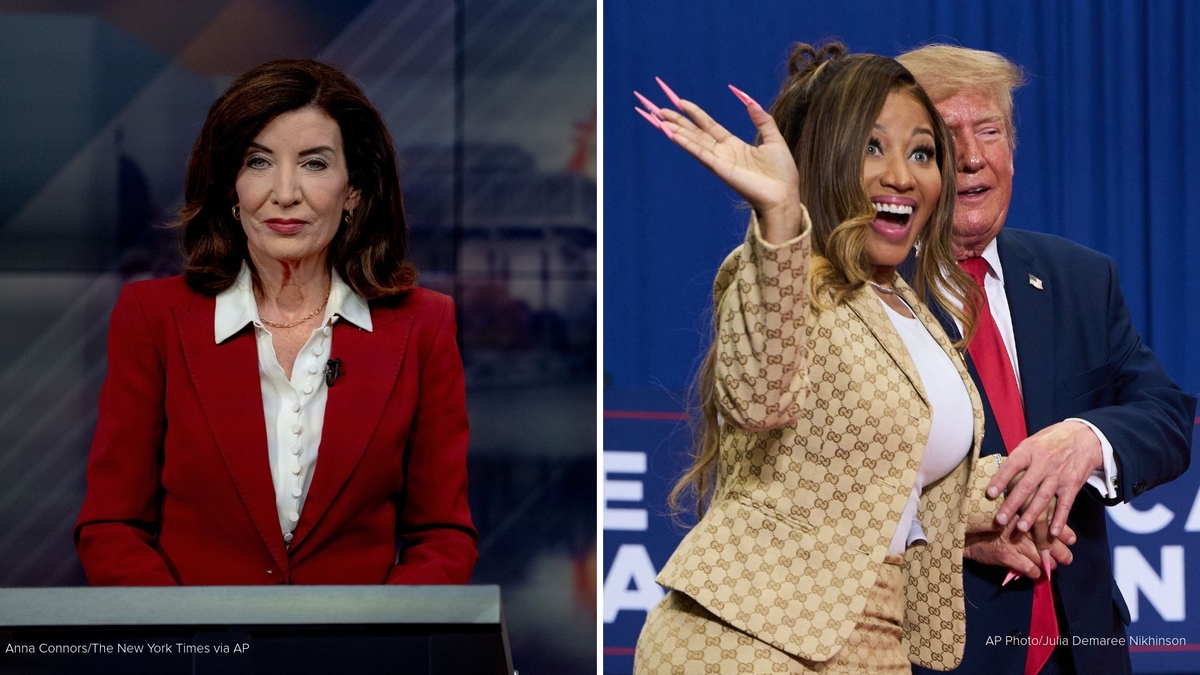
New York Governor Kathy Hochul responds after rapper Nicki Minaj calls her ‘evil
Rapper Nicki Minaj and New York Governor Kathy Hochul Trade Sharp Words in Final Days of Campaign New...
As Above, So Below Distillery | Santa Fe Spirits – New Mexico Magazine
Magic, Botanicals, and High-Rye Bourbon in Santa Fe Caley Shoemaker never expected a surplus of neighborhood fruit to...

Amick Farms expands South Carolina footprint with new Edgefield County operations
Amick Farms Invests $54.78 Million to Build Trenton Hatchery Amick Farms is expanding its South Carolina footprint with...