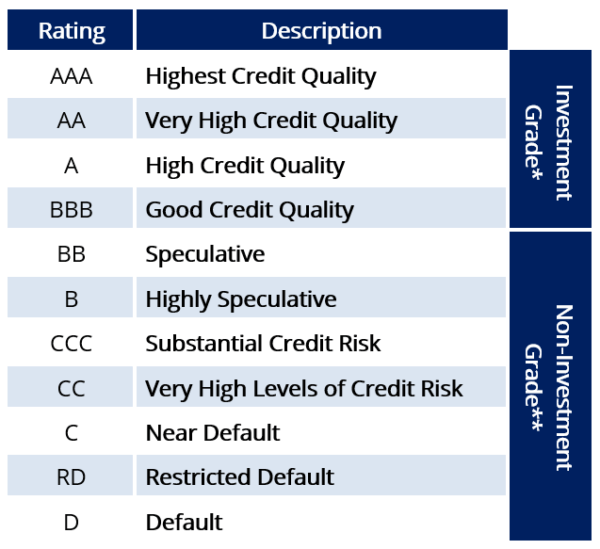
Digital Realty Trust is tapping the Swiss franc debt market with a CHF 510 million senior unsecured green notes issuance. Fitch Ratings assigned the securities a BBB rating with a stable outlook, backed by data center demand driven by artificial intelligence workloads and cloud adoption.
The financing package is issued by Digital Constellation B.V. and fully and unconditionally guaranteed by Digital Realty Trust, Inc., Digital Realty Trust, L.P., and Digital Intrepid Holding B.V. Proceeds from the offering are earmarked for eligible green projects under the company framework alongside general corporate purposes, which include paying off near-term debt maturities.
Digital Realty Trust is entering the Swiss franc debt market as demand for data center capacity remains supported by artificial intelligence workloads, cloud adoption, and migration away from on-premise infrastructure. The CHF 510 million issuance is backed by group guarantees and is intended to fund eligible green projects as well as general corporate needs, including near-term debt repayment.
Swiss Franc Green Notes Structure and Maturities
The CHF 510 million debt package is divided into three distinct tranches maturing across the next decade. According to ratings disclosures, the issuance consists of CHF 225 million in notes due in October 2029, CHF 185 million due in October 2032, and CHF 100 million due in October 2036.
- CHF 225 million of 1.6803% notes due October 2029
- CHF 185 million of 2.06% notes due October 2032
- CHF 100 million of 2.415% notes due October 2036
These securities rank equally in right of payment with existing and future senior unsecured obligations across the issuer and guarantors, including the group’s global revolving credit facilities.
AI Demand Fuels Record Leasing Activity for Digital Realty
Credit metrics for Digital Realty continue to benefit from structural tailwinds. Demand growth—particularly for hyperscale artificial intelligence applications—outpaces available supply, fueling record leasing activity, firm pricing dynamics, and an expanding development pipeline.
A downturn in technology spending or overall capacity demand could pressure operations, with the rating agency indicating that a slowdown in artificial intelligence-led or overall demand could weigh on the business.
Fitch expects the company's debt-to-EBITDA ratio to stay within its 5x to 6x through-the-cycle expectations, as EBITDA growth from scheduled lease commencements offsets development debt; Fitch notes Digital Realty's ratio is in the high 4.0x range on a last-12-month REIT basis, leaving room within the current rating category and improving materially from several years ago.
Digital Realty Operates Facilities in over 30 Countries
As of June 30, 2026, Digital Realty owns, leases, and operates more than 310 facilities spanning over 55 cities across more than 30 countries on six continents.
Worth a look
Flydubai Co-Pilot Attacks Captain With Axe Over Saudi Airspace
An Israel-bound Flydubai flight narrowly avoided disaster on September 30, 2026, when its co-pilot attacked the captain with...
Amazon Slashes Up to $2,000 Off Hisense TVs During Prime Big Deal Days
Up to $2,000 comes off Hisense television ranges as Amazon’s Prime Big Deal Days event brings major discounts...
Amazon Discounts SSDs Ahead of Prime Big Deal Days Event
As Amazon’s Prime Big Deal Days event approaches, tech shoppers are racing to secure storage discounts during a...
Restricting Gemini Free Tier Access Starting October 9, 2026
Google is restricting its Gemini app models starting October 9, 2026, leaving free users with only the Flash-Lite...