Hartford Funds launched the Hartford Hybrid and Credit Opportunities ETF under the ticker HCOP with Wellington Management Company LLP as sub-adviser.
The fund arrives carrying a 0.55% net expense ratio and a mandate that deliberately blurs the line between fixed income and equity, targeting hybrid capital securities — preferreds, trust preferreds, convertibles, junior subordinated debt, and contingent convertible bonds — issued by corporate borrowers worldwide, according to its prospectus.
Wellington Management Company LLP can roam across investment-grade and below-investment-grade securities (junk bonds), any maturity, any duration, and use derivatives to manage risk or equitize cash.
“The hybrid and subordinated nature of the portfolio introduces layered risks,” the filing says, flagging that CoCos and additional tier 1 instruments can see principal written down to zero under regulatory triggers.
That history shows the predecessor returning 7.64% for the year ended December 31, 2025, 5.20% annualized over five years, and 5.46% annualized over ten years, each period outpacing the ICE BofA US All Capital Securities Index. But the current strategy only took effect July 31, 2026, meaning the track record reflects a different approach.
The conversion mechanic
ETF conversions have become a familiar playbook: an existing mutual fund swaps its wrapper, preserves its performance history, and instantly gains intraday liquidity and potential tax efficiency. HCOP follows that script, but the portfolio turnover rate of 73% for the fiscal year ended October 31, 2025 shows an active, opportunistic trading style that can generate meaningful transaction costs, the prospectus shows.
Where it sits in the lineup
Competing funds include JPIE, JCPB, PYLD, FBND, and BOND. The differentiation is structural: most rivals run broad bond mandates, while HCOP explicitly targets the hybrid capital structure — instruments that sit between equity and senior debt. Because the fund does not track an index, performance depends entirely on Wellington’s security selection and tactical allocation decisions.
Risk stack
Derivative use creates borrowed exposure and counterparty risk.
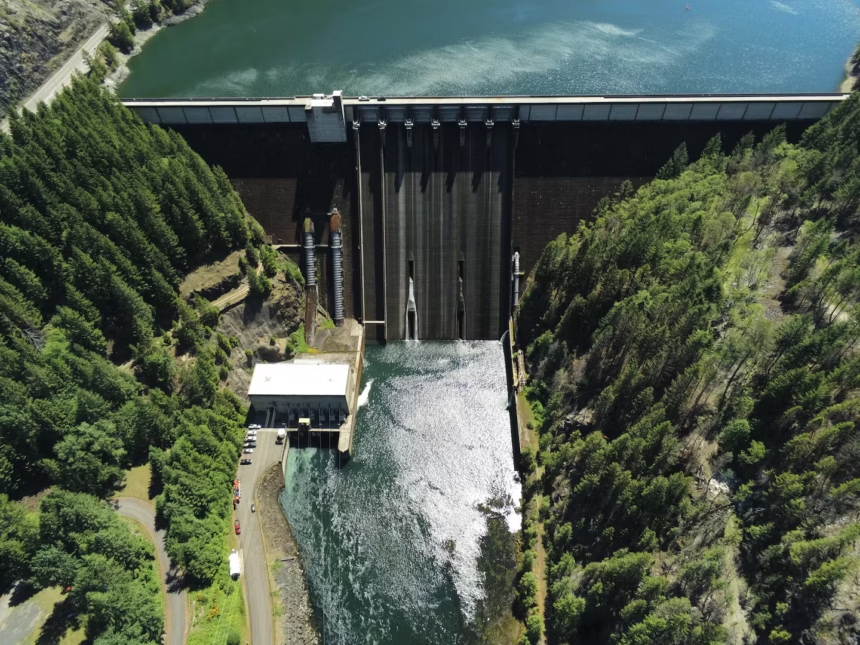
Army Corps Begins Detroit Reservoir Step-Down Drawdown to 1,425 Feet for Endangered Fish Passage
The U.S. Army Corps of Engineers will drop Detroit Reservoir to 1,425 feet later this month, the first...
Kentucky Utilities Says Grid Faces No Threat as 90-Day Blackout Posts Spread Online
Social media posts warning of a 90-day nationwide blackout collided with reality when Kentucky Utilities stated its grid...
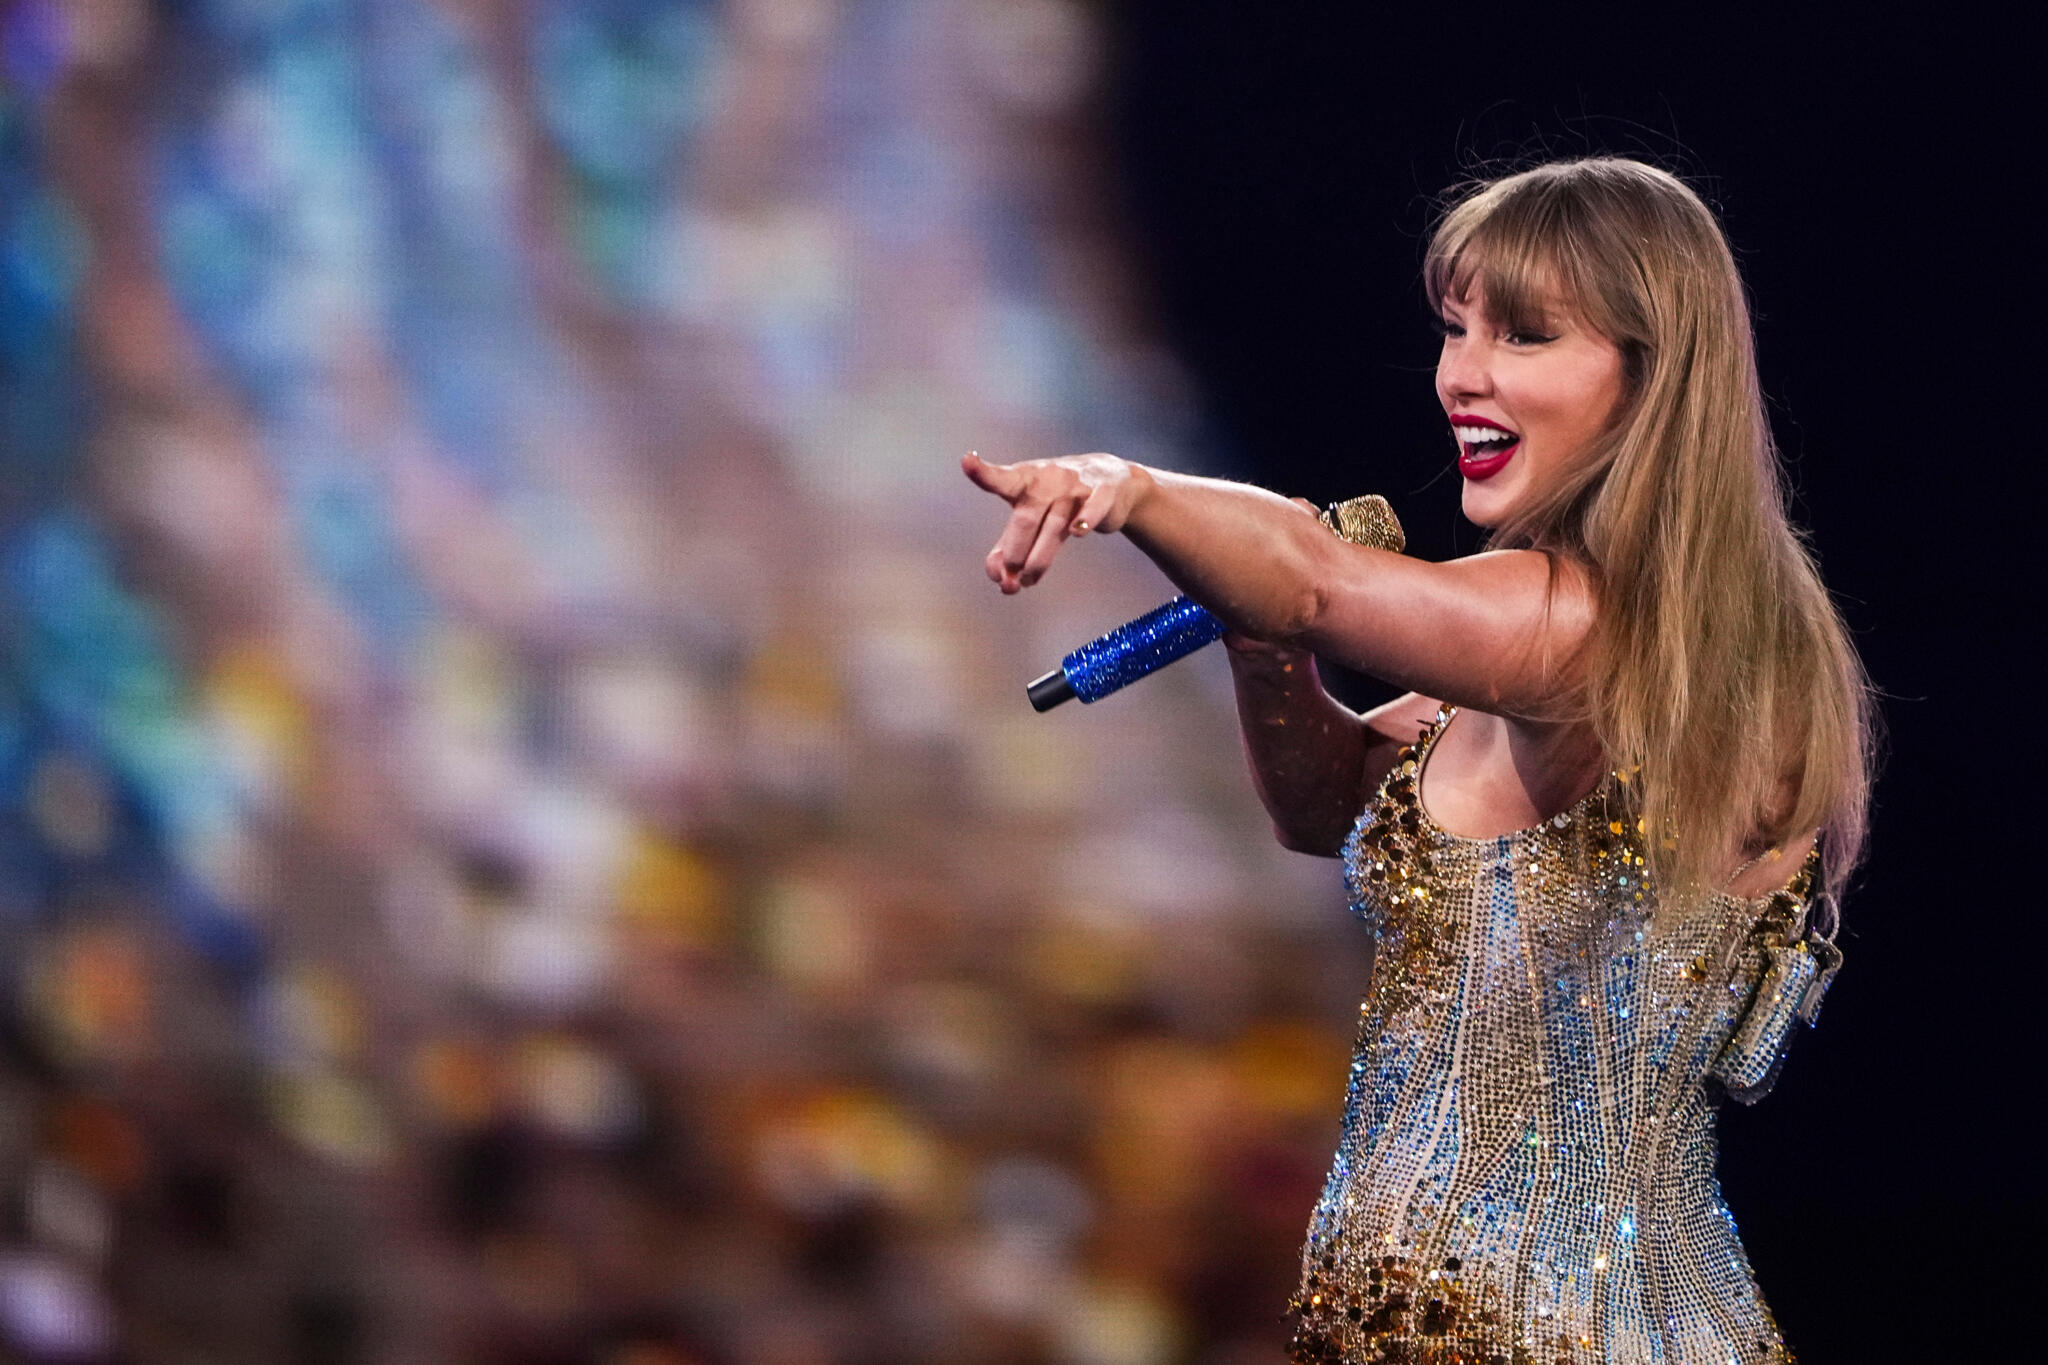
Taylor Swift Eras Collection Opens at Boston MFA April 2027, First Musician Exhibition
The Museum of Fine Arts in Boston will open "Taylor Swift: The Eras Collection" on April 10, 2027,...

No. 2 Maryland Faces Harvard in NCAA Semifinals at Trager Stadium
No. 2 seed Maryland takes the field Friday at noon against No. 3 seed Harvard in the NCAA...