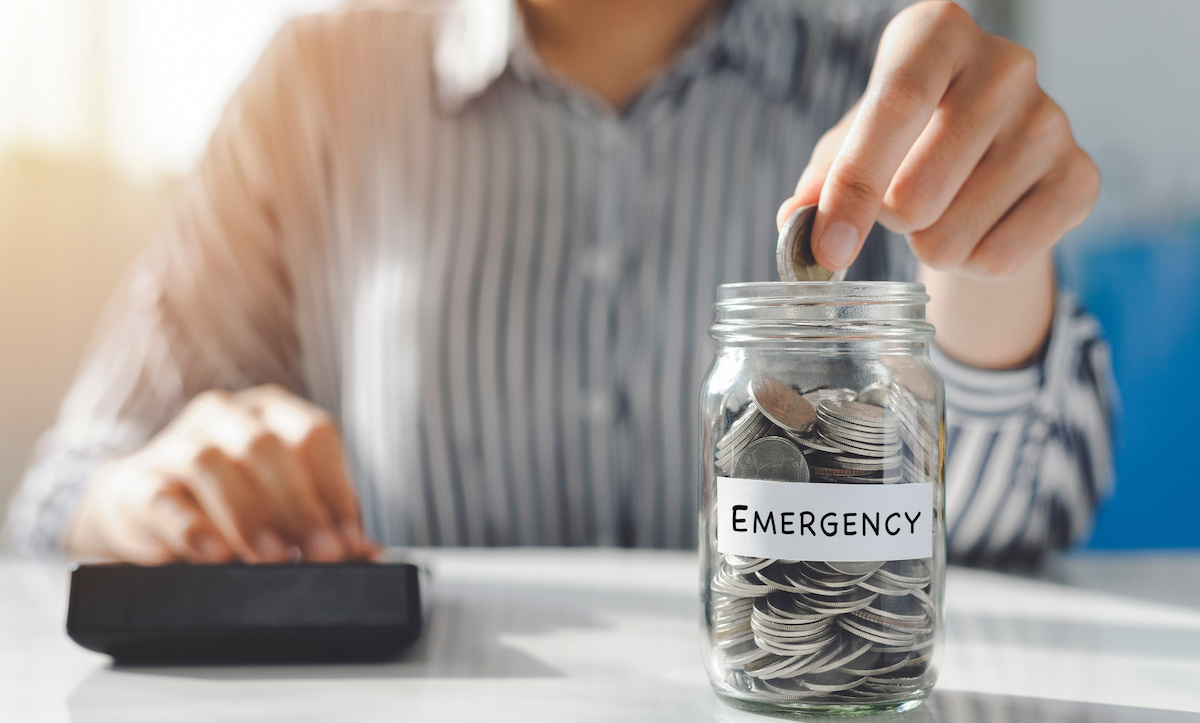
Gen X’s Automated Retirement Masks an Emergency Savings Crisis
Generation X has mastered the art of automated retirement savings, yet remains critically exposed to financial shocks due to a persistent failure to build emergency funds. PYMNTS Intelligence’s report, “Gen X’s Savings Split: Retirement on Track, Emergency Cash Running Short,” reveals a stark contrast: 41% of Gen X consumers saving for retirement use exclusively automated methods, while 56% of those saving for emergencies rely solely on manual, inconsistent efforts. This gap represents a significant vulnerability for a generation already burdened by caregiving responsibilities and stagnant wages, creating a precarious financial balance that could easily tip.
The Bottom Line:
- 56% of Gen X emergency savers use only manual methods, the highest rate among working-age generations.
- 38% of Gen X consumers have $1,000 or less in readily available savings, with 18% having none at all.
- 43% of Americans have cut back on 401(k) contributions to cover rising living costs, according to a TIAA survey.
The Alpha Metric: The $1,000 Emergency Savings Threshold
The single most critical data point in this financial narrative is the fact that 38% of Gen X consumers have $1,000 or less in readily available savings. This figure is the canary in the coal mine because it directly measures the buffer against unexpected life events—a job loss, a medical emergency, or a major car repair—which can instantly derail a family’s financial stability. This metric is amplified by the finding that nearly one in five Gen Xers have zero cushion at all. The inability to cover a modest $1,000 expense is not a minor inconvenience; it is a direct pathway to high-interest debt and a vicious cycle of financial fragility that can erase years of disciplined retirement saving.

Retirement Contributions Versus Short-Term Needs
For Wall Street, the automation of retirement contributions is a story of disciplined, long-term capital formation. Banks and asset managers see a reliable flow of funds. For Main Street, the reality is far more precarious. While Gen X has successfully automated retirement, the very same discipline is absent for short-term needs. This disconnect creates a dangerous liquidity trap. When an unexpected bill arrives, the automated retirement account is a last resort, not a first line of defense. The TIAA survey shows this pressure, finding that 43% of Americans have reduced or stopped 401(k) contributions to pay for daily expenses. Surya Kolluri, head of TIAA Institute, called this a “rational response.” He noted, “Let’s take the simple case of, ‘I have to pay the mortgage, and I have to contribute to my retirement, and I’m in a pinch. I have no freedom on the one. I have lots of freedom on the other.’” This is not a failure of will; it is a failure of financial infrastructure. The system rewards automation for long-term goals but offers no such smooth mechanism for building an emergency fund, forcing consumers into a high-stakes choice between immediate survival and future security.
This creates a systemic vulnerability. Generation X is financially disciplined in one area but completely exposed in another. The market has solved the retirement problem with automation but has failed to provide a parallel solution for liquidity.

The Market Opportunity for Financial Institutions
The financial services industry is beginning to recognize the opportunity embedded in Gen X’s savings shortfall. Banks and payment providers have the tools to bridge this gap, turning a generation’s financial weakness into a business opportunity. The report suggests several solutions: automatic transfers on payday, split direct deposits where a portion of the paycheck goes directly to savings, and savings features linked to debit card transactions that round up purchases and stash the change. These tools make saving passive, mirroring the success of payroll deductions for retirement. The key is to embed these features into the existing financial ecosystem, removing the cognitive load and friction from manual saving. The goal is to build reserves incrementally, as PYMNTS notes, rather than waiting for a lump sum deposit. Financial institutions that successfully integrate these automated savings tools into their platforms could capture significant market share while simultaneously helping a generation build the financial flexibility it desperately needs.
Smart Money Tracker: Institutional Sentiment
Institutional investors are likely to view Gen X’s financial behavior through a lens of risk and opportunity. On the risk side, the lack of emergency savings represents a potential drag on consumer spending and an increase in credit default risk. A sudden wave of unexpected expenses could strain household budgets, leading to a dip in discretionary spending—a key driver of economic growth. Conversely, companies providing automated savings and fintech solutions are poised for growth. The data shows a clear market need, and successful execution could lead to strong returns. The broader market sentiment, however, is cautious. The Conference Board Consumer Confidence Index shows Gen X confidence flatlining around 60 points, one of its lowest readings in five years, a signal that Wall Street is watching this demographic’s financial stress as a leading indicator of consumer health.
The Squeeze of the “Sandwich Generation”
Gen X’s financial anxiety is not abstract; it is a direct result of their unique position in the life cycle, often termed the “sandwich generation.” As the first generation to hit their 50s while simultaneously managing aging parents’ care and dependent kids’ expenses, they are at the bottom of the U-shaped happiness curve. The numbers are brutal. A 2024 Northwestern Mutual study found Gen X believes it needs $1.56 million to retire comfortably but has saved an average of just $108,600—a $1.45 million gap. This pressure is compounded by caregiving costs. A Bank of America report found that 35% of Gen Xers’ financial situation worsened while providing care, with out-of-pocket expenses averaging over $11,500. This dual burden of raising children and caring for parents leaves little room for error and makes the lack of an emergency fund even more dangerous.
Unlike younger generations who are starting to build wealth, Gen X is playing catch-up. Fortune notes that while Gen Z is disproportionately contributing to business growth, many Gen Xers are still grappling with the aftermath of the 2008 financial crisis and the rise of the 401(k) system, which replaced traditional pensions. This shift placed the onus for retirement savings entirely on the individual, a responsibility many were not adequately prepared for. The result is a generation that is both disciplined and desperate, saving for a distant future while living paycheck to paycheck.
The contrast between automated retirement savings and manual emergency savings is not a matter of preference; it is a matter of design. The retirement system is built for automation. Payroll deductions happen before a worker even sees their paycheck, making saving effortless. The emergency savings system, by contrast, relies on personal initiative. It requires active transfers, mental reminders, and leftover funds after bills are paid—a process that is prone to failure. This structural flaw is the root of Gen X’s financial vulnerability. The solution lies in redesigning the system to make short-term savings as automatic and frictionless as long-term savings.
Market Trajectory: From Crisis to Opportunity
The trajectory for Gen X’s finances depends on whether the financial industry acts on the insights from PYMNTS and other reports. The crisis is clear: a generation is saving for the future but unprepared for the present. The opportunity is equally clear: by using automation and embedded financial tools, banks and fintechs can help Gen X build a more resilient financial foundation. The market’s next move will determine whether this generation continues to teeter on the edge or finally secures the safety net it needs. The data has spoken. The question is whether anyone will listen.
Disclaimer: The information provided in this article is for educational and market analysis purposes only and does not constitute financial, investment, or legal advice. Always consult with a certified financial professional before making investment decisions.
Related reading
Democrat Joe Madge defeats Micah Caskey in SC House District 89
State Rep. Micah Caskey, R-West Columbia, lost his re-election bid to Democrat Joe Madge in House District 89...

Maya Wente named to NSIC first-team all-conference volleyball squad
Maya Wente Climbs to Augustana Volleyball's Elite Tier On Thursday, the Northern Sun Intercollegiate Conference announced its postseason...
Providence Teachers Union President pickets PPSD over unsafe heating conditions
Providence Teachers Rally as Cold Classrooms Spark District-Wide Crisis On an unseasonably warm Wednesday in November, the Providence...

Flyers Face Rangers After 4-2 Home Loss to Wild
On a night at the world's most famous rink, one number told the story. Twenty-five. On Tuesday, the...