
The IRS has set the 2026 IRA contribution limit at $7,500, with a $1,100 catch-up provision for savers 50 and older, and the clock is ticking toward the April 15, 2027 filing deadline, CNBC reported.
-
The Bottom Line:
- The 2026 contribution ceiling sits at $7,500 across traditional and Roth IRAs, plus an $1,100 catch-up for those 50 and older.
- Savers have until April 15, 2027 — not Dec. 31 — to fund the 2026 tax year, creating a 20-week window from the week of Nov. 23.
- Platform-specific matches from Robinhood and SoFi can add up to 3% on eligible contributions, but they carry holding-period strings that do not count toward the IRS limit.
From the week of Nov. 23, you have 20 weeks to work toward your savings goal.
A certified financial planner who reviews platform disclosures for clients said the match is effectively free alpha, but the five-year holding requirement on Robinhood Gold and the proportional clawback on SoFi turn liquidity into an opportunity cost.
Robinhood Gold members can earn a 3% match on contributions to self-directed IRAs, while standard Robinhood users receive 1%. SoFi Invest offers a 1% match on contributions and rollovers. Neither match counts toward the $7,500 IRS limit, but both impose a five-year holding period. An early withdrawal triggers a proportional fee that can wipe out the match entirely.

Robinhood Strategies managed IRAs are excluded from the match. SoFi charges a $25 annual inactivity fee waived by logging in every six months, and its automated investing tier carries a 0.25% advisory fee. Robinhood charges no management or commission fees on the IRA itself.
Betterment and Wealthfront automate portfolio construction, rebalancing, and tax-loss harvesting once the cash lands in the account. Betterment’s digital tier costs $5 monthly until assets hit $24,000 or recurring deposits reach $200 per month, then shifts to 0.25% annually. Wealthfront charges a flat 0.25% advisory fee with a $500 minimum deposit and offers daily tax-loss harvesting on all balances.
Neither platform contributes for you. The investor must still execute the deposit before the April 15, 2027 deadline. Missed weeks cannot be recovered retroactively.
Roth IRAs deliver tax-free growth and qualified withdrawals, but eligibility phases out at higher incomes. Traditional IRAs may offer an upfront deduction, deferring taxes until retirement when marginal rates could be lower.
Save $50 each week, and you’d contribute $1,000 by April 15, 2027. The math is unforgiving: compounding works only on dollars actually invested.
Disclaimer: The information provided in this article is for educational and market analysis purposes only and does not constitute financial, investment, or legal advice. Always consult with a certified financial professional before making investment decisions.
U.S. Marshals Arrest Philadelphia Abduction Suspect Olunkayode Taiwo in Connecticut
U.S. Marshals arrested Olunkayode Taiwo in Newington, Connecticut, on Thursday night, ending a weeks-long search for the 28-year-old...

Passenger Jumps From Vehicle During 100 MPH Pursuit Near Thompson; Two Arrested
Three miles of Interstate 29 near Thompson became a crime scene on Nov. 13 after a routine speed...

Five Authors Host Book Events Across New Hampshire This Weekend
Five authors will appear at bookstores, libraries and a theater across New Hampshire this weekend, offering talks on...
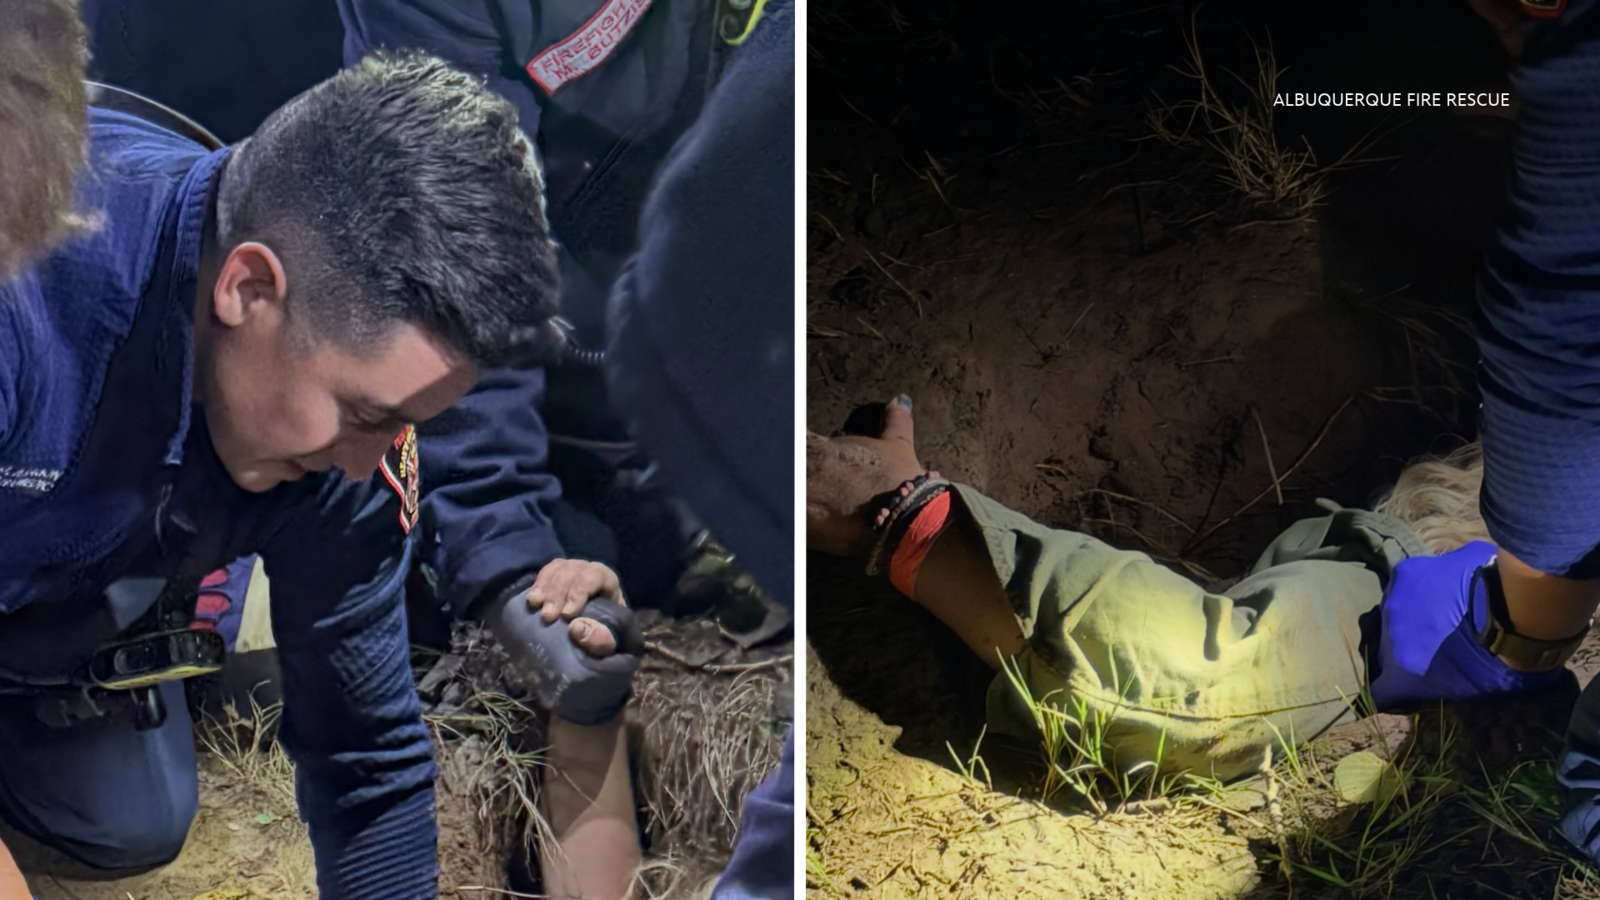
Woman Trapped Chest-Deep in Sinkhole on Rio Grande Bank After Fall Rains
Historic fall rains have turned Albuquerque's dry Rio Grande riverbanks into a trap, pulling a woman chest-deep into...