The United States government has quietly evolved into a significant shareholder in dozens of private companies, creating a sprawling, semi-invisible portfolio that blurs the line between public policy and private equity. Washington now holds equity stakes in approximately 40 companies, though the lack of a centralized official record has left the exact number in dispute among analysts and government agencies.
Rather than relying solely on grants or loans, the federal government is increasingly taking ownership slices—minority, non-voting stakes—as a condition for funding. For the average investor, this means the “invisible partner” in the room now influences everything from risk profiles to share dilution.
The Commerce Department expands its portfolio
The most recent expansion of this strategy occurred on October 22, 2026, when the Commerce Department signed letters of intent for $389 million in CHIPS Act research awards. The funding is earmarked for four private firms: Helion, which is in line for up to $175 million; Commonwealth Fusion Systems ($85 million); Vertical Semiconductor ($73 million); and Sibelco ($56 million). In exchange for these awards, the department is taking a minority, non-controlling, non-voting equity stake in each.
The scale of this holdings portfolio remains murky. Tad DeHaven, a policy analyst at the Cato Institute, puts the count of announced or completed stakes at 40. However, the Council on Foreign Relations counts 43, citing deals involving the Development Finance Corporation. This discrepancy exists because, as a Treasury spokesperson noted in July, different agencies report equity in different ways. There is no single, public ledger of what the U.S. government actually owns.
“Like a down payment on a sovereign wealth fund, which many countries have.”
Council Director Kevin Hassett
That is how National Economic Council Director Kevin Hassett described these stakes in July 2026.
Intel serves as the anchor holding
If the government’s portfolio has a crown jewel, it is Intel. In August 2025, the federal government agreed to purchase 433.3 million shares of Intel (NASDAQ:INTC) at $20.47 per share, a move costing roughly $8.9 billion funded through CHIPS Act grants and the Secure Enclave program. This gave Washington a 9.9% stake in the semiconductor giant.
The deal includes a five-year warrant allowing the government to buy another 5% at $20 a share, provided Intel stops owning at least 51% of its foundry business. With Intel closing at $93.74 on October 27, the government’s shares are now valued at approximately $40.6 billion.
Trading equity for Japanese capital
Under a U.S.-Japan plan announced October 14, Japan will provide up to $21 billion to finance two new 300mm plants for GlobalFoundries (NASDAQ:GFS) in Malta, New York, with the first plant expected to be operational by 2029. As part of this arrangement, the Commerce Department’s stake in the company will rise from about 3% to roughly 7%.
GlobalFoundries CEO Tim Breen described the move as a bold initiative for semiconductor manufacturing. While Donald Trump claimed on Truth Social that the stake is worth more than $2 billion, market calculations based on the October 27 value put that 7% stake closer to $1.8 billion.
Pentagon price floor fails to stabilize MP Materials stock
Not every federal investment is a windfall. The Pentagon’s deal with MP Materials (NYSE:MP) illustrates the friction between protecting a business and protecting a stock price. In July 2025, the Pentagon purchased $400 million of preferred stock in the rare earth producer, which pays a 7% dividend and converts to common stock at $30.03 a share. The Pentagon’s total ownership is capped at 19.9%.
To stabilize the supply of neodymium-praseodymium (NdPr), the government established a 10-year price floor of $110/kg. However, the stock market has remained volatile, trading between $37.11 and $76.80 over the last 52 weeks. MP Materials closed at $40.87 on October 27. If the stock dips below $37.11 before its November 5 report, it will likely prove that while a price floor can save a company’s operations, it offers limited protection to the actual shareholders.
Federal partnerships offer safety nets but risk shareholder dilution
For those holding these stocks, the presence of the U.S. government is a double-edged sword. On one side, federal partnership reduces the likelihood of total failure. Guaranteed buyers and price floors create a safety net that traditional startups lack. Furthermore, as seen with GlobalFoundries, the government can act as a catalyst for massive foreign direct investment.
The downside is dilution. When the government exercises warrants or converts preferred stock into common shares, it increases the total share count, potentially watering down the profits for existing investors. There is also the “informal pressure” factor. Even a non-voting stake gives Washington significant leverage over corporate decisions, such as where to build plants or whom to hire.
Moreover, these holdings are subject to political volatility. A future administration could decide to liquidate these stakes to fund other priorities or repurpose them to meet different geopolitical goals, creating a layer of political risk that doesn’t exist in purely private enterprises.
The coming days will provide a litmus test for this model. With Intel reporting on October 29 and MP Materials on November 5, the market will see whether the “sovereign wealth” approach provides a genuine floor for growth or merely a slow-motion dilution of private value.
Worth a look
BBG Youth Correspondent Jayli Interviews South Charleston City Council Candidate Karley Walker
In a recent interview, 23-year-old BBG Youth Correspondent Jayli sat down with Karley Walker, the Democratic candidate for...
Takeaways from Tennessee Lady Vols exhibition vs. Florida A&M – Sports Illustrated
The Tennessee Lady Vols delivered a statement win in their only exhibition game of the season, defeating Florida...
Study Ranks Milwaukee 8th Nationally In Spending on Fast Food
Milwaukee Ranks 8th Nationally in Fast Food Spending, Highlighting Deeper Economic and Social Divides Milwaukee residents spend an...
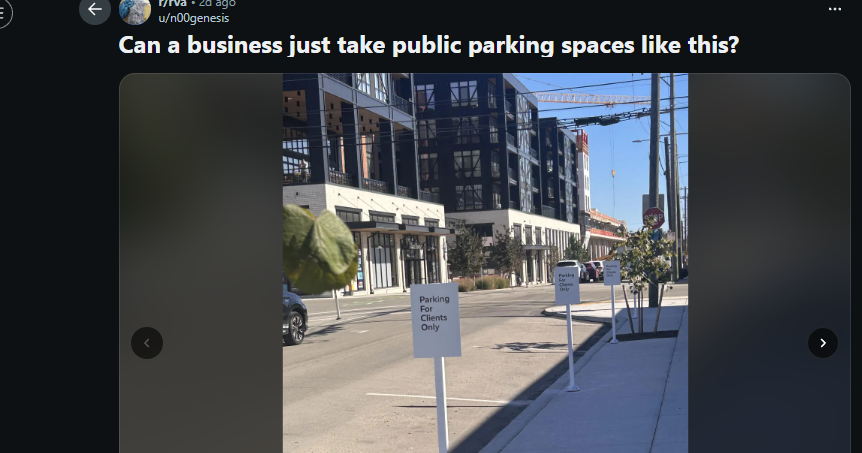
Miscommunication’ led to private parking signs on public Richmond street, landlord says
A miscommunication between a Richmond landlord and city officials led to the installation of private parking signs on...