Wisconsin has climbed to 6th place nationally in property tax competitiveness, up from 17th in 2020, according to data published by the Tax Foundation.
Wisconsin has climbed to 6th place nationally in property tax competitiveness, marking a sharp departure from its standing earlier in the decade according to data published by the Tax Foundation.
The state’s score rests at 7.96 out of 10 on the organization’s index, placing it well above the 50-state median. This positioning reflects an upward trajectory that has steadily gained momentum over recent years.
Backcast calculations under the current methodology show the state holding the 17th spot back in 2020. From there, the ranking shifted to 14th in both 2021 and 2022, moved to 12th in 2023, and then transitioned through 13th, 10th, and 7th places before reaching its current 6th-place standing for 2027.
Outperforming Regional Neighbors
When stacked against its immediate geographic neighbors, Wisconsin outranks every single bordering state in the property tax component. The evaluation measures the combined impact of real and personal property, inventory, estate, inheritance, and other wealth levies across two equally weighted categories: the rate subindex and the base subindex.
The rate subindex examines property tax collections as a percentage of personal income—which makes up 80 percent of that subindex score—alongside capital stock taxes. Wisconsin earned a rate subindex score of 6.75, ranking 26th nationally for that specific metric, driven by property tax collections at 5.94 percent of personal income alongside a top-tier score for capital stock taxes.
Meanwhile, the base subindex evaluates limitation regimes and the types of property taxes a state levies. Wisconsin secured a 9.17 score, good for 1st place nationally in the base subindex category.
| Component / Subindex | Score (0–10) | Rank |
|---|---|---|
| Property Taxes Score | 7.96 | 6 |
| Base Subindex | 9.17 | 1 |
| Rate Subindex | 6.75 | 26 |
| Collections as Share of Personal Income | 5.94 | 29 |
Base Variables Score Perfectly While Transfer Taxes Fail
The underlying data points reveal where the state captures its high marks. Wisconsin earned a maximum score of 10.00 across nearly all variables making up the base subindex, including tangible personal property taxes, inventory tax exemptions, de minimis thresholds, intangible property levies, and estate, inheritance, and gift taxes.
The Tax Foundation, which produced the index ranking Wisconsin sixth, was organized on December 5, 1937, in New York City by a group of corporate executives that included General Motors chairman Alfred P. Sloan Jr. and Standard Oil president William S. Farish.
Its first project helped defeat a tax increase in Westchester County, and by 1943 it had assisted in forming taxpayer associations in 35 states. The foundation relocated to Washington, D.C., in 1978 and is known for its State Tax Competitiveness Index and the Facts & Figures report, first published in 1941.
At the same time, real estate transfer taxes presented a stark contrast, pulling a 0.00 score and a 16th-place ranking in that specific narrow element. The overall framework evaluates variables as of July 1, 2026, capturing the structural adjustments that have lifted the state’s standing by 11 places since 2020.
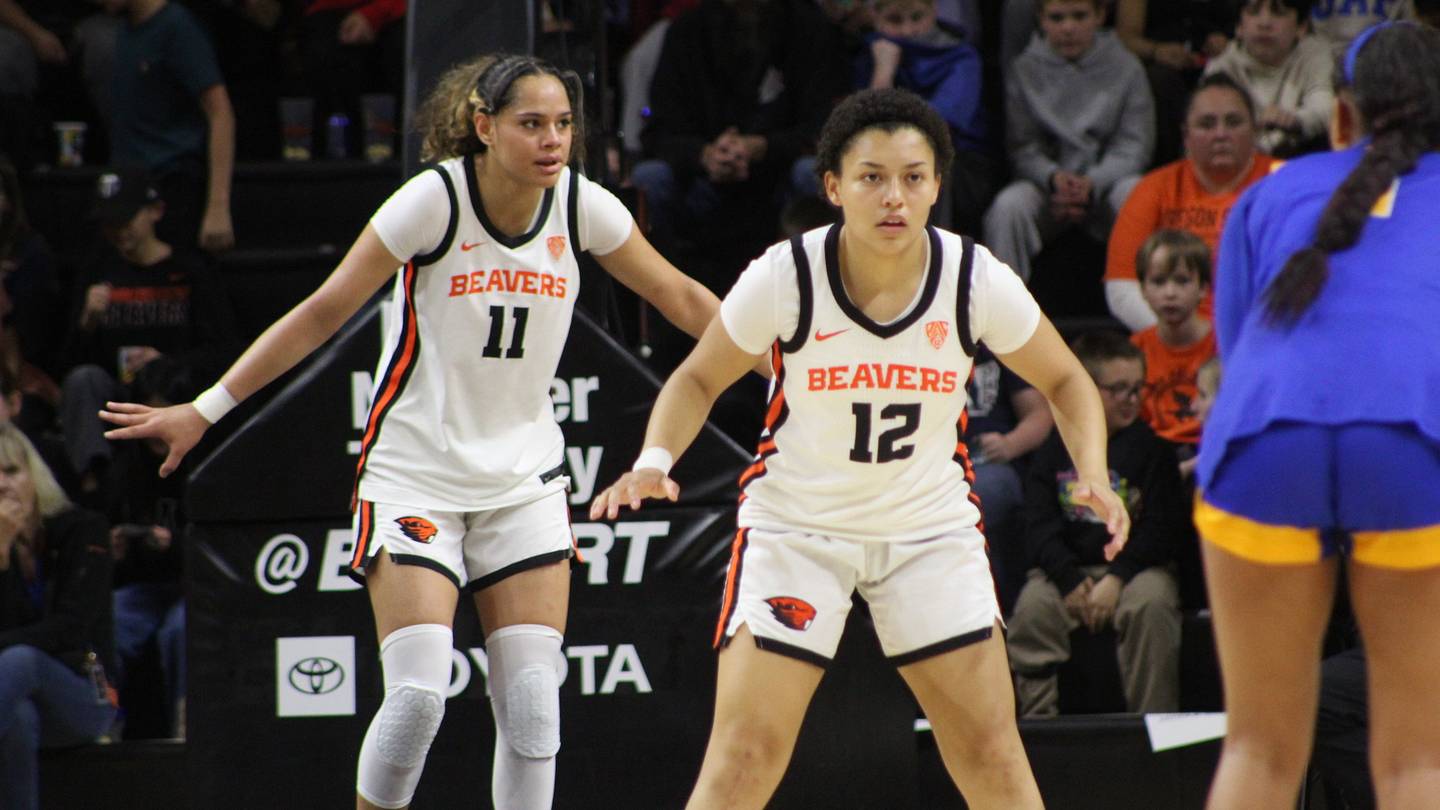
Oregon State Scrapes Past UC Riverside 64-57 at Gill Coliseum
Oregon State scraped past UC Riverside 64–57 on Wednesday afternoon at Gill Coliseum, leaving the Beavers 3–2 on...
Idaho Working Group Recommends Lottery, Loans, Asset Monetization for College Sports Funding
Idaho’s four public universities are staring down an $18 million hole at Boise State alone, and the governor’s...
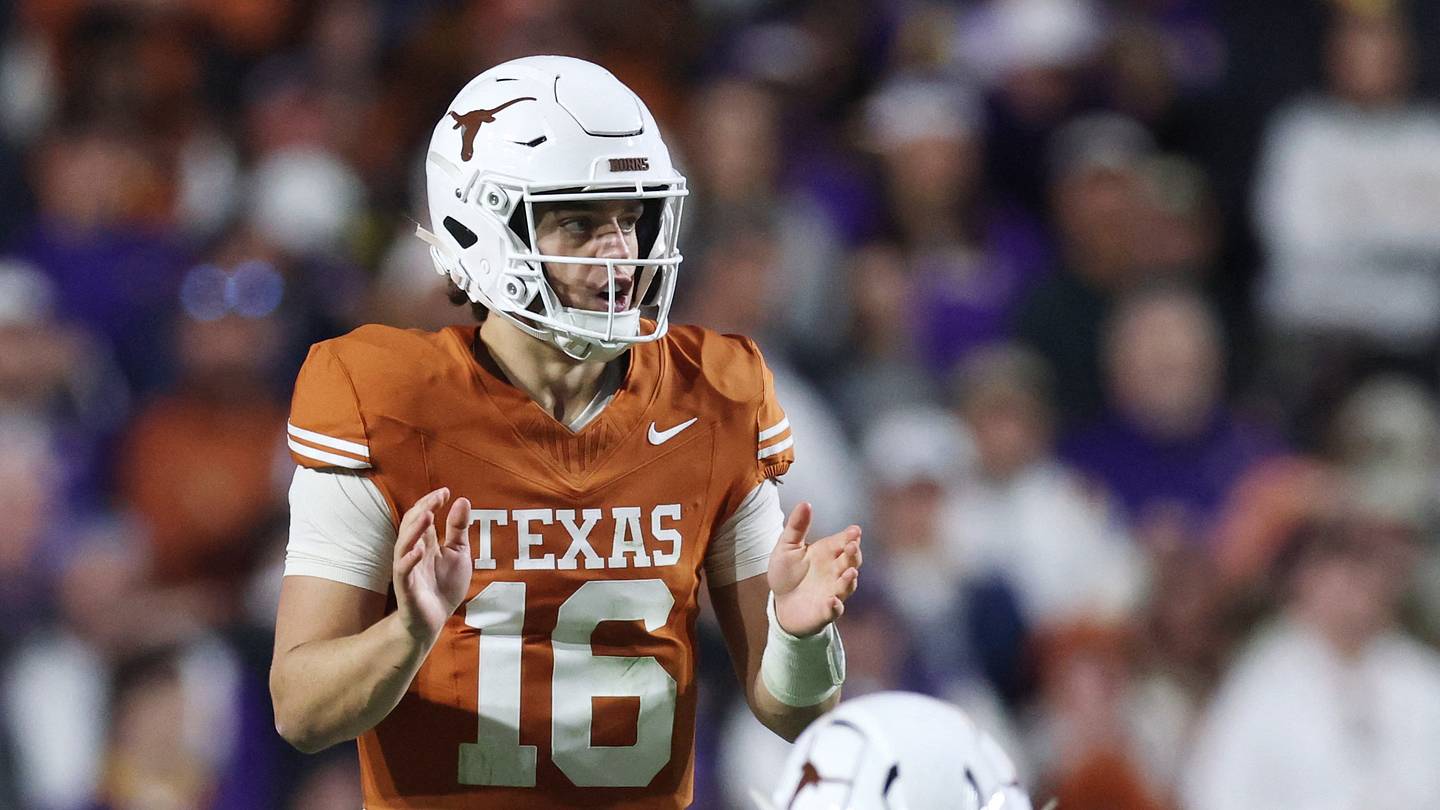
Arkansas DC Ron Roberts: Stopping Run Is ‘Surprisingly Simple’ Key to Slowing Arch Manning, No. 5 Texas
Arkansas defensive coordinator Ron Roberts has a surprisingly simple recipe for slowing down Arch Manning: stop the run...
Dorothy Louise Holston, 71, Atglen Educator and Valley Baptist Church Member, Dies November 12, 2026
"To be absent from the body is to be present with the Lord," the family of Dorothy Louise...