
Bank of England Rate Hike Pushes UK Borrowing Costs Higher as Inflation Accelerates
The Bank of England raised its Bank Rate by 0.25 percentage points to 4% on Thursday, a move that pushes borrowing costs up across the British economy as persistent inflationary pressures take their toll on households and financial markets alike. bbc.com reported that everyday borrowers are already feeling the direct pinch of these shifting macroeconomic conditions, with many facing immediate increases in their monthly housing expenditures. The central bank’s decision breaks a three-year period of relative rate stability and aligns with broader hawkish monetary policies adopted by major economies managing stubbornly high consumer prices.
The Bottom Line:
NEW Bank of England RAISES rates to 4% for first time in 3 years 8-1 vote (with 1 vote for 0.5% rise) Q3 GDP growth now forecast at 0.7% Inflation set for 4.9% in spring
- The Bank of England increased its benchmark interest rate by 25 basis points to 4%, citing growing inflationary momentum.
- UK consumer price index inflation reached 3.5% in September and is projected by the central bank to climb to approximately 5% by the middle of next year.
- Median full-time buyers face monthly mortgage commitments jumping from roughly £948 under 2021 conditions to about £1,612 today, driven by rates shifting from 1.95% to 5.65%.
Global Indices Plunge Amid Tech Sell-Off and Falling Crude Prices
Kitco.com noted that following the Bank of England’s announcement, spot gold held solid gains above critical support levels, trading at £3,065.90 an ounce—up 1.70% on the day.
The Divergence Between Wages and Mortgage Servicing Costs
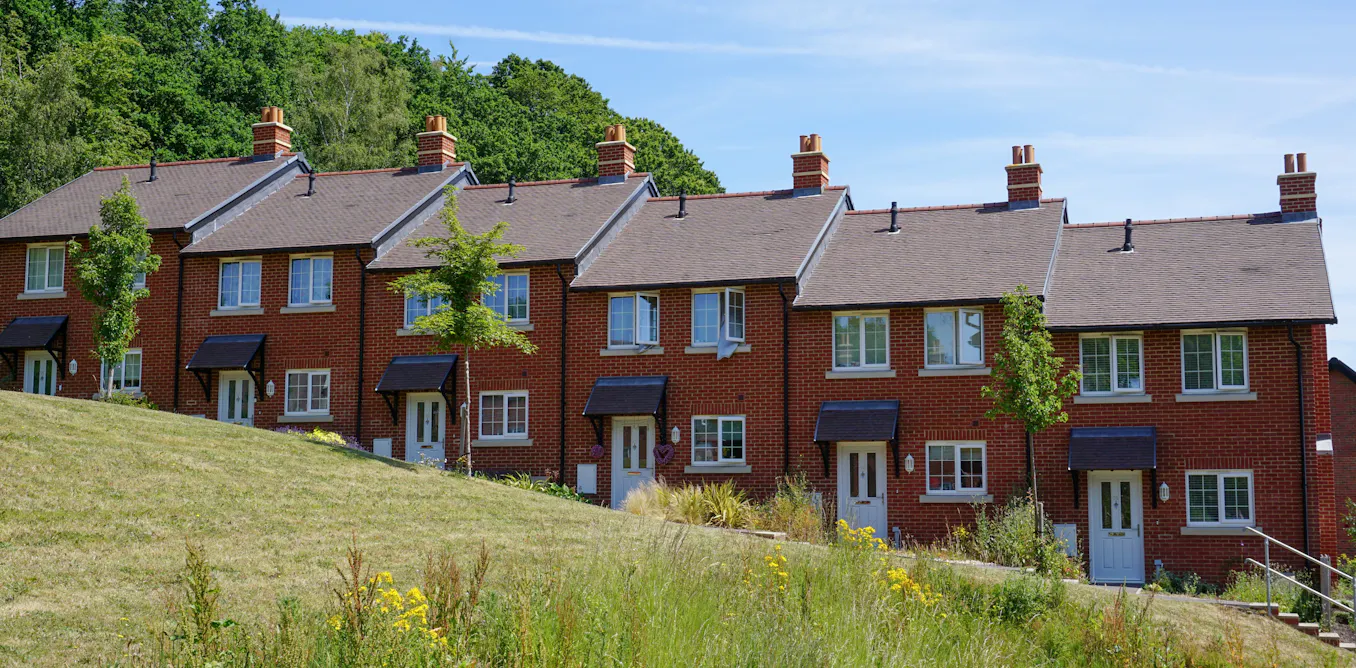
While official labor market data shows annual earnings rising faster than property valuations over recent years, the actual mechanics of home affordability have deteriorated sharply for average earners. According to analysis published by The Conversation, annual earnings between 2021 and 2025 increased by 25%, whereas residential property prices in England rose by roughly 15%. However, this traditional comparison overlooks the punishing impact of higher financing costs on monthly household budgets.
As widely expected, the Bank of England hiked interest rates by 25 bps. The vote was 8-1, with one dissenter pushing for 50 bps. The policy move comes alongside a warning that inflation could peak at 4.9% next year.#economy #markets #boe @bankofengland #centralbanks
Consider a dual-income household earning the median full-time salary. In 2021, their combined earnings stood at approximately £62,900. Purchasing a £250,000 property with a 10% deposit required a £225,000 mortgage. At an interest rate of 1.95%, monthly repayments over 25 years were roughly £948, consuming 18.1% of their monthly income. Fast-forward five years, and their combined earnings have advanced 25% to £78,600, while property values have ticked up 15% to £287,500. Yet with mortgage rates hovering near 5.65%, monthly repayments have surged to approximately £1,612—devouring 24.6% of their monthly income.
“Monetary policy is not on a pre-set path. The Committee will continue to assess the evidence at each meeting, in particular how likely high energy prices are to feed through to other prices and the economy more broadly,” the Bank of England stated in its official policy release.
The Broader Consumer Squeeze and Capital Allocation
Beyond baseline mortgage adjustments, concurrent inflationary pressures across food, energy, and transport sectors continue to compress household disposable income. The Conversation notes that securing a £300,000 property requires a £30,000 deposit alone, excluding stamp duty, legal expenses, and moving costs. This dynamic exacerbates a widening socioeconomic divide between prospective buyers reliant entirely on personal savings and those receiving direct familial financial support.
With the Bank of England projecting that headline inflation will peak near 5% next year before gradually moderating toward its medium-term 2% target, commercial banks and retail lenders are actively repricing loan portfolios.
Disclaimer: The information provided in this article is for educational and market analysis purposes only and does not constitute financial, investment, or legal advice. Always consult with a certified financial professional before making investment decisions.
Andrew Bailey, Bank of England Governor told my colleague @annaefoster on Today that “The probability of us having to increase interest rates at least once more is probably reasonably high" with no Middle East resolution and oil/ gas prices remaining where they are… also said…”
More on Bank of England
- United Dreamliner Returns to Chicago After Cockpit Windshield Crack
- South Carolina Volleyball Falls to No. 4 Florida in Straight Sets
- Rate Rise Adds About £31 a Month on £200,000; Leaving 1.58% About £460 (daybreakwire.com)
- Fin Smith fit to start for England in autumn opener against Australia (newsarchyuk.com)
United Dreamliner Returns to Chicago After Cockpit Windshield Crack
United Airlines Flight 219, a Boeing 787-10 Dreamliner headed from Chicago to Honolulu, was forced to return to...

South Carolina Volleyball Falls to No. 4 Florida in Straight Sets
Florida Volleyball Downs South Carolina in Straight Sets The South Carolina volleyball team faced a formidable challenge at...
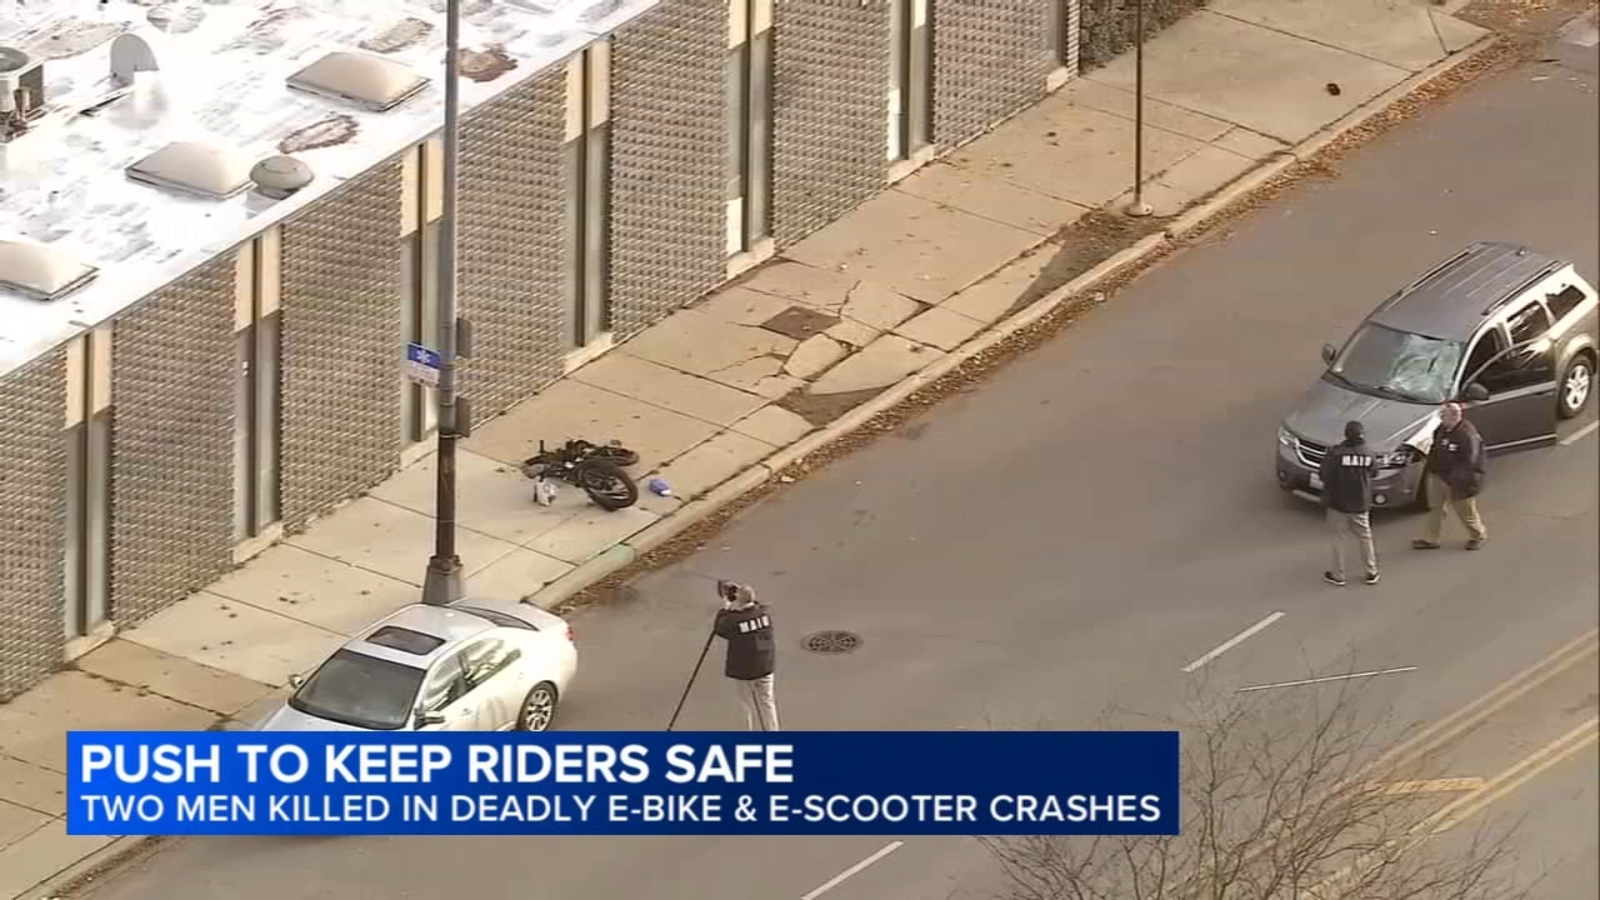
Two Fatal Chicago Crashes Involving E-Bike and E-Scooter Spark Safety Concerns
Two Fatal Collisions in Two Days Ignite Urban Safety Concerns Chicago streets have seen a harrowing 48-hour span...
Faces of Arkansas: Floyd Brantley’s Century of Service and Resilience
A Century of Service: Floyd Brantley Named November Face of Arkansas In the quiet halls of the Arkansas...