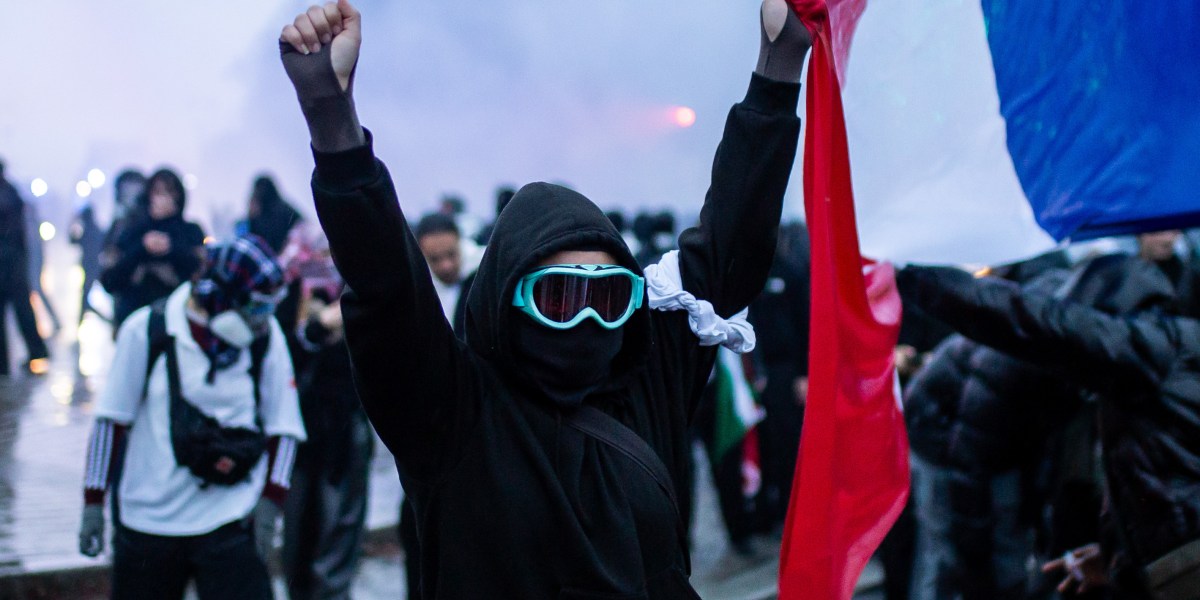
When U.S. markets watched Paris implode on October 17, 2026, as roughly 550,000 demonstrators marched against the high cost of living, the immediate consensus reaction across Wall Street was straightforward: “Let’s not do that.”
The Bottom Line:
- France’s public debt sits at 116% of GDP, with 30-year bond yields topping 5.4%, creating a widening fiscal chasm that has pushed the nation’s 10-year borrowing spread over Germany to nearly 160 basis points.
- The French government faces mounting debt-service costs, projecting annual interest payments to exceed €91 billion by 2027 and potentially reach €132 billion by 2030, while attempting to finance a €54 billion fiscal adjustment package.
- In contrast, the U.S. operates at roughly 100% debt-to-GDP with a real GDP growth rate above 2%—dwarfing France’s stagnant 0.4% Q2 growth and providing American policymakers more room to maneuver.
The Macroeconomic Reality Behind French Social Unrest
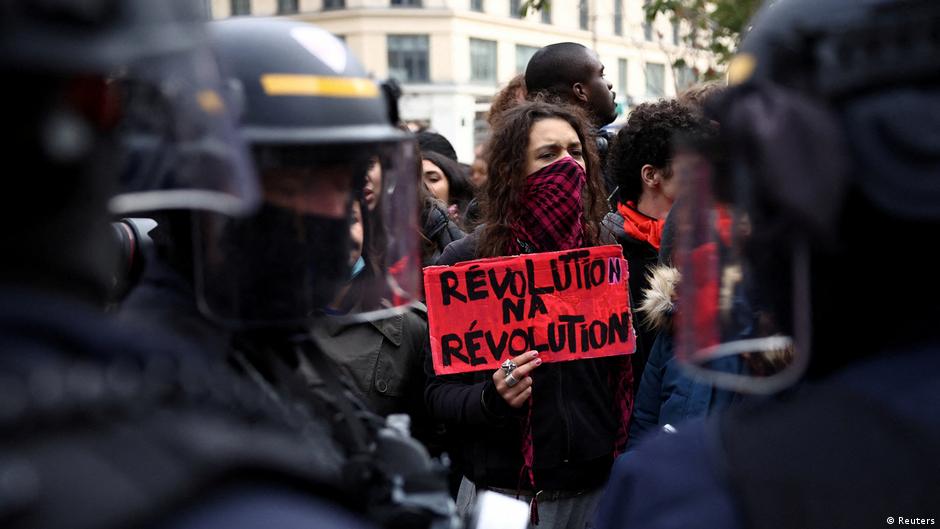
The macroeconomic health underpinning France’s current unrest leaves little room for error. National unemployment sat at 8.3% in the second quarter of 2026, real GDP growth limped along at 0.4%, and wage growth crawled at 1.7%. The government of Prime Minister Sébastien Lecornu proposed a 2027 budget featuring a €54 billion fiscal adjustment, signaling aggressive spending cuts that triggered violent pushback from students and union workers alike.
Compounding the fiscal strain, the cost of servicing French sovereign debt has skyrocketed. In February 2026, Paris paid only about 60 basis points more to borrow than Berlin did. By the end of October, that spread widened to nearly 160 basis points as the yield on France’s 10-year bonds breached 5% for the first time since 2002. France is expected to pay more than €79 billion in debt service for 2026 alone, with projections climbing past €91 billion in 2027 and reaching up to €132 billion by 2030.
Meanwhile, structural pressures continue to strain public finances, notably a pension system that consumes a staggering 14% of the country’s GDP. The core state pension guarantees up to 50% of a worker’s average salary over their top 25 earning years, augmented by mandatory occupational schemes to deliver a net replacement rate around 72%. Attempts to raise the retirement age have consistently run into fierce political resistance, leaving governments trapped between rigid entitlements and soaring liabilities.
Differentiating U.S. Fiscal Headroom from European Stagnation
Despite mounting anxiety over federal borrowing in Washington, American policymakers operate within a fundamentally different financial cushion than their European counterparts. Speaking at a Bipartisan Policy Center event, Heather Long, chief economist at Navy Federal Credit Union, pointed out the critical structural indicators separating the two economies. While the U.S. sits at roughly 100% debt-to-GDP and maintains a growth rate just above 2%, France sits further along the crisis curve at roughly 120% debt-to-GDP with growth hovering near 0.5%.
Tax capacity provides another stark divider. Per data from the OECD, the French tax wedge—the gap between an employer’s labor costs and an employee’s net take-home pay—stands at 47.2%. The United States sits considerably lower at 30%. Because France has largely exhausted its revenue-generating capacity through taxes, its government faces severe constraints in attempting to tax its way out of its debt spiral.

The question of repayment is one budget experts are asking, with the consensus that households with relatively high lifetime incomes will have more of a share of the adjustment. In France, that generational frustration is already fueling the unrest in the streets, serving as a warning sign for other Western nations grappling with escalating deficits.
Sovereign Spreads and the Danger of Deferred Adjustments
The absence of immediate currency adjustment mechanisms within the eurozone has further masked underlying structural imbalances. Landry Charrier, a researcher at the University of Bonn, explained that the euro historically provided easy access to cheap financing for France, softening the immediate pressure to adjust that once came from currency devaluations and declining purchasing power. Without those instant market signals, political debates in Paris have frequently operated divorced from economic reality.
Similar fiscal pressures are quietly building across the channel and borders. In the United Kingdom, public debt is projected to hit roughly 95% of GDP by the end of 2026, while state pensions face upward adjustments. Germany is likewise confronting a sharp rise in federal interest payments that threaten to triple by the early 2030s.
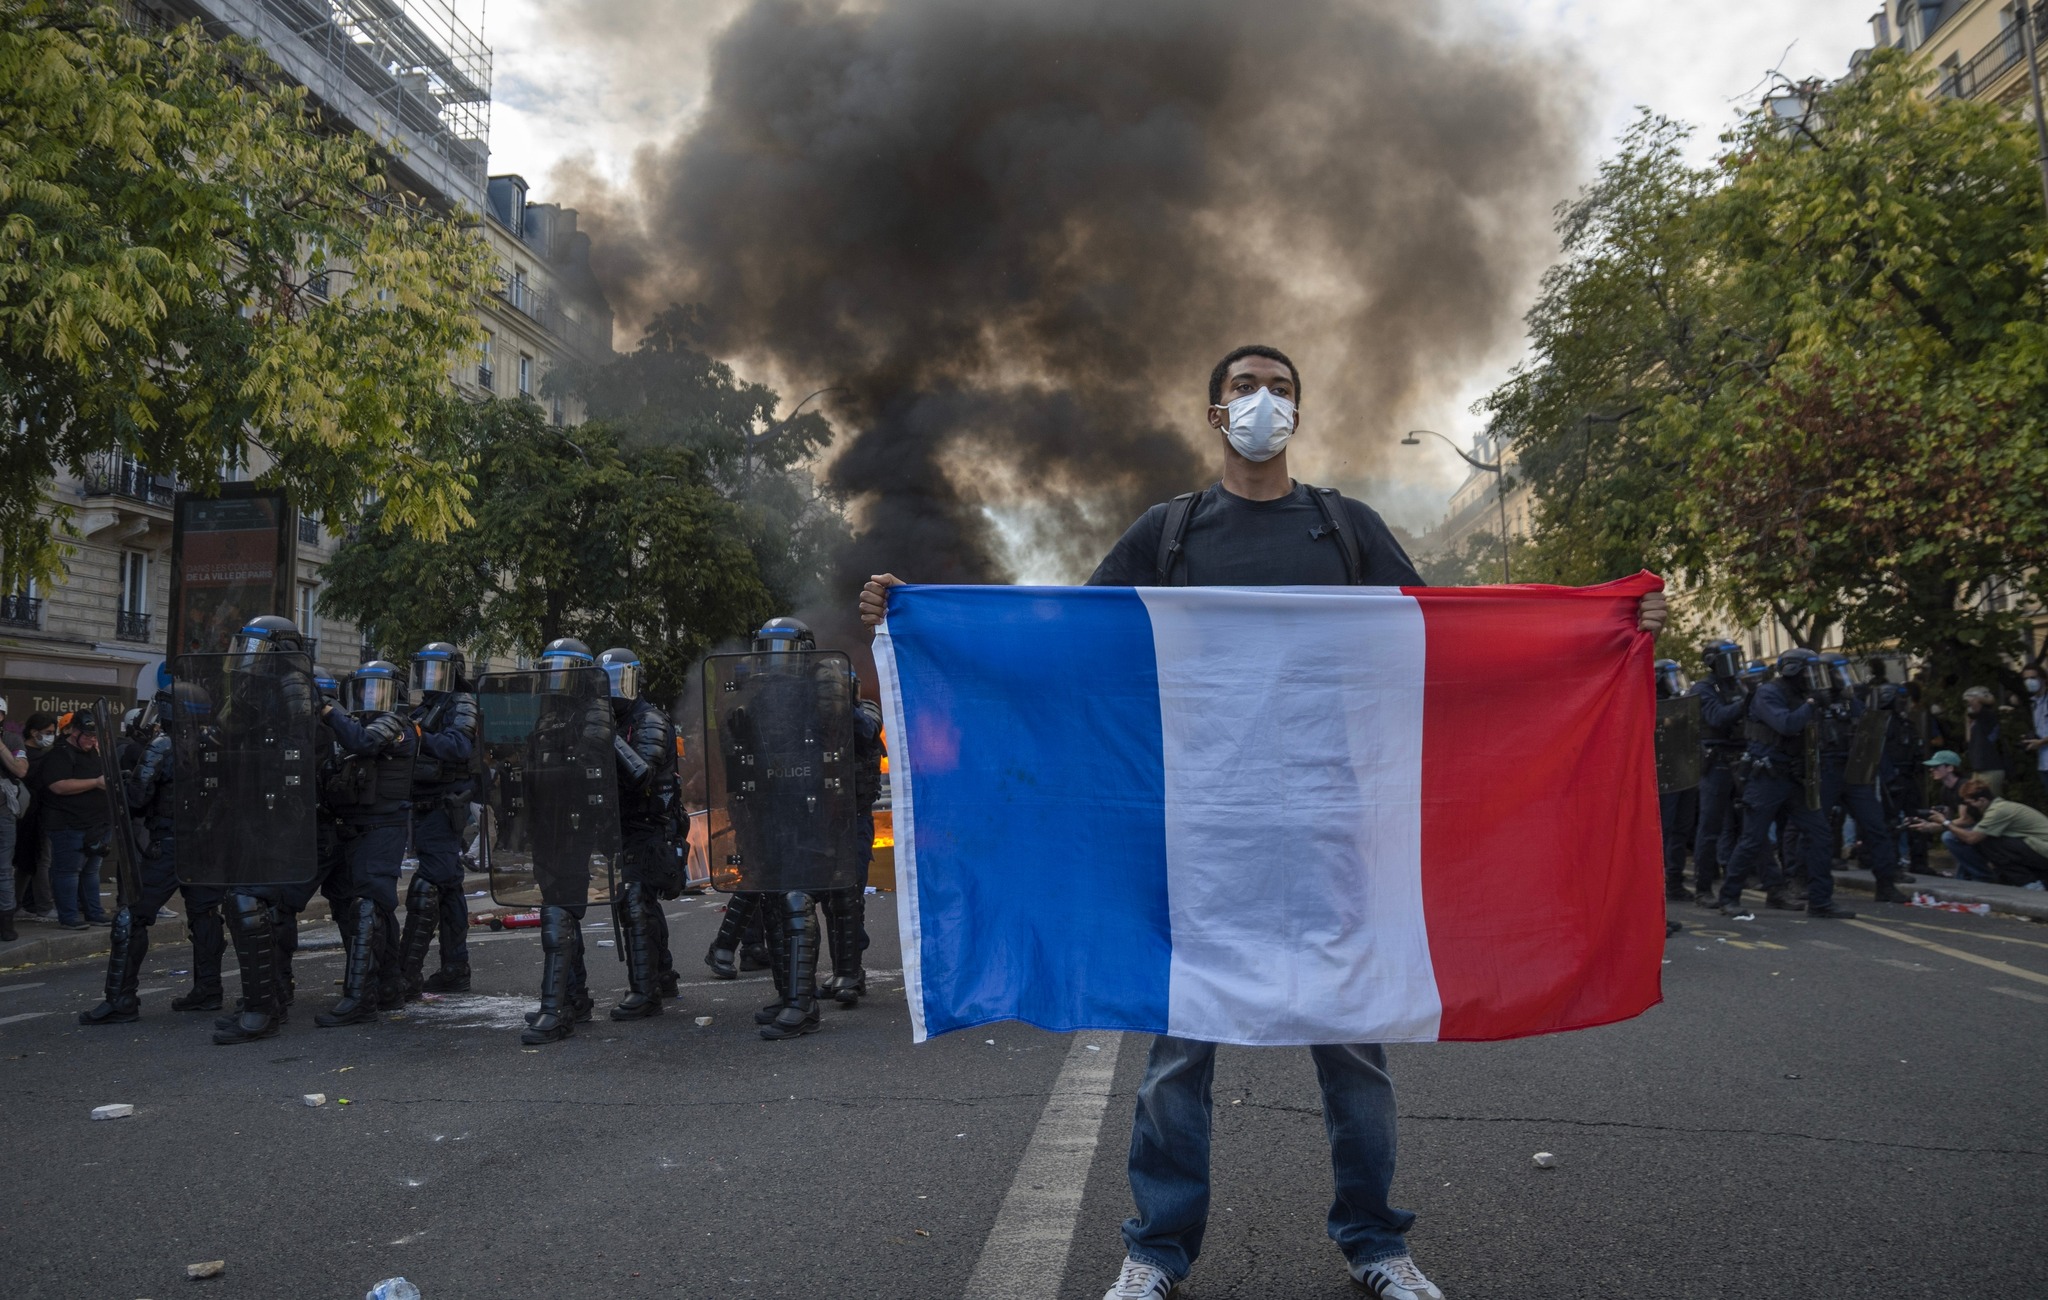
As bond markets monitor sovereign debt trajectories, the immediate focus turns to how parliamentary coalitions manage upcoming budgetary votes and whether fiscal tightening can proceed without triggering further civil disruption. The next definitive test arrives with the legislative debates over the 2027 French budget cycle, which will test whether the Lecornu government can defend its spending caps against sustained political opposition.
Disclaimer: The information provided in this article is for educational and market analysis purposes only and does not constitute financial, investment, or legal advice. Always consult with a certified financial professional before making investment decisions.
New Mexico beats Northern Arizona 94-65 to move to 2-0
Jake Hall Paces New Mexico Past Northern Arizona 94-65 “It was good to get a positive result here...

West Michigan Forecast Predicts Mild Weather Before Midweek Rain
WEST MICHIGAN — Residents across West Michigan are wrapping up the weekend with a quiet weather pattern before...

Family and Friends Honor Pilot Jeff Gregory at Celebration of Life
Family and Friends Remember Pilot Jeff Gregory at Montgomery County Celebration of Life On Saturday morning, loved ones...

Supreme Court Permits Limited Green Fireworks Use During Diwali
Air quality index readings reached 387 on Friday as India's Supreme Court permitted the limited use of green...