
North American Construction Group (NOA) delivered a mixed financial report for the third quarter of 2026, balancing revenue growth against operational hurdles.
While the company raised its full-year 2026 revenue outlook to a range of CAD 1.7 billion to CAD 1.8 billion, it simultaneously lowered its adjusted EBITDA midpoint from CAD 400 million to CAD 385 million.
The company, which specializes in heavy civil construction and contract mining, reported combined revenue of CAD 438 million for the quarter ended September 30. This represents a CAD 47 million increase over the same period last year, a surge largely driven by the acquisition of IMC, which contributed CAD 74 million to the quarter’s results.
However, the bottom line felt the pressure of specific project failures. As reported by MarketBeat, the company recorded a CAD 50 million pretax impact stemming from a joint venture project in Fargo. Management cited delayed completion, schedule disruptions, and rework as the primary culprits. CFO Jason Veenstra noted during the earnings call that the project is now in a contract loss position, requiring the full loss to be recognized immediately.
The company’s performance diverged sharply by region. Australia, a key market, saw its gross profit margin dip to 11.9%, falling well below the company’s typical 15% to 20% range. According to transcripts from StockAnalysis, this decline was exacerbated by a pit wall failure at a Western Australia site and roughly CAD 10 million in unexpected maintenance costs at a major Queensland location.
In contrast, the Canadian segment showed resilience. Gross profit margins there improved to 10.5% from 7% in the previous quarter. Veenstra attributed this gain to improved maintenance capabilities and fleet efficiency initiatives, alongside strong demand within the oil sands sector.
“The EBITDA revision reflects third-quarter operational challenges while retaining expectations for a strong fourth quarter,” said President and CEO Barry Palmer.
Despite the Fargo-related losses, North American Construction Group has many upcoming projects. The company reported a contractual backlog of approximately CAD 3.2 billion as of September 30, with a bid pipeline exceeding CAD 15 billion. Looking toward 2027, management anticipates roughly 10% organic revenue growth, assuming no further major project disruptions.
For investors, the primary concern is the company's debt. Net debt currently sits at CAD 1.1 billion, resulting in a trailing 12-month net debt to EBITDA ratio of 3.0 times. Management intends to prioritize free cash flow toward debt reduction, with a medium-term goal of bringing the debt ratio down to 2.0 times.
The company is also preparing for a leadership transition. Brad Rogers is set to step into the roles of president, CEO, and director on December 1, taking over from Barry Palmer. This change marks the end of Palmer’s tenure, with the company emphasizing a focus on maintaining continuity in capital allocation and customer relationships as it moves into the next fiscal year.
Related reading

Wyoming’s Barrasso, Hageman and Gray Face Democrat-Led Congress
Wyoming’s Republican Delegation Faces Shift to Minority Power When the new Congress convenes this January, Wyoming’s all-Republican congressional...
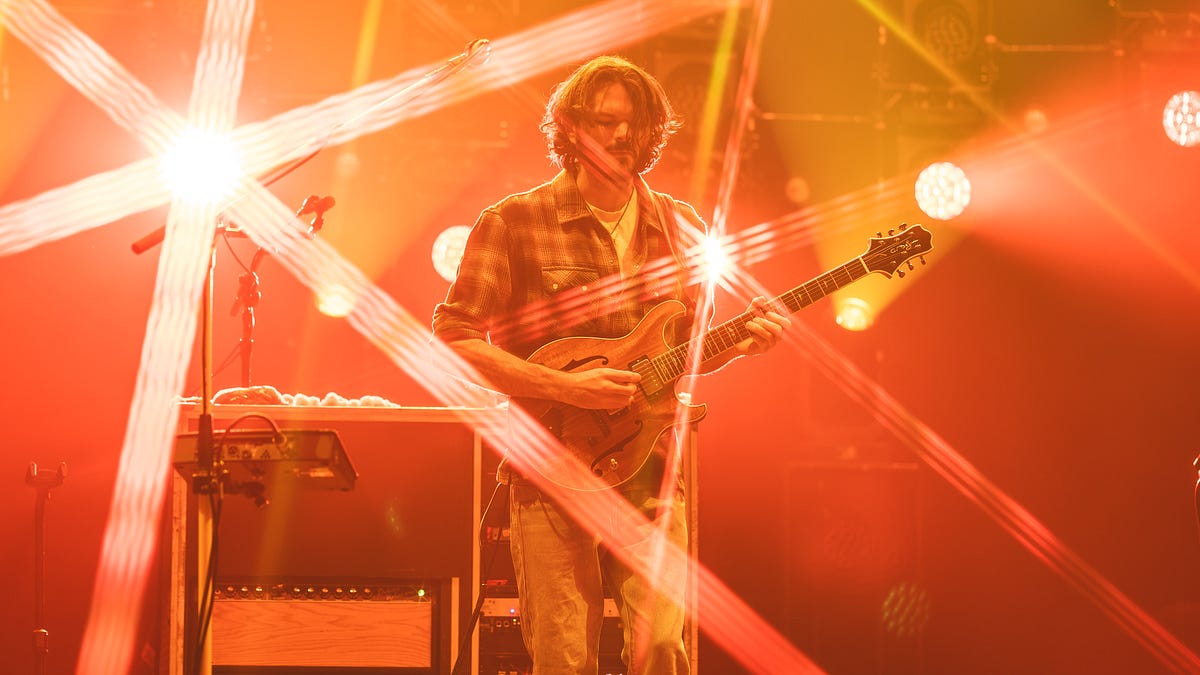
Goose Delivers High-Energy Funk Set at Milwaukee’s Miller High Life Theatre
Goose returned to the Miller High Life Theatre in Milwaukee on November 7, 2026, for the second of...
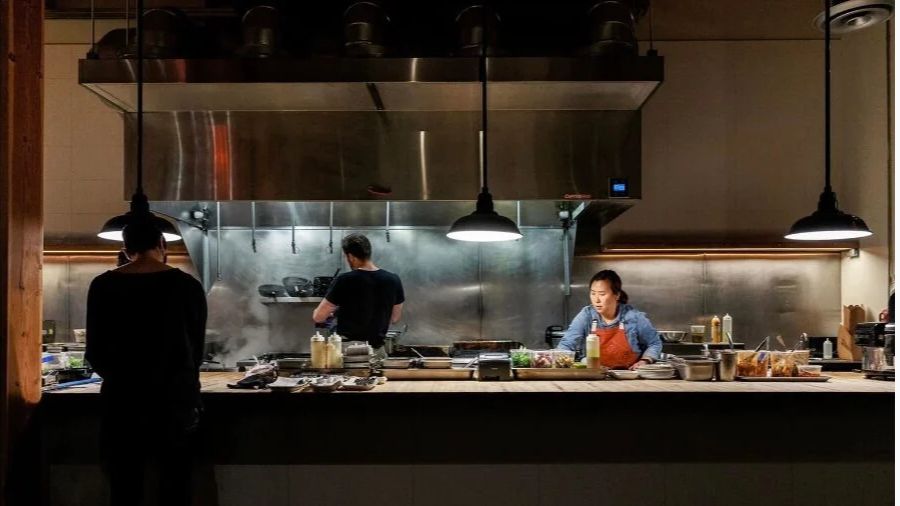
KIRO Hosts Discuss Revel Closure and Seattle Dining Costs
The landscape of Seattle’s dining scene is shifting, and for many residents, the change is hitting home in...
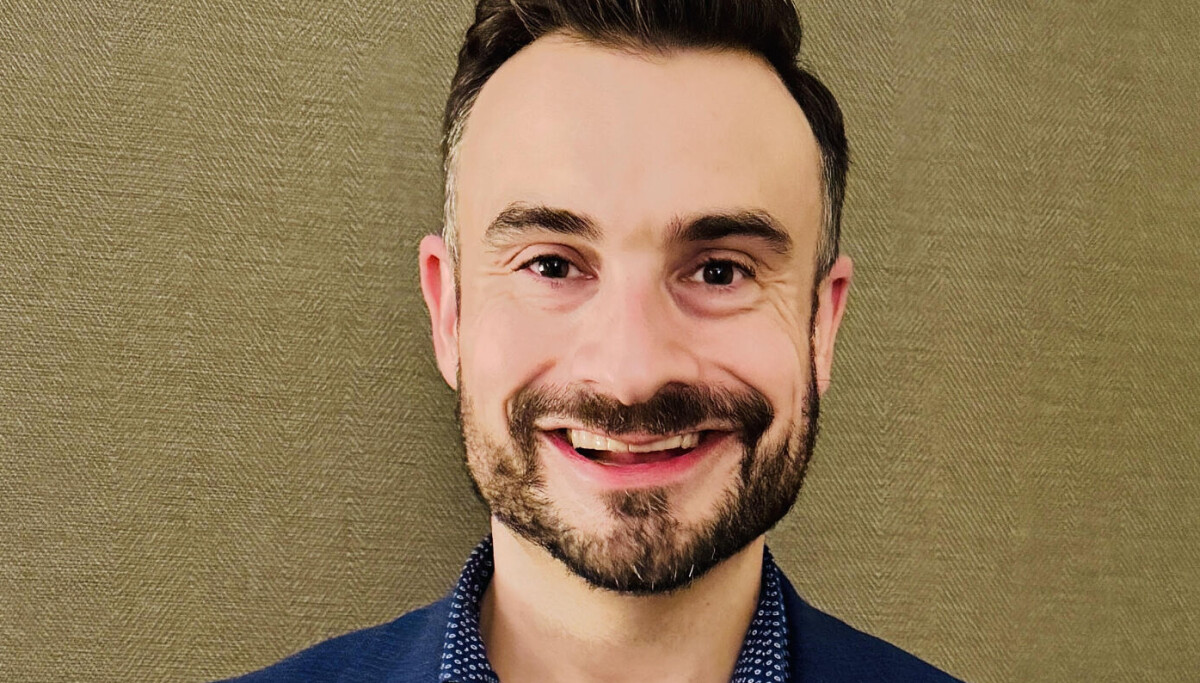
Matt Harrington Named 2026 VermontBiz Rising Star Alumni of the Year
Matt Harrington Named 2026 Rising Star Alumni of the Year The Southwestern Vermont Chamber of Commerce CEO Matt...